ASC 842 Disclosure Requirements: Complete Guide & Checklist
What disclosures are required under ASC 842?
ASC 842 requires qualitative and quantitative information about leases, including relevant assets and liabilities, lease costs, future payment commitments, cash flow information, weighted-average metrics, and significant accounting judgments.
ASC 842 disclosure requirements help financial statement users understand a company's lease obligations, related expenses, and future cash flow commitments. Under the standard, organizations must provide both quantitative and qualitative information about their operating and finance leases.
These disclosures go beyond reporting right-of-use (ROU) assets and lease liabilities on the balance sheet. Companies must also explain lease costs, payment obligations, significant accounting judgments, and other information that affects their financial reporting.
For businesses managing multiple commercial properties, preparing accurate disclosures requires complete lease information, consistent accounting calculations, and coordination between real estate and finance teams.
This guide explains the main ASC 842 disclosure requirements, provides practical reporting examples, and includes a checklist finance teams can use before finalizing their financial statements.
What Are ASC 842 Disclosure Requirements?
ASC 842 establishes the financial reporting disclosures required for lease arrangements under U.S. Generally Accepted Accounting Principles (GAAP).
The standard's disclosure objective is to help financial statement users assess the amount, timing, and uncertainty of cash flows arising from leases.
To accomplish this, lessees must provide information about their leases, significant accounting judgments, and lease-related amounts recognized in their financial statements.
These requirements apply to both operating and finance leases, although certain disclosures must distinguish between the two classifications.
For example, a retail company operating 100 leased stores may report substantial lease liabilities on its balance sheet. However, those balances alone do not explain when payments become due, how expenses are recognized, or which renewal options may affect future obligations.
ASC 842 disclosures provide the additional context needed to understand those commitments.
Organizations should consider materiality when determining the appropriate level of detail. Excessive information can make disclosures difficult to understand, while insufficient information may obscure important financial risks.
For a broader explanation of lease classification and recognition requirements, see Occupier's ASC 842 guide.
What Are the Two Main Types of Lease Disclosures?
ASC 842 lease disclosures fall into two broad categories: quantitative and qualitative information.
Both are necessary because financial amounts alone cannot fully explain how an organization manages its lease obligations.
Disclosure type Purpose Common examples
Quantitative Communicates measurable financial information Lease costs, asset balances, liabilities, maturity schedules
Qualitative Explains contractual arrangements and accounting judgments Renewal options, variable payment terms, discount rate
Quantitative disclosures show the financial impact of leasing activities, while qualitative disclosures help readers understand the underlying agreements and accounting decisions.
For instance, a company may disclose $20 million in operating lease liabilities and separately explain that several significant leases contain renewal options excluded from the current measurement.
Together, these disclosures provide a more useful picture of the company's financial commitments.
Quantitative Disclosure Requirements Under ASC 842
Quantitative disclosures communicate the financial amounts associated with a company's leasing activities.
They generally include recognized lease balances, lease-related expenses, cash flow information, and future payment commitments.
ROU Assets and Lease Liabilities
ASC 842 generally requires lessees to recognize ROU assets and lease liabilities for qualifying operating and finance leases.
Operating and finance lease balances must be separately presented on the balance sheet or disclosed in the notes.
If the balances are not presented separately, the company must identify the relevant balance sheet line items containing them.
This distinction matters because ASC 842 does not require every lease asset and liability to appear as an individual balance sheet line item.
For example, a company might disclose the following:
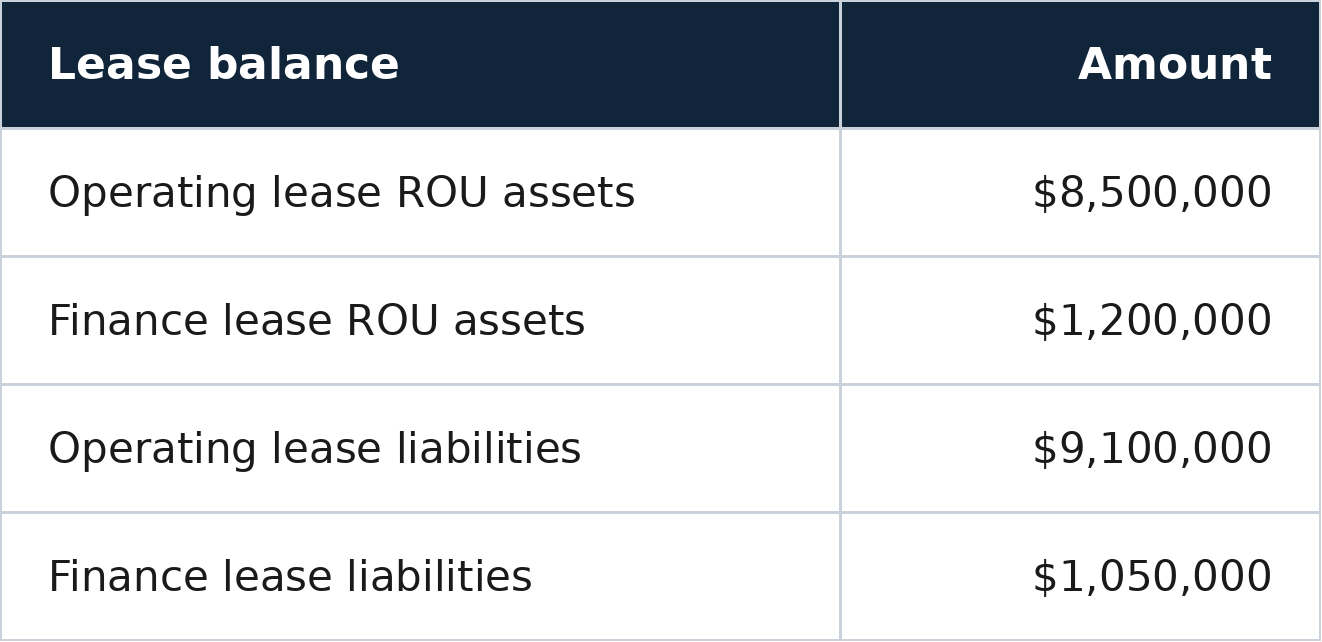
These amounts are illustrative.
The disclosures should agree with the organization's financial statements and supporting lease accounting schedules.
Lease Cost Disclosures
Lessees must disclose relevant components of their lease costs.
These generally include operating lease cost, finance lease amortization, finance lease interest, short-term lease cost, variable lease cost, and sublease income when applicable.
Finance lease costs are separated between ROU asset amortization and interest on lease liabilities.
For example, a company's lease cost disclosure might include:
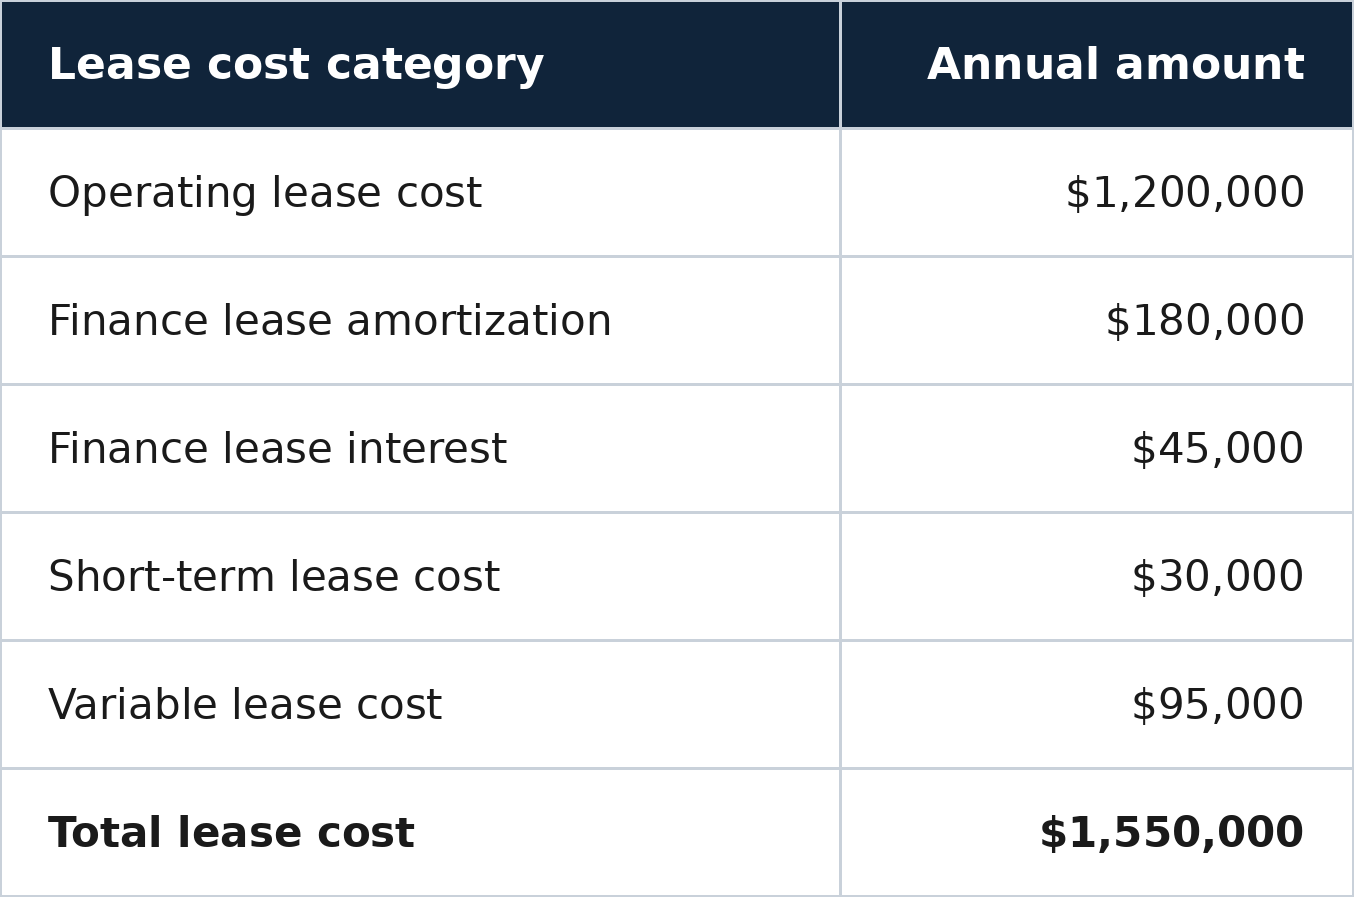
The amounts should be calculated consistently with the relevant accounting guidance.
Sublease income is disclosed separately on a gross basis rather than automatically being deducted from lease expenses.
Companies must also consider applicable sale-leaseback gains or losses and other required information.
Cash Flow and Noncash Disclosures
ASC 842 requires supplemental information about cash paid for amounts included in the measurement of lease liabilities.
The amounts must be appropriately distinguished between operating and finance leases and relevant cash flow classifications.
Companies also disclose supplemental noncash information about lease liabilities arising from obtaining ROU assets.
For example, signing a new property lease may create a substantial ROU asset and lease liability without an equivalent initial cash payment.
Disclosing this activity helps financial statement users understand new obligations that would not otherwise be apparent from the cash flow statement.
ASC 842 Lease Liability Maturity Analysis
The maturity analysis explains when future contractual lease payments are expected to become due.
ASC 842 requires separate maturity analyses for operating and finance lease liabilities.
Each analysis presents undiscounted payments for at least the first five years following the reporting date, plus a combined amount for the remaining years.
The undiscounted total must then be reconciled to the recognized lease liability.
Lease Maturity Schedule Example
Consider a company preparing its year-end disclosures.
Its operating lease payment commitments are:
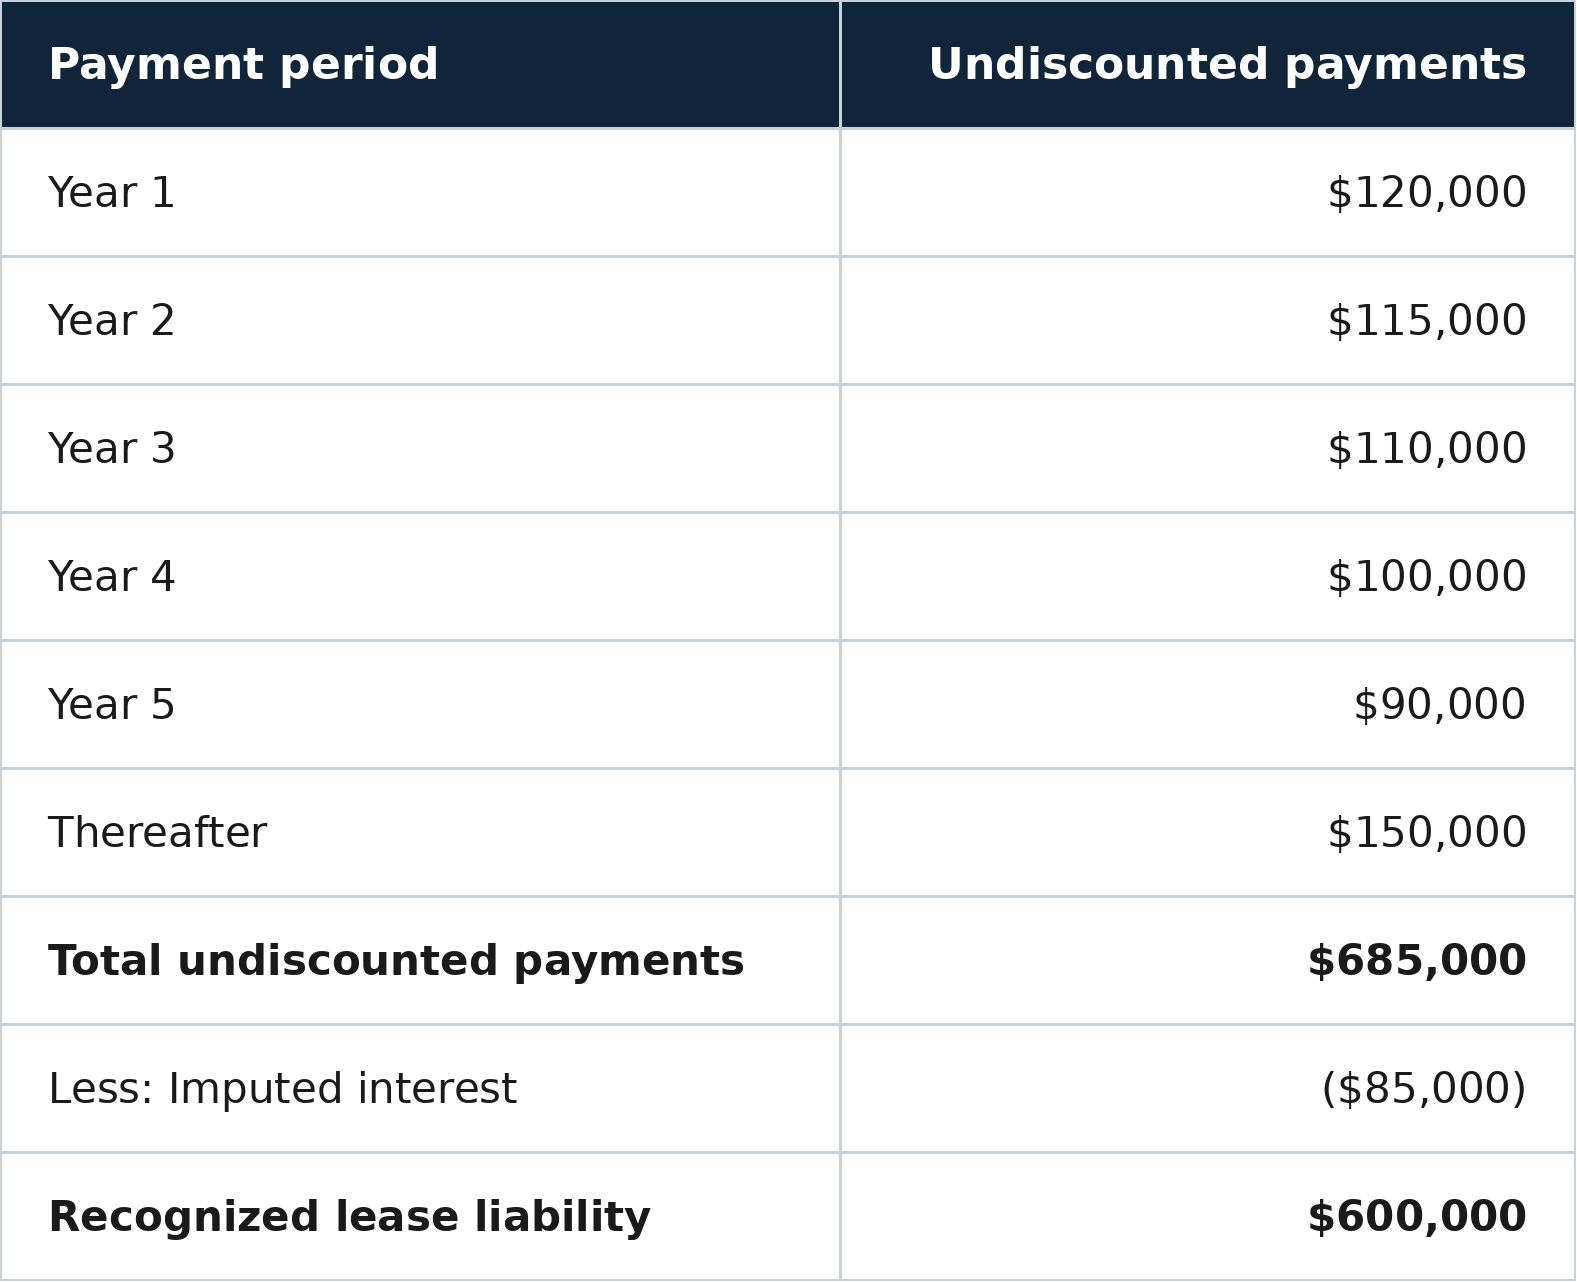
This simplified example illustrates the presentation of an operating lease maturity analysis.
The $85,000 difference represents the aggregate discount effect between undiscounted future payments and their recognized present value.
The actual amount must be derived from the underlying lease schedules.
If the company also has finance leases, it must provide the corresponding finance lease maturity information separately.
This disclosure is important because the balance sheet liability does not equal the total undiscounted cash payments remaining under the lease agreements.
Weighted-Average Lease Term and Discount Rate Disclosures
ASC 842 requires lessees to disclose the weighted-average remaining lease term and weighted-average discount rate separately for operating and finance leases.
These measures help financial statement users understand the duration and measurement assumptions associated with outstanding lease obligations.
The weighted-average remaining lease term reflects the remaining accounting lease terms, weighted using the relevant lease liability balances.
The weighted-average discount rate summarizes the applicable rates across the relevant lease portfolio.
For example, a company's disclosures might report:
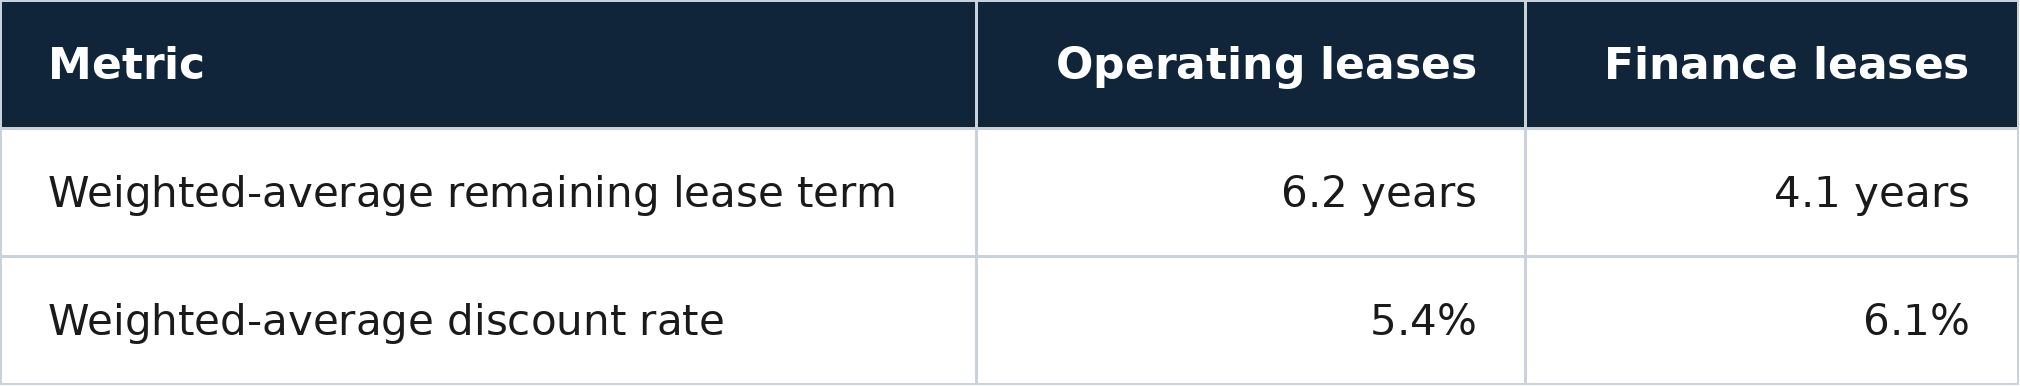
The calculation methods should follow ASC 842's applicable implementation guidance.
Finance teams should not simply calculate an unweighted average of lease terms or discount rates when preparing these disclosures.
Qualitative Disclosure Requirements Under ASC 842
Qualitative disclosures describe the nature of the organization's lease agreements and the significant judgments used in accounting for them.
These explanations provide context for the amounts reported in the financial statements.
Nature and Terms of Lease Arrangements
Organizations must disclose relevant information about their leasing arrangements.
This includes a general description of the leases and important contractual provisions.
For commercial tenants, such information may cover leased property types, variable payment arrangements, renewal options, termination rights, residual value guarantees, and restrictions or covenants.
For example, a retailer might explain that it leases stores under agreements containing fixed annual escalations and renewal options.
Where applicable, the company should distinguish renewal options included in recognized lease balances from options that have not been included.
The objective is to explain significant contractual exposure without reproducing every lease agreement.
Significant Accounting Assumptions and Judgments
Companies must disclose significant judgments made when applying ASC 842.
These may involve determining whether a contract contains a lease, separating lease and non-lease components, and selecting an appropriate discount rate.
Renewal and termination option assessments can also materially affect lease measurement.
For example, a company may determine that it is reasonably certain to exercise a renewal option because significant improvements make relocation economically unattractive.
The resulting lease term may extend beyond the original noncancelable period.
ASC 842 uses five finance lease classification criteria rather than the explicit 75% and 90% bright-line thresholds formerly associated with ASC 840.
Disclosures should accurately describe the relevant judgments and accounting policies.
Significant Leases That Have Not Commenced
Some agreements create important rights and obligations before the lease commencement date.
For example, a retailer may sign a contract for a new store that remains under construction at the reporting date.
If the arrangement is significant, the company must disclose relevant information even though the lease has not yet commenced.
This can include the nature of the agreement and relevant involvement in the construction or design of the underlying asset.
ASC 842 Disclosure Checklist for Finance Teams
A structured checklist helps finance teams confirm that required disclosures are complete and supported by reliable accounting records.
The following ten review points combine mandatory requirements with useful supporting procedures.
1. Verify ROU Asset and Liability Balances
Confirm that operating and finance lease assets and liabilities agree with the general ledger.
Review their balance sheet presentation and identify the relevant line items when amounts are disclosed in the notes.
2. Review All Lease Cost Categories
Check operating lease costs, finance lease amortization and interest, variable lease costs, and applicable short-term lease expenses.
Confirm that relevant sublease income and sale-leaseback gains or losses are also considered.
3. Confirm Weighted-Average Information
Recalculate the weighted-average remaining lease term and discount rate for each classification.
Ensure the calculations use the appropriate weighting methods and agree with the underlying lease portfolio.
4. Validate Maturity Schedules
Prepare separate operating and finance lease maturity analyses.
Verify the first five annual payment amounts, remaining payments, and reconciliation from undiscounted payments to recognized liabilities.
5. Review Cash Flow Information
Confirm cash paid for amounts included in lease liability measurements.
Review the classification of operating and finance lease cash flows and the required supplemental noncash information.
6. Document Significant Judgments
Review lease identification, accounting lease terms, discount rates, and lease component elections.
Ensure significant accounting policies and judgments are appropriately explained.
7. Evaluate Modifications and Impairments
Determine whether material lease modifications, remeasurements, impairments, or incentives require additional explanation.
Retain supporting documentation for significant transactions.
8. Assess Subleases and Sale-Leasebacks
Identify relevant subleasing activities and sale-leaseback transactions.
Confirm that required income, gains or losses, and material contractual information are included.
9. Reconcile Supporting Reports
Compare the financial disclosures with the general ledger, lease accounting schedules, and other supporting records.
A lease roll forward report can help explain changes arising from new leases, payments, modifications, and terminations.
Although useful for reconciliation, ASC 842 does not universally require a standalone roll forward report in one prescribed format.
10. Complete the Final Reporting Review
Confirm that disclosures are accurate, internally consistent, and appropriate for the reporting period.
Review significant changes, investigate unexplained differences, and obtain the necessary accounting approvals before the financial statements are finalized.
Common ASC 842 Disclosure Mistakes
Many disclosure errors arise from incomplete lease information rather than a misunderstanding of the reporting requirements themselves.
One common mistake is omitting the operating lease maturity analysis or providing the schedule without reconciling undiscounted payments to the recognized liability.
Another is combining operating and finance lease information when the standard requires separate reporting.
Organizations may also overlook new leases that create material noncash obligations, especially when the agreements are maintained outside the accounting department.
Other issues include incorrectly calculated weighted averages, outdated renewal assumptions, incomplete variable lease cost information, and missing documentation for significant modifications.
Businesses should pay particular attention to changes occurring near the reporting date.
For example, a lease amendment executed during the final month of the year may affect the accounting balances and related disclosures.
A consistent lease accounting audit checklist can help finance teams review supporting documents, calculations, and reporting controls before an external audit.
How to Improve the Lease Disclosure Reporting Process
Accurate ASC 842 disclosures depend on maintaining reliable lease information throughout the reporting period.
When real estate teams negotiate agreements and finance teams prepare financial statements, incomplete communication can create reporting discrepancies.
For example, a property manager may approve an extension that changes the accounting lease term, but the finance team may not receive the executed amendment before preparing the year-end disclosures.
Establishing a defined process for communicating new leases, modifications, and terminations helps address this risk.
Finance teams should also use consistent reporting templates and regularly reconcile lease records with the general ledger.
Rather than assembling all supporting documentation during year-end close, organizations can review lease movements throughout the year.
For companies with numerous locations, lease accounting software can help maintain accounting schedules, organize lease information, and support financial reporting.
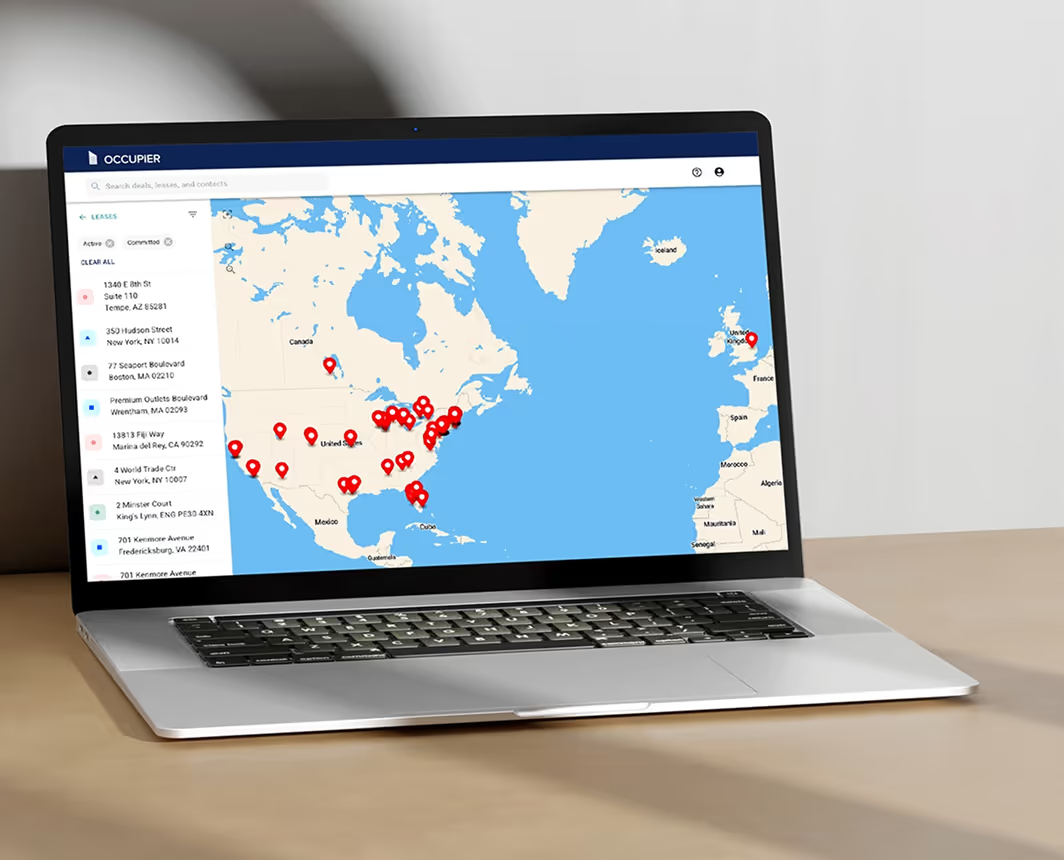
Occupier connects commercial lease records with accounting workflows, helping real estate and finance teams work from more consistent information.
Frequently Asked Questions About ASC 842 Disclosures
What disclosures are required under ASC 842?
ASC 842 requires qualitative and quantitative information about leases, including relevant assets and liabilities, lease costs, future payment commitments, cash flow information, weighted-average metrics, and significant accounting judgments.
Are operating leases included in ASC 842 disclosures?
Yes. Operating leases are subject to ASC 842 disclosure requirements. Certain information, including maturity analyses and weighted-average metrics, must be presented separately from finance leases.
Does ASC 842 require a lease liability maturity schedule?
Yes. Lessees must disclose separate maturity analyses for operating and finance lease liabilities, including at least five years of annual undiscounted payments, a remaining-years total, and reconciliations to recognized liabilities.
Are lease roll forward reports mandatory?
ASC 842 does not universally require a standalone roll forward report in a prescribed format. However, roll forwards can support reconciliations, disclosure preparation, and audit reviews.
What is the difference between quantitative and qualitative disclosures?
Quantitative disclosures report financial amounts such as lease costs and liabilities. Qualitative disclosures explain lease terms, significant contractual provisions, and accounting judgments affecting those amounts.
How often should ASC 842 disclosures be updated?
Disclosures should be prepared and reviewed as required for the organization's applicable financial reporting periods. Material changes in lease activity should be evaluated when preparing the relevant financial statements.

Lease management that works for real estate and finance
15,000 sq ft
90 days notice
March 2026
Action required