Roll Forward Report: How It Works, Examples & Reconciliation

What is the purpose of a roll forward report?
A roll forward report explains how an account balance changes between two dates. It identifies additions, reductions, and adjustments so finance teams can verify closing balances and understand the transactions affecting an account.
A roll forward report is an accounting reconciliation that explains how an account balance changes between two reporting dates. It starts with the opening balance, identifies transactions that increased or decreased the account, and calculates the closing balance.
In lease accounting, roll forward reports track movements in right-of-use (ROU) assets and lease liabilities. They help finance teams understand the financial effects of new leases, payments, modifications, terminations, and other changes during a reporting period.
For businesses managing multiple commercial locations, these reports are useful when reconciling financial records, investigating unexpected balance movements, and responding to auditor requests. A well-prepared roll forward shows not only how much an account changed but also which transactions caused that change.
What Is a Roll Forward Report?
A roll forward report summarizes changes in an account balance over a specific accounting period.
Rather than presenting only the opening and closing amounts, it organizes the transactions responsible for the difference into identifiable categories.
The basic calculation is:
Ending Balance = Beginning Balance + Additions − Reductions ± Adjustments
For example, a company might begin the year with $400,000 in lease liabilities and end with $455,000.
The $55,000 increase alone does not explain what happened. The company may have signed additional leases, made scheduled payments, recognized interest, or modified existing agreements.
A roll forward report separates these movements so finance teams can understand and verify the ending balance.
Roll forwards are used across several accounting areas, including fixed assets, debt, investments, and reserves. For commercial lease portfolios, they are particularly useful because assets and liabilities can change every reporting period.
A roll forward is also distinct from a general ledger or trial balance. Those records show account activity and balances, while a roll forward organizes the movements into categories that explain the change between reporting dates.
What Does a Lease Accounting Roll Forward Show?
A lease accounting roll forward generally reports changes in ROU assets and lease liabilities over a defined period.
Although the two balances are related, they should be reconciled separately because different transactions affect them in different ways.
For example, a scheduled lease payment generally reduces the lease liability, while ROU asset amortization or reduction affects the carrying amount of the asset.
An impairment may reduce the ROU asset without changing the related lease liability.
The report therefore needs to distinguish the movements affecting each account.
Right-of-Use Asset Movements
The ROU asset portion of the report explains changes in the recorded right to use leased properties or equipment.
Common movements include additions from newly commenced leases, periodic asset reductions, lease modifications, impairments, and terminations.
Consider a retailer opening five new stores during the year while closing two existing locations.
The new agreements may create additional ROU assets, while terminations remove or adjust the carrying amounts associated with the closed locations.
The roll forward records these movements and shows their combined impact on the portfolio's ending asset balance.
Lease Liability Movements
The lease liability portion explains how the obligation associated with qualifying future lease payments changes.
Interest accretion increases the liability, while lease payments reduce it.
New leases and qualifying modifications may increase the balance, while terminations or reductions in payment obligations may decrease it.
The report allows accountants to distinguish between normal scheduled movements and significant changes caused by business decisions.
This distinction becomes particularly important when several locations have different payment schedules, discount rates, or modification dates.
Which Transactions Should Appear in a Lease Roll Forward?
An effective lease roll forward uses consistent categories to classify transactions.
These categories help reviewers understand whether an account movement resulted from routine accounting activity or a change to the lease portfolio.
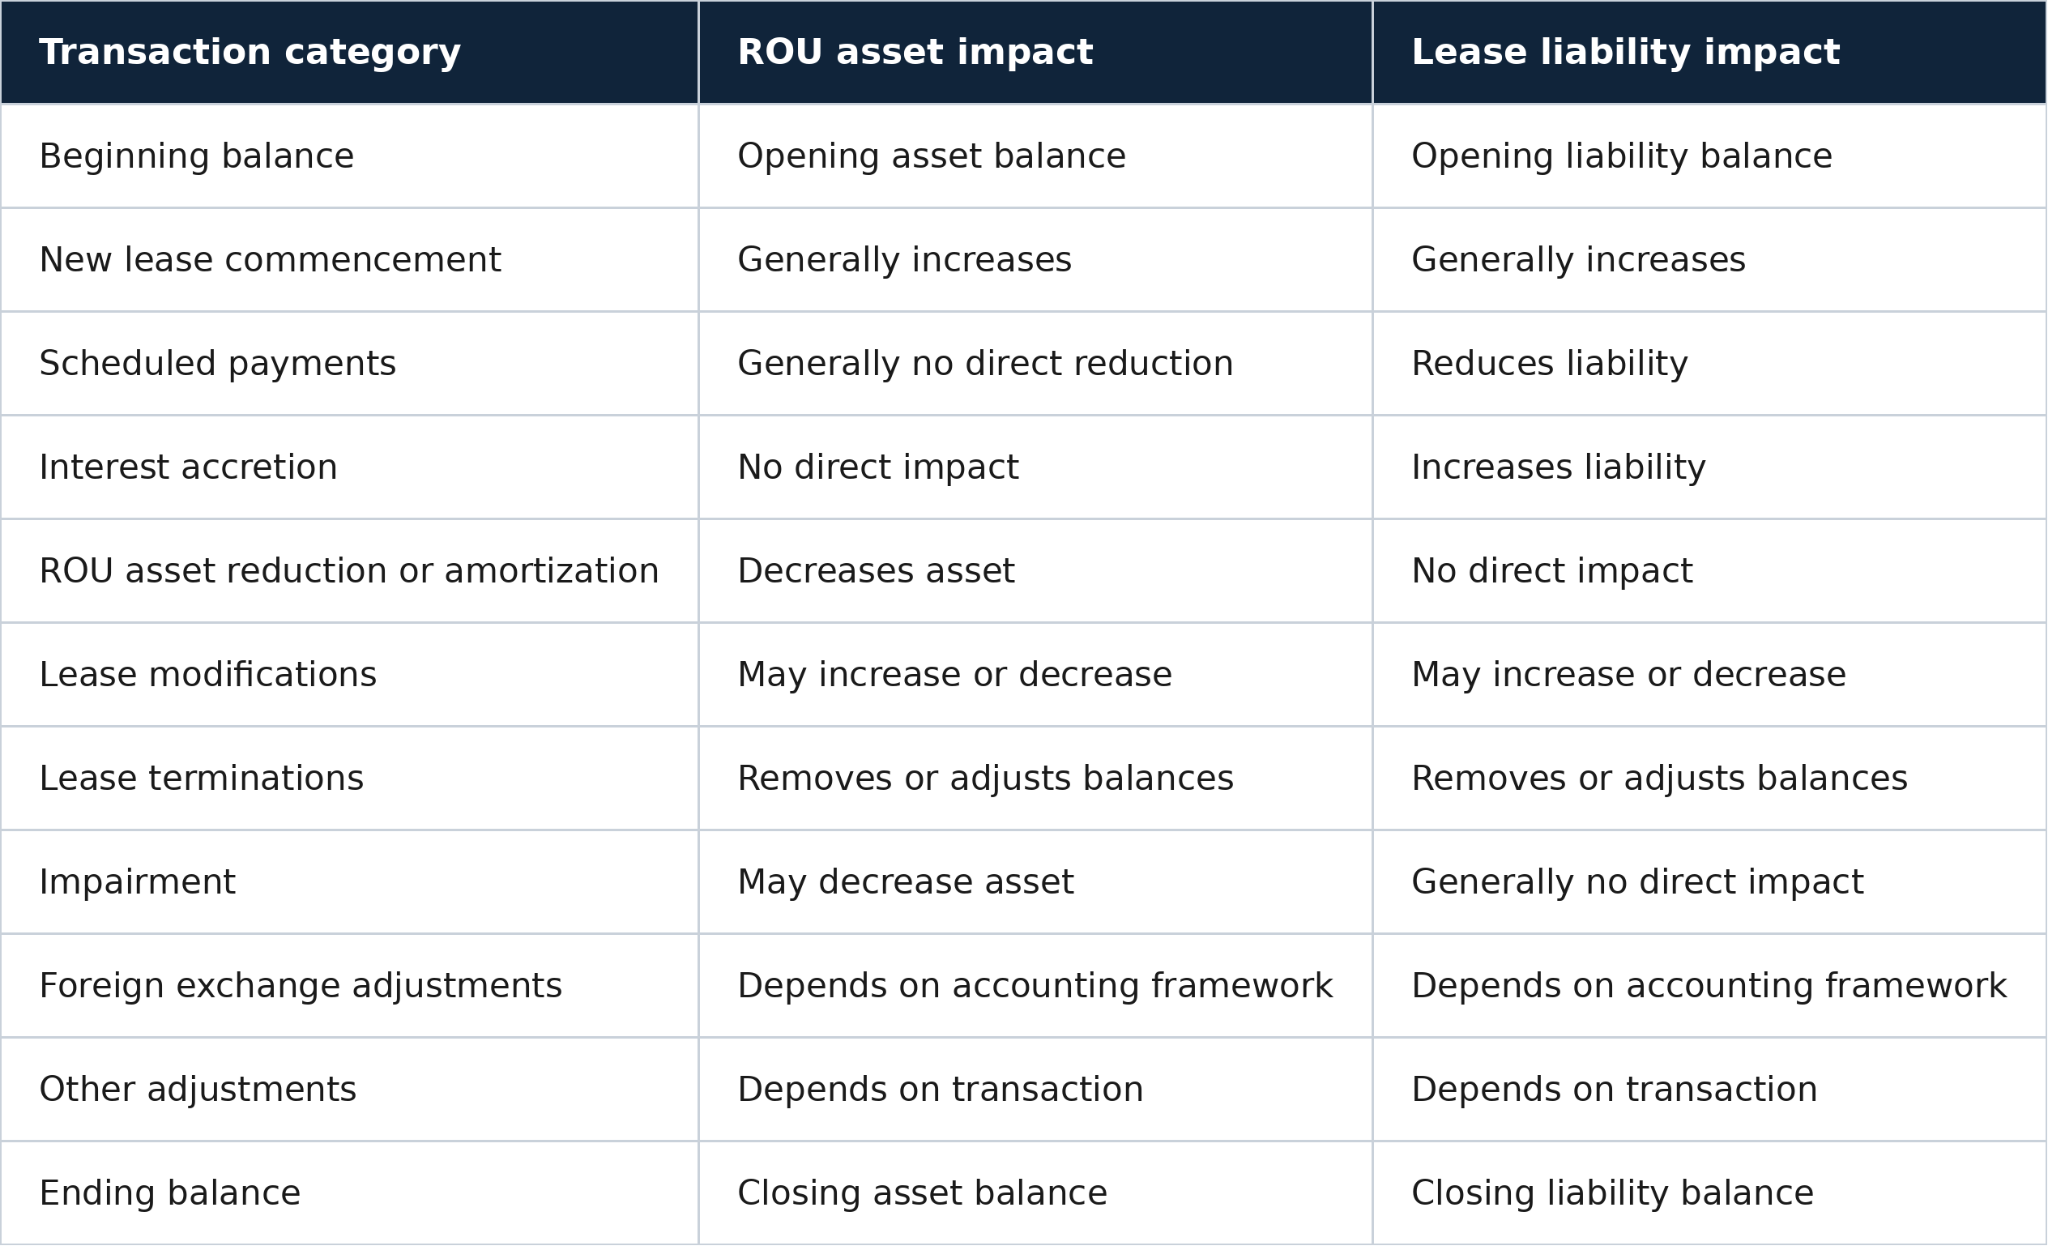
Not every transaction affects both balances.
For example, an impairment charge generally affects the carrying amount of the ROU asset, but it does not automatically eliminate the contractual obligation to make lease payments.
Similarly, interest accretion increases the lease liability without directly increasing the ROU asset.
The precise accounting depends on the applicable reporting standard, lease classification, and transaction details.
Using clearly defined categories helps prevent unrelated movements from being grouped together under a generic adjustment line.
Lease Liability Roll Forward Report Example
Consider a hypothetical company preparing an annual lease liability reconciliation.
At the beginning of the year, its commercial lease portfolio has a total lease liability of $400,000.
During the reporting period, the company signs new leases, makes scheduled payments, recognizes interest, and modifies an existing agreement.
The resulting report could look like this:
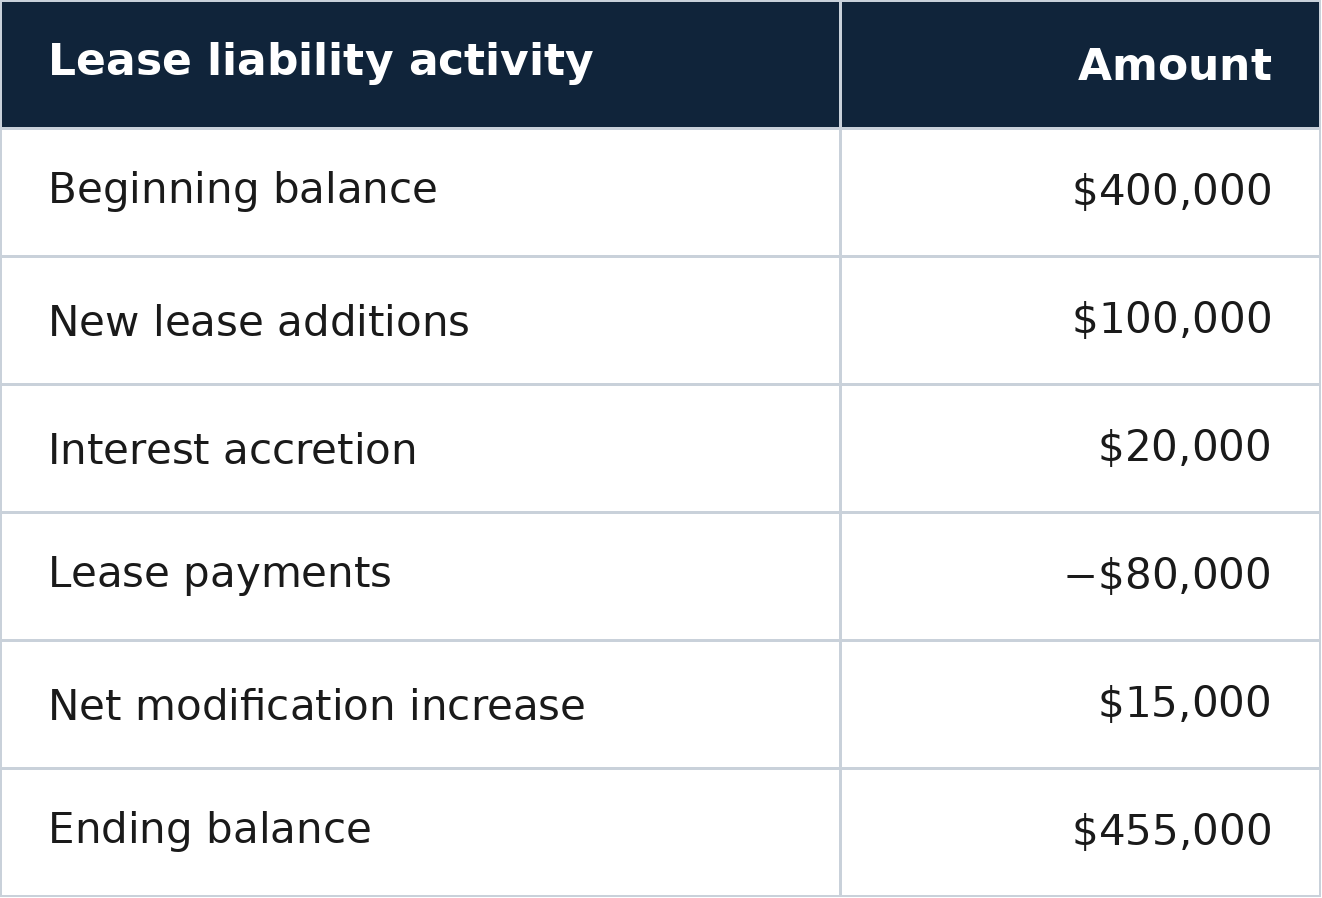
The reconciliation is:
$400,000 + $100,000 + $20,000 − $80,000 + $15,000 = $455,000
The lease liability increased by $55,000 during the year.
However, that increase does not mean the company failed to make payments. It paid $80,000 while adding new obligations and recognizing other increases.
Without a roll forward, the ending balance would provide limited insight into those changes.
The report helps accountants identify which transactions require further investigation and whether they agree with the underlying lease accounting records.
How to Interpret the Results
The largest increase in this example comes from $100,000 in newly commenced leases.
This may reflect business expansion, a new location, or additional equipment agreements.
The $15,000 modification increase represents a net change associated with an existing agreement. The supporting records should identify the specific lease and explain how the revised terms affected the liability.
The $20,000 interest amount represents the combined accretion recognized across the relevant leases.
Each category should reconcile to supporting accounting schedules and recorded journal entries.
ROU Asset Roll Forward Report Example
The same company also prepares a separate reconciliation for its ROU assets.
Assume the opening ROU asset balance is $390,000.
During the year, the company records new lease additions, periodic asset reductions, a net increase from a modification, and an impairment charge.
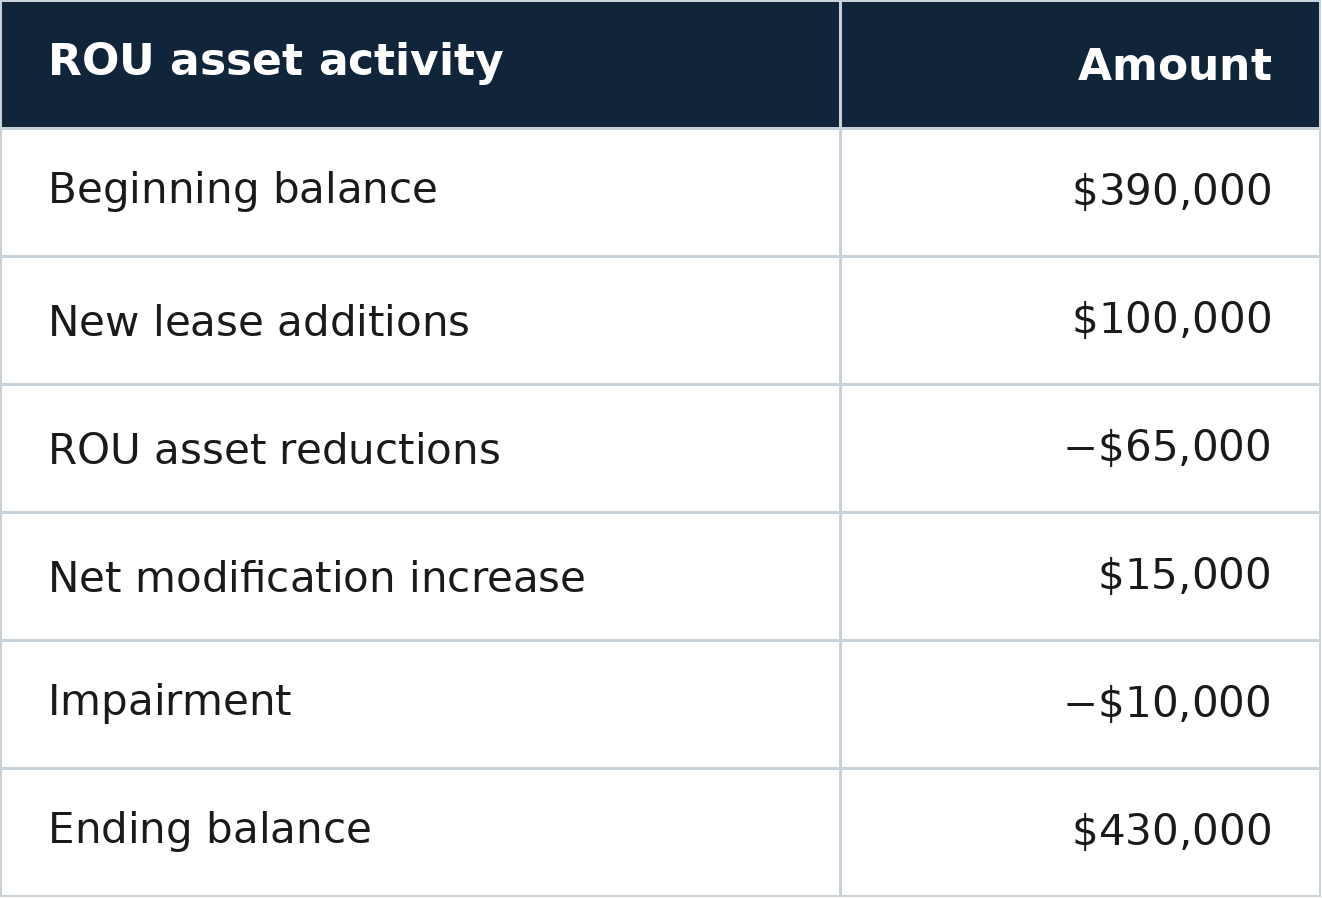
The reconciliation is:
$390,000 + $100,000 − $65,000 + $15,000 − $10,000 = $430,000
The ending ROU asset balance is $430,000, compared with the lease liability balance of $455,000 in the previous example.
These balances are not required to remain equal throughout the lease term.
The difference may result from the applicable accounting treatment, asset reductions, interest accretion, impairments, incentives, and other adjustments.
The examples are simplified portfolio-level illustrations. Actual asset and liability movements should reflect the company's individual lease schedules and applicable accounting requirements.
How to Prepare a Lease Roll Forward Report
Preparing a roll forward requires more than subtracting the prior period's balance from the current balance.
The finance team must identify the transactions responsible for the movement, classify them correctly, and reconcile the result to the accounting records.
Establish the Reporting Period and Opening Balances
Start by defining the reporting period, such as a month, quarter, or financial year.
The opening balance should agree with the prior period's closing balance, unless a documented correction or other appropriate adjustment explains a difference.
For example, a roll forward covering January through March should generally begin with the closing account balances from December 31.
If the opening amount differs from the previous report, investigate that discrepancy before proceeding.
Otherwise, even correctly classified current-period transactions may produce an inaccurate ending reconciliation.
Gather the Period's Lease Transactions
Next, collect the relevant movements from lease accounting schedules and the general ledger.
These may include payments, newly commenced leases, interest accretion, ROU asset reductions, modifications, remeasurements, terminations, and impairments.
Finance teams should also confirm whether relevant changes originated in the real estate department.
For example, a lease amendment signed during the quarter may need to be reflected in the accounting records even when the revised rental payments have not yet started.
The transaction data should cover the entire reporting period and include the leases within the report's scope.
Group Movements Into Consistent Categories
Once the transactions are collected, classify them according to their accounting effect.
Interest should not be combined with new lease additions, and scheduled payments should remain distinguishable from adjustments caused by terminations.
Consistent classifications make the report easier to compare across periods.
For instance, if modifications caused a significant liability increase in one quarter, management should be able to compare that activity with previous quarters without reviewing every individual journal entry.
Avoid using an undefined "other" category for large or unusual movements. Significant adjustments should be described clearly and supported by documentation.
Calculate the Ending Balances
After classifying the activity, total the movements and calculate the closing balance.
The resulting amount should reconcile to the relevant general ledger account and supporting schedules.
If the ending balance does not agree, the difference needs to be investigated.
Common causes include missing journal entries, incorrect reporting dates, duplicate transactions, and classification errors.
The completed report should make it possible to trace each material movement to its supporting records.
How to Reconcile a Roll Forward to the General Ledger
A roll forward is most useful when its ending balance agrees with the organization's accounting records.
Suppose the report calculates a closing lease liability of $455,000, but the general ledger reports $462,000.
The $7,000 difference should not simply be added to an adjustment category without investigation.
The accounting team needs to determine whether the discrepancy results from an omitted transaction, an incorrect journal entry, a timing difference, or another issue.
Begin by comparing the opening balances. If those agree, review current-period transaction totals and posting dates.
For example, a payment recorded in the general ledger on the final day of the month might appear in the lease schedule during the following period.
Differences can also arise when a modification is recorded in one system but has not been reflected in another.
A documented reconciliation should identify the cause, determine the appropriate correction, and record who reviewed the resolution.
For organizations completing monthly reconciliations, Occupier's lease accounting month-end checklist provides a broader framework for reviewing accounting schedules and reporting balances.
What Can Unexpected Roll Forward Movements Reveal?
Roll forward reports are particularly valuable when an account changes more than expected.
A sudden increase or decrease may reflect legitimate business activity, but it may also indicate incomplete information or incorrect accounting.
Unexpected Increase in Lease Liabilities
Suppose a company makes its scheduled rental payments but reports a substantial increase in lease liabilities.
The roll forward may show that newly commenced leases and modifications more than offset those payments.
If no such business activity occurred, the finance team should investigate whether an agreement was duplicated, an adjustment was recorded incorrectly, or an unexpected remeasurement was applied.
Unexplained ROU Asset Reductions
A significant decrease in ROU assets may result from normal amortization, lease terminations, impairment, or other adjustments.
However, the report should identify which category caused the change.
A large asset reduction classified as an ordinary monthly adjustment may require further investigation, especially if it does not agree with supporting schedules.
Large Modification Balances
Lease modifications may substantially change recognized assets and liabilities.
For example, a retailer extending several store leases may record increases in its lease liabilities during the quarter.
The roll forward identifies the total accounting impact, while the supporting records explain which agreements changed and why.
Maintaining a clear lease audit trail helps teams connect these movements to the relevant amendments and accounting decisions.
Why Do Auditors Request Roll Forward Reports?
Auditors use roll forward reports to understand how account balances changed during a reporting period and to identify transactions for further examination.
A report that separates new leases, payments, modifications, terminations, and other activity helps auditors assess the population of transactions and determine where additional testing may be appropriate.
For example, auditors may select significant lease additions and compare their accounting entries with executed agreements and related calculations.
They may also investigate unusual modifications or verify that recorded balances agree with the general ledger.
A roll forward supports these procedures, but it does not independently prove that every lease has been identified or that all transactions are accurate.
Auditors still require appropriate evidence and may perform additional procedures.
Finance teams preparing for year-end reporting can use Occupier's lease accounting audit checklist to understand the wider documentation and review requirements.
Portfolio-Level vs. Individual Lease Roll Forwards
A portfolio-level roll forward summarizes changes across all leases included in the report.
This provides a useful view of how the organization's overall lease assets and liabilities changed during the period.
For example, a company managing 75 retail locations may use a portfolio-level report to identify total additions, payments, and modifications for the quarter.
However, the consolidated figures do not necessarily explain which specific lease caused an unusual movement.
An individual lease roll forward provides that additional detail.
If the portfolio report includes a $250,000 modification adjustment, finance teams should be able to identify the affected agreements and trace the corresponding entries.
Both reporting levels serve important purposes.
The portfolio view supports financial reporting and trend analysis, while the individual lease view helps investigate specific transactions and provide supporting evidence.
For organizations with multiple legal entities, reports may also need to be filtered or grouped according to the relevant reporting structure.
How to Improve the Accuracy of Roll Forward Reporting
Reliable reporting depends on consistent accounting information and clear responsibilities between departments.
A practical approach is to establish standard transaction categories and apply them consistently in every reporting period.
Finance teams should also ensure that the opening balance of each new report agrees with the previously approved closing balance.
Significant adjustments should include explanations and references to supporting documentation.
Another important consideration is the timing of lease changes.
Real estate teams may negotiate amendments, renewals, or terminations before the finance department becomes aware of them.
A defined process for communicating executed agreements helps accountants recognize changes in the correct reporting period.
Regular reviews can also reduce the amount of investigation required at year-end.
Rather than reconstructing twelve months of lease activity during an audit, organizations can maintain reconciled reports throughout the year.
For businesses with large portfolios, lease accounting software can help generate roll forwards, maintain supporting calculations, and organize reporting information.
Occupier provides lease-level and portfolio-level reporting capabilities, helping finance teams review account movements and access related lease information.
Frequently Asked Questions About Roll Forward Reports
What is the purpose of a roll forward report?
A roll forward report explains how an account balance changes between two dates. It identifies additions, reductions, and adjustments so finance teams can verify closing balances and understand the transactions affecting an account.
What is a lease liability roll forward?
A lease liability roll forward reconciles opening and closing lease liability balances. It tracks changes caused by payments, interest accretion, new leases, modifications, terminations, and other applicable adjustments.
What is an ROU asset roll forward?
An ROU asset roll forward explains changes in the carrying amount of right-of-use assets. It may include new lease additions, periodic asset reductions, modifications, impairments, and terminations.
How often should roll forward reports be prepared?
Reporting frequency depends on the organization's financial reporting schedule and internal controls. Many finance teams prepare roll forwards monthly or quarterly, with additional reconciliations supporting annual financial statements.
What is the difference between a roll forward and an amortization schedule?
An amortization schedule calculates how balances change according to payment schedules and accounting assumptions for a lease. A roll forward summarizes actual account movements over a reporting period, often across several leases, and reconciles opening and closing balances.
Is a roll forward report required under ASC 842?
ASC 842 establishes lease recognition, measurement, presentation, and disclosure requirements. A roll forward reconciliation is a useful supporting accounting report and a common audit request, but the standard does not universally require every lessee to publish a standalone roll forward report in one prescribed format.
What should you do if a roll forward does not reconcile?
Compare the opening balances, transaction categories, journal entries, and reporting dates. Investigate missing or duplicated entries, timing differences, and other adjustments before finalizing the report.
Lease management that works for real estate and finance
15,000 sq ft
90 days notice
March 2026
Action required