Finance Lease Accounting: ASC 842 Guide & Example
What is finance lease accounting?
Finance lease accounting involves recognizing an ROU asset and lease liability, recording interest expense on the liability, and amortizing the ROU asset according to ASC 842. It applies when a lease meets at least one finance lease classification criterion.
Finance lease accounting is the process of recognizing and reporting lease arrangements that meet specific classification criteria under ASC 842. A finance lease requires the lessee to record a right-of-use (ROU) asset and lease liability on the balance sheet, recognize interest expense on the liability, and separately amortize the ROU asset.
Previously called capital leases under ASC 840, finance leases are common in arrangements involving equipment, machinery, vehicles, and other long-term assets. Although both operating and finance leases generally appear on the balance sheet under ASC 842, their expense recognition and cash flow treatment differ.
Understanding how to classify, calculate, and account for finance leases helps businesses maintain accurate financial statements and avoid errors during financial reporting and audits.
What Is a Finance Lease Under ASC 842?
A finance lease is a lease arrangement that meets at least one of the five classification criteria established under ASC 842. These criteria indicate that the lessee obtains substantially all of the economic benefits associated with ownership of the underlying asset.
The lessee receives the right to use the asset for an agreed period in exchange for payments to the lessor. Depending on the agreement, the lessee may also receive ownership of the asset or have an option to purchase it.
However, transferring legal ownership is not required for a lease to qualify as a finance lease. A contract can meet the classification requirements based on its duration, payment value, or specialized nature.
For example, a manufacturing company might lease machinery for most of its remaining economic life. Even if the company never takes legal ownership, the arrangement may qualify as a finance lease because of the substantial portion of the asset's economic life covered by the agreement.
Under ASC 842, the lessee recognizes an ROU asset and lease liability when the lease commences, provided the lease is within the recognition requirements of the standard.
What Are the Five Finance Lease Classification Criteria?
ASC 842 establishes five criteria for determining whether a lease should be classified as a finance lease.
A lease is generally classified as a finance lease if it meets any one of the following conditions:
- Transfer of ownership: Ownership of the underlying asset transfers to the lessee by the end of the lease term.
- Purchase option: The agreement gives the lessee an option to purchase the asset that the lessee is reasonably certain to exercise.
- Lease term: The lease covers a major part of the asset's remaining economic life.
- Present value: The present value of lease payments, together with any applicable residual value guarantee not already included in those payments, represents substantially all of the asset's fair value.
- Specialized nature: The asset is sufficiently specialized that the lessor is expected to have no alternative use for it when the lease ends.
ASC 842 does not prescribe universal numerical thresholds for the third and fourth criteria. However, its implementation guidance indicates that 75% of the asset's remaining economic life and 90% of its fair value are reasonable approaches to interpreting "major part" and "substantially all."
The remaining economic life criterion also has specific considerations when a lease begins at or near the end of the underlying asset's economic life.
Businesses should evaluate all five criteria using the contract terms and the facts available at the relevant classification date.
For a broader explanation of the standard, read Occupier's ASC 842 guide.
Finance Lease vs. Operating Lease Accounting
ASC 842 requires lessees to classify leases as either finance leases or operating leases.
Both classifications generally involve recognizing an ROU asset and lease liability, but their subsequent accounting treatment differs.
A finance lease recognizes interest expense on the lease liability and amortization expense on the ROU asset separately. An operating lease generally produces a single lease cost recognized on a straight-line basis.
This distinction affects the timing of expenses and how lease-related amounts appear in the financial statements.
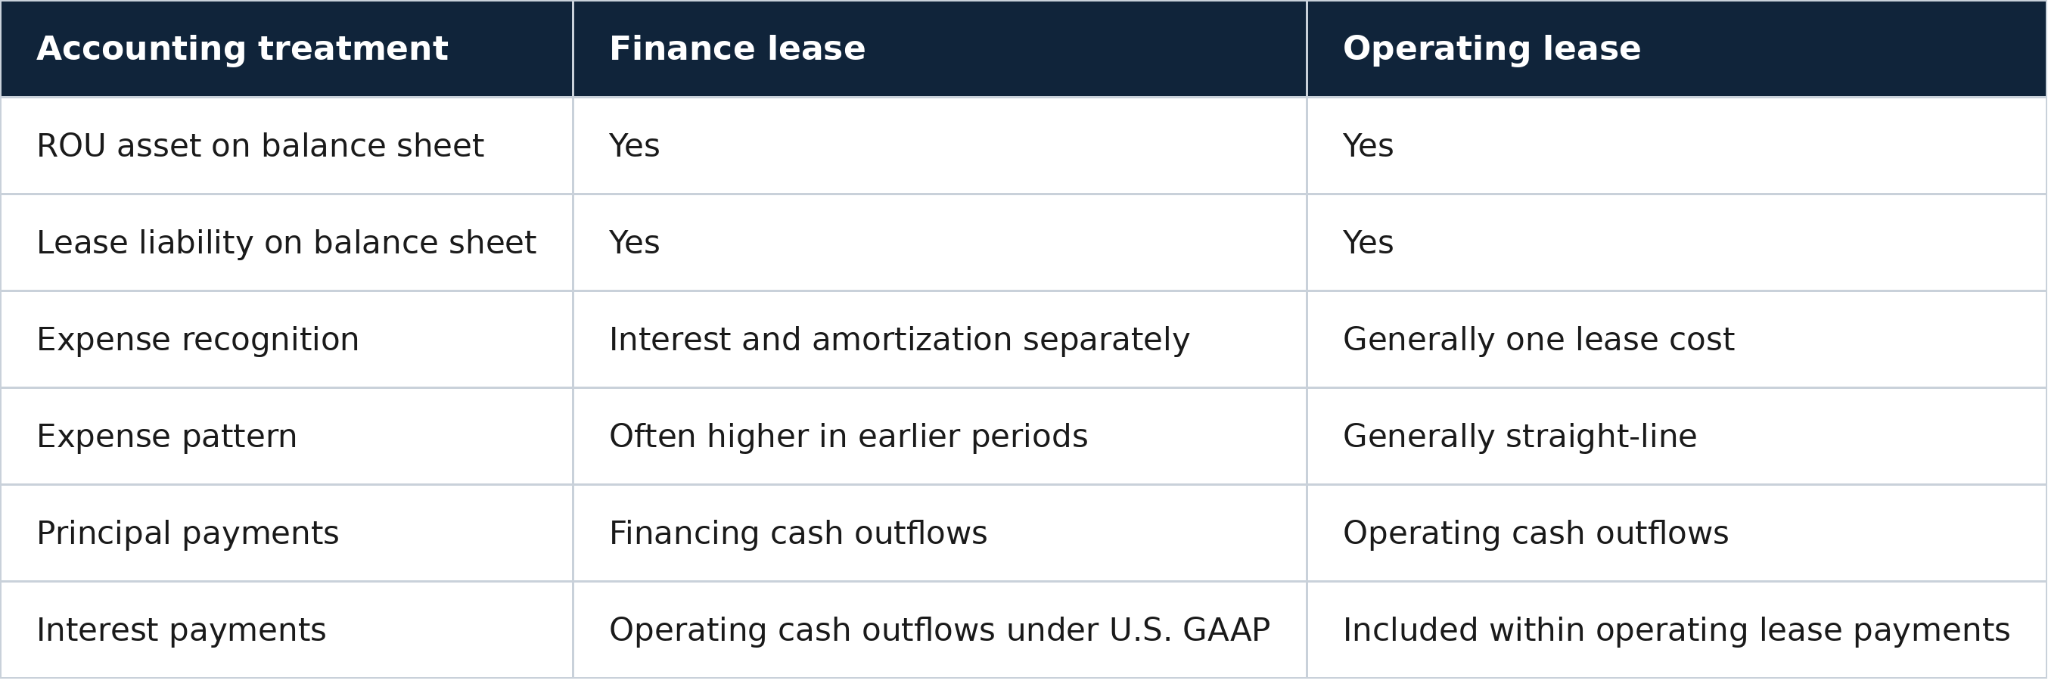
For example, a five-year equipment lease classified as a finance lease may produce higher total recognized expenses early in its term because interest is calculated on a larger outstanding liability.
An otherwise comparable operating lease would generally recognize a more consistent total lease cost across the term.
These differences are important when evaluating financial performance, budgeting, and accounting requirements.
How Does Finance Lease Accounting Work?
Finance lease accounting begins when the lessee recognizes its right to use the underlying asset and the obligation to make qualifying future payments.
The accounting process generally involves initial measurement, periodic interest calculations, liability reductions, and ROU asset amortization.
Step 1: Calculate the Initial Lease Liability
The initial lease liability is measured at the present value of qualifying lease payments that have not been paid at the commencement date.
The calculation uses the interest rate implicit in the lease when that rate is readily determinable. Otherwise, the lessee generally uses its incremental borrowing rate, subject to any applicable accounting policy election.
Qualifying payments may include fixed payments, certain variable payments based on an index or rate, and other amounts specified by ASC 842.
The payment schedule, discount rate, lease term, and payment timing all affect the initial liability.
Step 2: Recognize the Right-of-Use Asset
The finance lease ROU asset initially reflects the lease liability, adjusted for qualifying payments made at or before commencement, lease incentives, and initial direct costs.
For a straightforward agreement with no prepaid rent, lease incentives, or initial direct costs, the initial ROU asset may equal the lease liability.
The ROU asset represents the right to use the equipment or property rather than ownership of the underlying asset.
Step 3: Record Interest and Lease Payments
After commencement, interest accretion increases the lease liability, while qualifying payments reduce it.
Finance teams calculate the interest expense based on the applicable periodic discount rate and outstanding liability balance.
The timing of payments matters. Payments made at the beginning of a period reduce the liability before interest accrues for that period, while payments at the end of a period generally follow the interest calculation.
Step 4: Amortize the ROU Asset
Finance lease ROU assets are generally amortized on a systematic basis over the appropriate period.
When ownership does not transfer and the lessee is not reasonably certain to exercise a purchase option, the asset is generally amortized over the shorter of the lease term and the asset's useful life.
If ownership transfers or the purchase option is reasonably certain to be exercised, the useful life may be the appropriate amortization period.
Finance Lease Accounting Example Under ASC 842
Consider a company that enters into a finance lease for manufacturing equipment.
Assume the lease qualifies as a finance lease because its five-year term covers a major part of the equipment's six-year remaining economic life.
The agreement has the following terms:
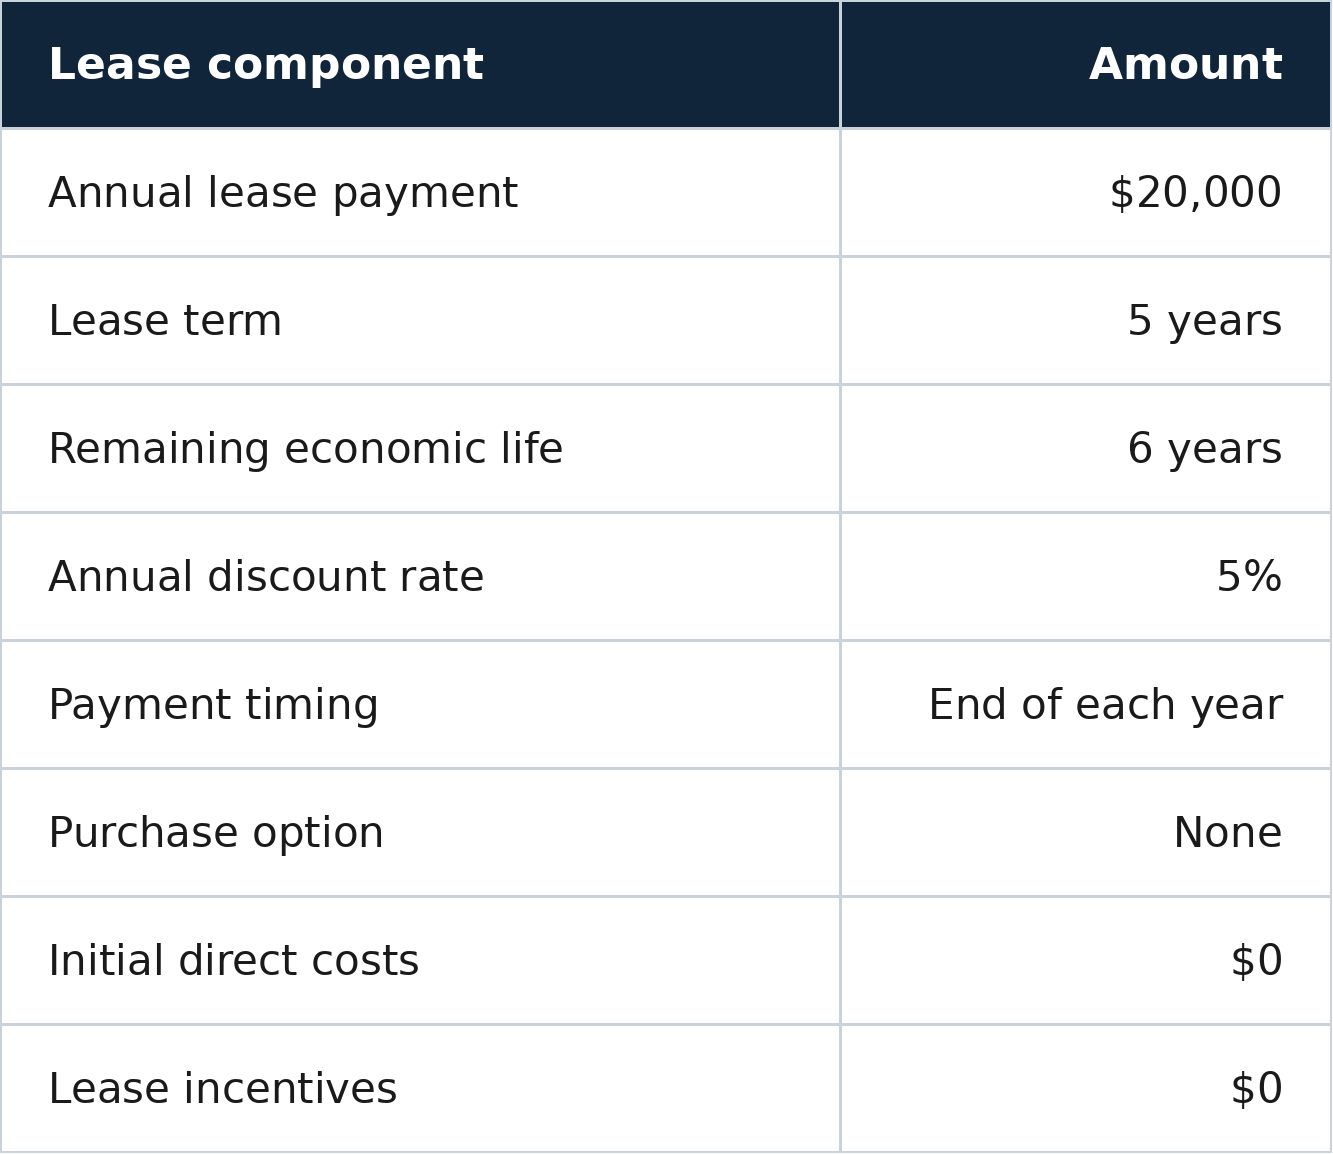
For simplicity, assume there are no residual value guarantees, prepaid amounts, impairment charges, or modifications.
Calculate the Initial Lease Liability
The company first calculates the present value of five annual payments of $20,000 using a 5% annual discount rate.
For equal payments made at the end of each period, the formula is:
Present Value = Payment × [1 − (1 + r)^−n] ÷ r
Where:
- Payment = $20,000
- r = 0.05
- n = 5
The calculation becomes:
$20,000 × [1 − (1.05)^−5] ÷ 0.05
The initial lease liability is approximately $86,590.
Because the agreement has no initial direct costs, incentives, or prepaid amounts, the initial ROU asset is also approximately $86,590.
Calculate the First Year's Interest Expense
Interest expense is calculated using the beginning liability balance and the discount rate.
$86,590 × 5% = approximately $4,329
Since the company makes its $20,000 payment at the end of the year, the liability reduction is:
$20,000 − $4,329 = approximately $15,671
The remaining liability is:
$86,590 − $15,671 = approximately $70,919.
Calculate Annual ROU Asset Amortization
In this example, ownership does not transfer and no purchase option is reasonably certain to be exercised.
The ROU asset is amortized over the five-year lease term, assuming straight-line amortization appropriately reflects the pattern of consumption.
$86,590 ÷ 5 = approximately $17,318 annually
The first year's total recognized finance lease expense is therefore approximately:
$4,329 interest + $17,318 amortization = $21,647
The exact amounts may differ slightly because of rounding.
Finance Lease Journal Entries Under ASC 842
Finance lease journal entries record the initial asset and liability, periodic interest expense, lease payments, and ROU asset amortization.
Using the example above, the company would record the following transactions.
Initial Recognition
At the lease commencement date:
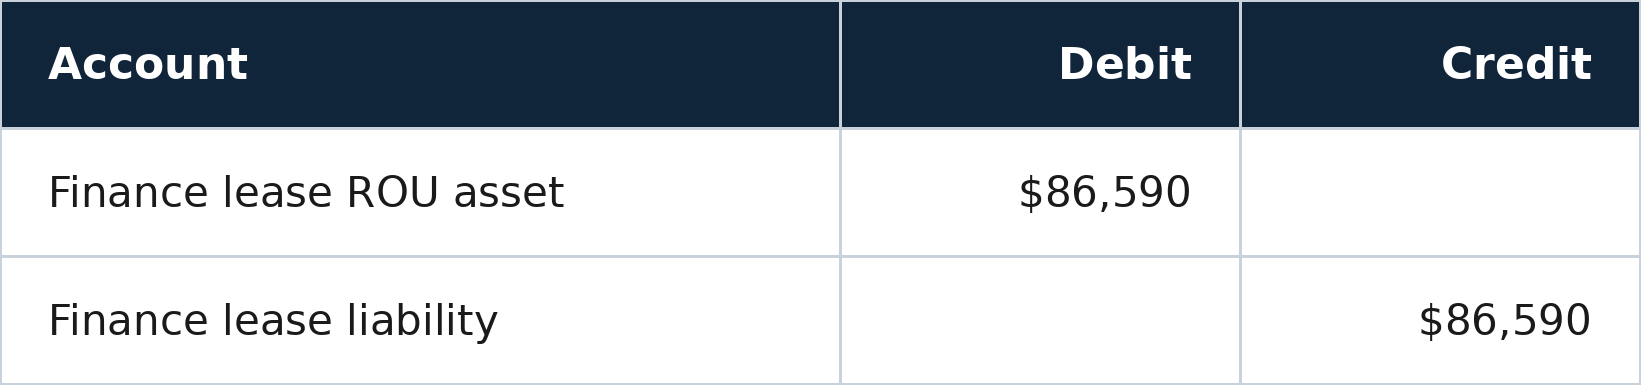
This entry recognizes both the right to use the equipment and the related payment obligation.
Interest Expense
At the end of the first year, before recording the annual payment:
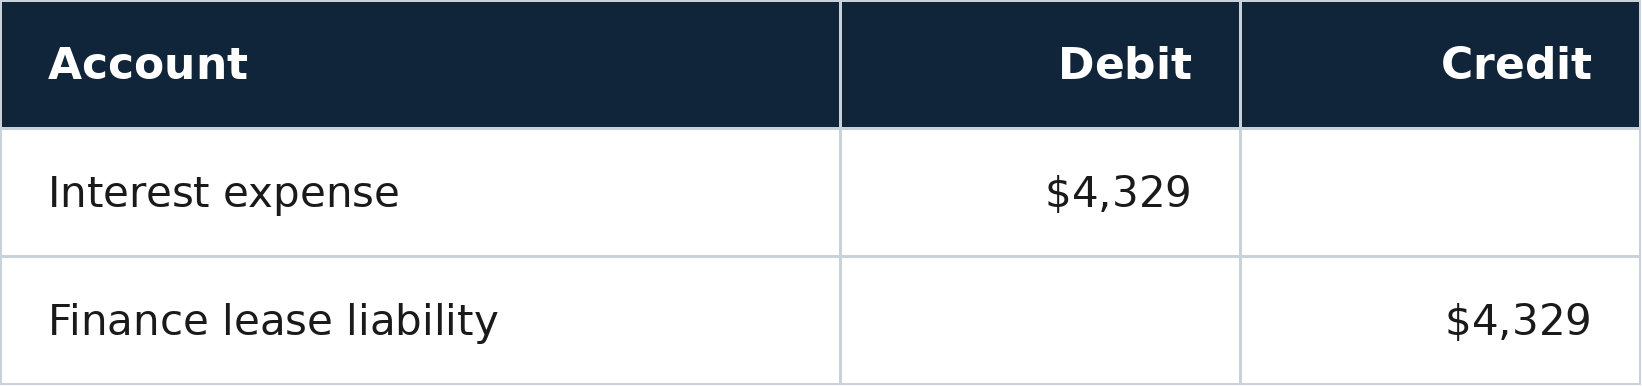
This entry reflects interest accrued on the outstanding lease liability.
Lease Payment
The company then records its $20,000 payment:
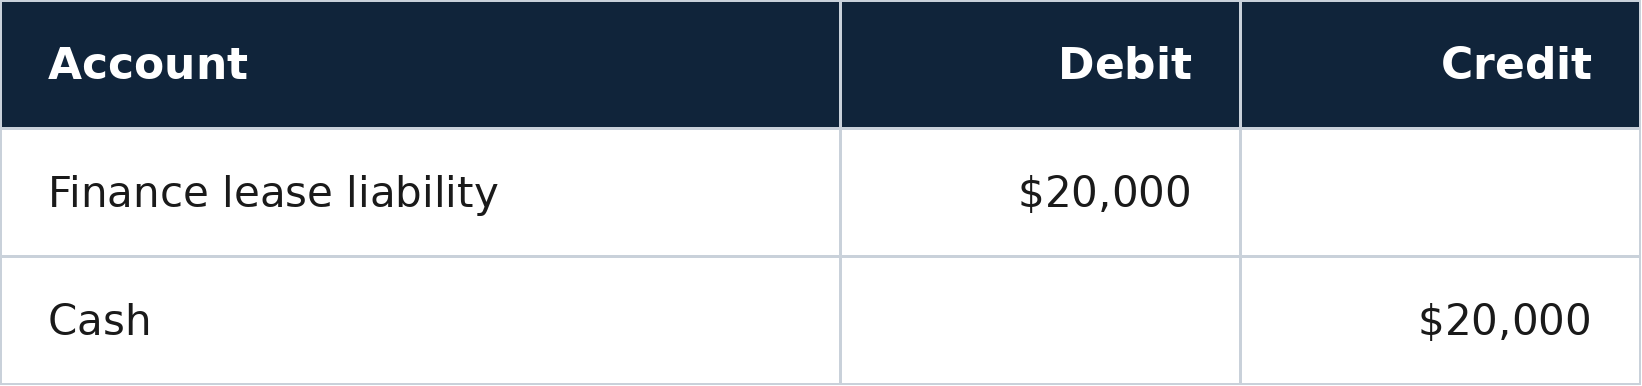
The net reduction in the liability for the year is approximately $15,671.
ROU Asset Amortization
The company separately records annual amortization:
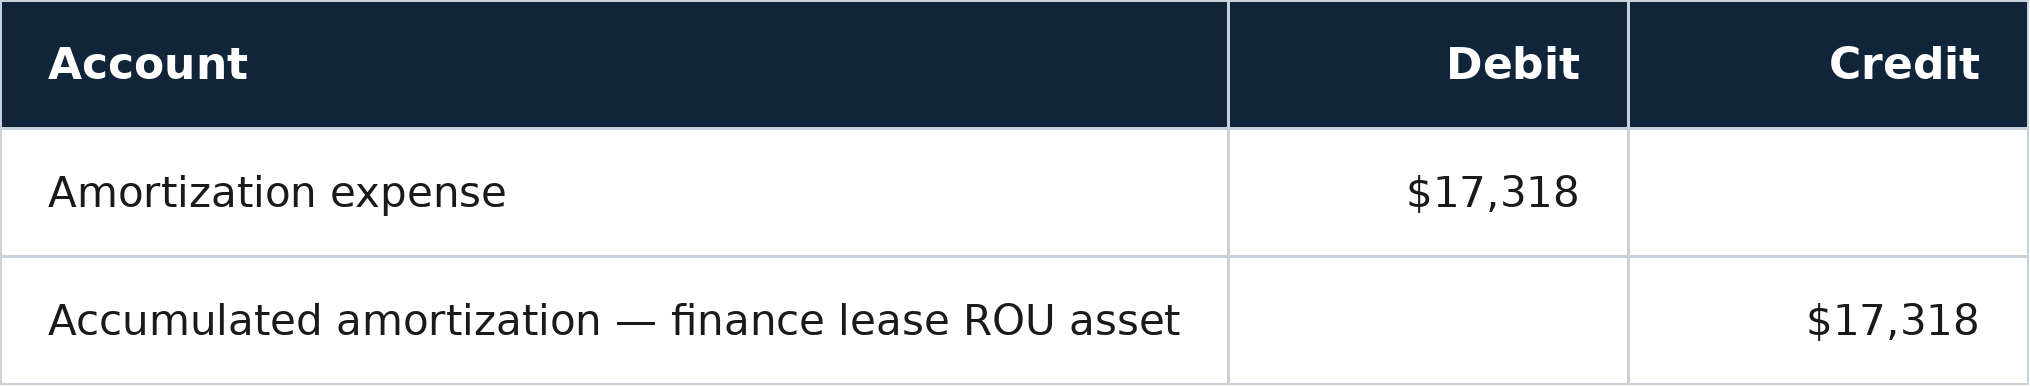
These entries are repeated throughout the lease term using the applicable amortization schedule.
Actual journal entries may differ when leases include initial direct costs, variable payments, modifications, impairment, or other adjustments.
Finance Lease Amortization Schedule
A finance lease amortization schedule tracks the liability from initial recognition through the final payment.
The schedule separates interest expense from the principal reduction associated with each payment.
Using the example above:
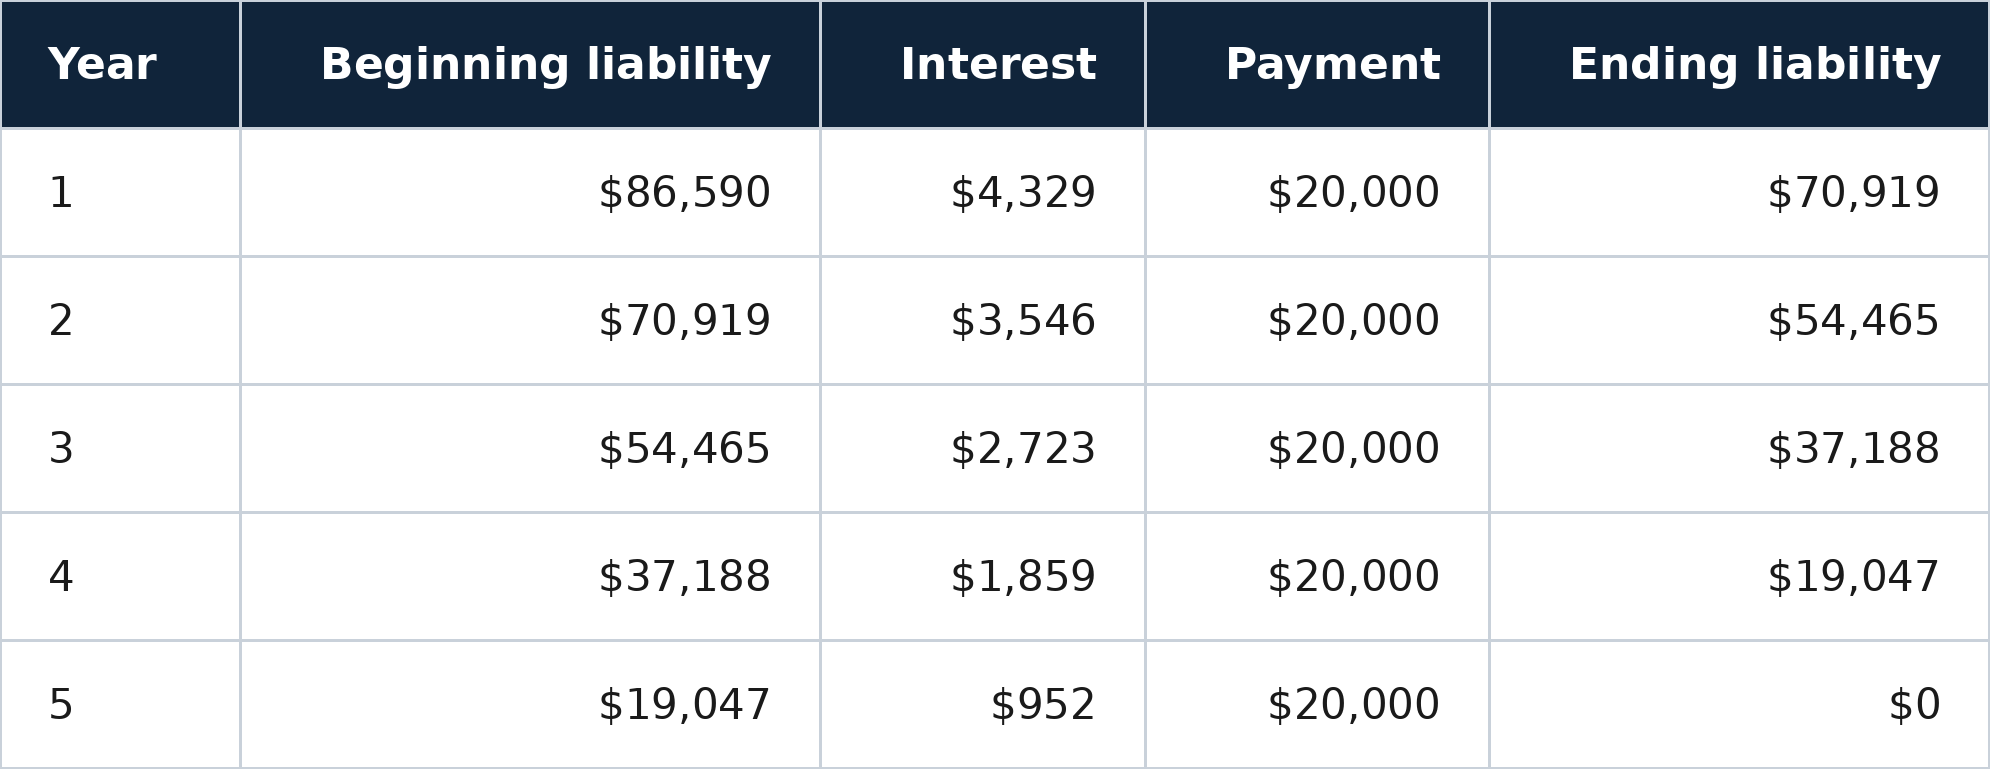
Figures are rounded. The final balance is zero when calculated using the unrounded present value and interest amounts.
The schedule demonstrates how interest expense generally declines as the liability decreases.
Meanwhile, the straight-line ROU asset amortization remains approximately $17,318 annually under the assumptions of this example.
Together, these movements explain the expense pattern associated with finance lease accounting.
What Is the Difference Between a Capital Lease and a Finance Lease?
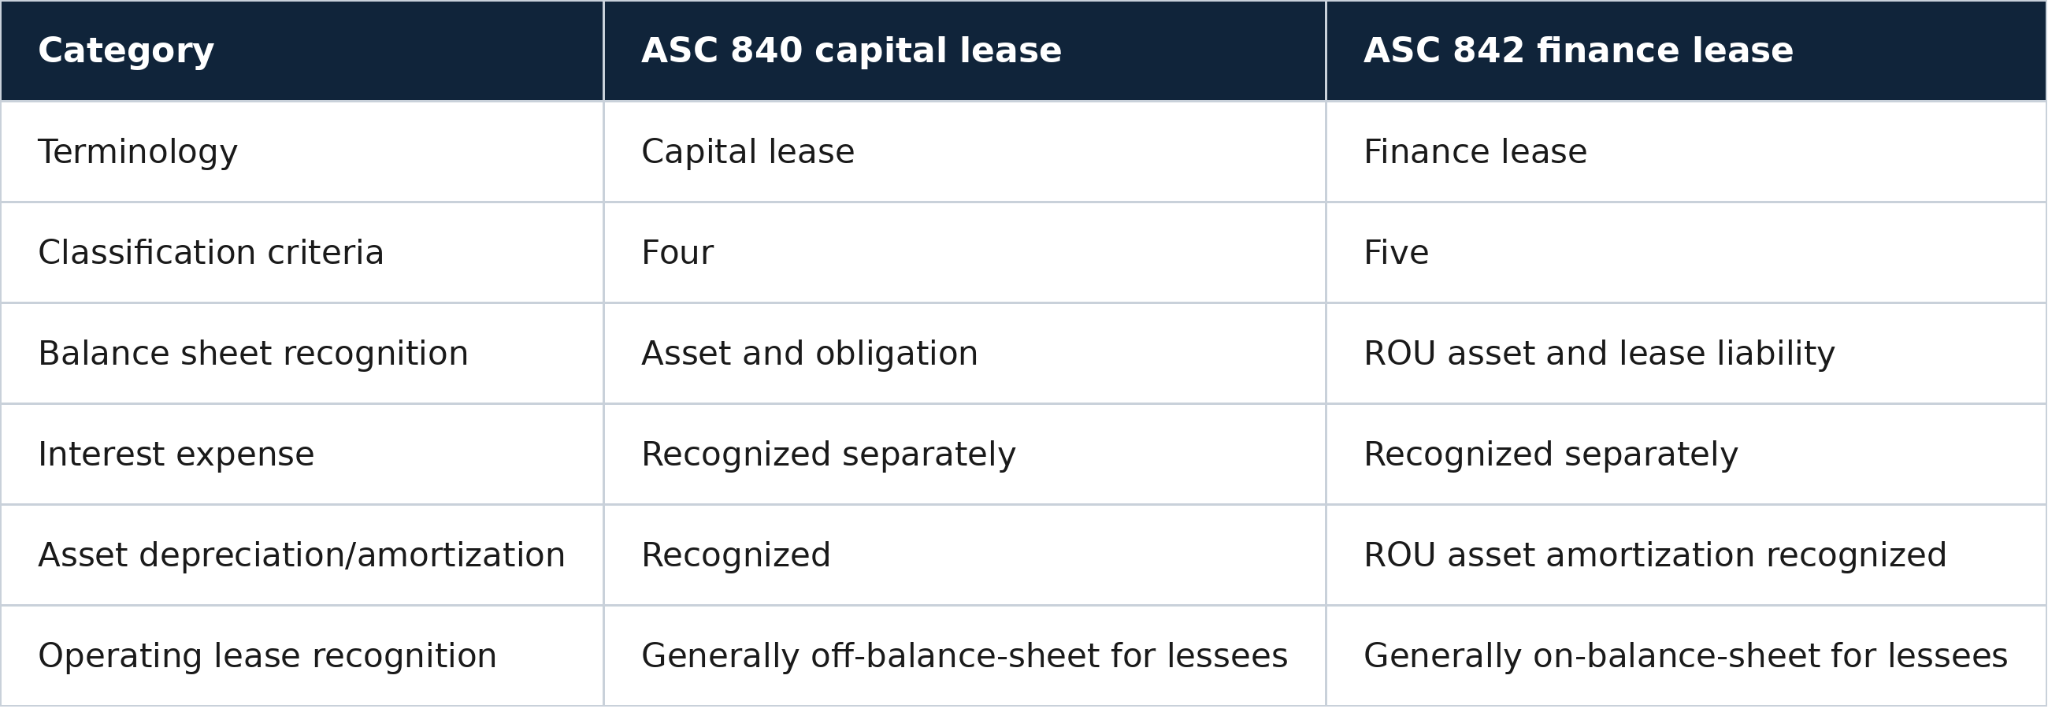
A capital lease is the terminology previously used under ASC 840 for lease arrangements that met specific classification criteria.
When ASC 842 replaced ASC 840, the term "finance lease" replaced "capital lease" for lessee classification under U.S. GAAP.
The underlying concept remains similar: the lease is economically comparable to acquiring an asset through financing rather than paying solely for its temporary use.
However, the accounting standards are not identical.
Under ASC 840, a lessee classified an agreement as a capital lease if it met at least one of four classification tests, including ownership transfer, a bargain purchase option, the lease term test, or the present value test.
ASC 842 replaced these with five finance lease classification criteria, including a specialized-asset criterion.
It also changed the treatment of operating leases by generally requiring their recognition on the balance sheet.
Companies preparing financial statements under U.S. GAAP should use the current finance lease terminology.
The phrase "capital lease" may still appear in older agreements, financial records, and historical reporting discussions.
How Are Embedded Finance Leases Accounted For?
Not every lease appears in a contract labeled as a lease agreement.
An embedded lease exists when a broader contract contains the right to control the use of an identified asset for a period of time in exchange for consideration.
For example, an IT services agreement may provide a company with dedicated servers alongside maintenance, software support, and other services.
If the customer controls the use of identified servers and meets the relevant requirements, the arrangement may contain an embedded lease.
The organization must evaluate the lease component separately from non-lease services, subject to applicable accounting policy elections.
After identifying the lease component, the company determines whether it meets the finance lease classification criteria.
This distinction matters because treating the entire contract as a service expense could result in missing lease assets and liabilities.
Embedded leases can also appear in logistics, manufacturing, transportation, and equipment service agreements.
How Do Finance Leases Affect Financial Statements?
Finance lease accounting affects the three primary financial statements.
On the balance sheet, the company recognizes the finance lease ROU asset and liability. These balances change over time as the asset is amortized and the liability is reduced.
On the income statement, the company recognizes interest expense and ROU asset amortization separately. Under a typical arrangement, total finance lease expense is higher in earlier periods because interest is calculated on a larger outstanding liability.
On the statement of cash flows, the principal portion of finance lease payments is generally classified as a financing activity under U.S. GAAP. Interest payments are generally classified as operating cash flows.
Finance leases also require appropriate qualitative and quantitative disclosures, including information about lease costs, cash flows, maturities, and significant accounting judgments.
Accurate reporting helps financial statement users understand the company's lease obligations and their effects on financial performance.
Common Finance Lease Accounting Mistakes
One common error is applying the classification criteria incorrectly. A lease does not need to meet all five finance lease tests, and legal ownership does not have to transfer.
Another mistake involves calculating present value using inconsistent payment timing or discount rates. Whether payments occur at the beginning or end of each period changes the liability calculation.
Finance teams may also incorrectly treat the entire periodic payment as an expense rather than separating its effects on the liability and interest expense.
Lease modifications create additional challenges. Changes to payment terms, lease duration, or the scope of an agreement may require reassessment or remeasurement.
Finally, failing to identify embedded leases can lead to incomplete accounting records, especially when procurement and finance teams do not share contract information consistently.
Regular reconciliations, documented assumptions, and clear communication between departments help reduce these errors.
Managing Finance Lease Accounting Across Multiple Locations
Organizations managing several finance leases may need to track different commencement dates, payment schedules, discount rates, asset lives, and modification terms.
Maintaining separate spreadsheets for every agreement can make it difficult to reconcile balances, update amortization schedules, and prepare journal entries consistently.
A centralized system helps finance teams organize agreements, review lease classifications, monitor asset and liability balances, and identify reporting changes.
Lease accounting software can support this process by maintaining lease data and generating calculations and reports based on the relevant accounting requirements.
Occupier's lease accounting platform helps commercial real estate and finance teams manage lease obligations, accounting calculations, and financial reporting across their portfolios.
For companies with growing lease portfolios, consistent data management can reduce manual reporting work and make financial reviews more reliable.
Frequently Asked Questions About Finance Lease Accounting
What is finance lease accounting?
Finance lease accounting involves recognizing an ROU asset and lease liability, recording interest expense on the liability, and amortizing the ROU asset according to ASC 842. It applies when a lease meets at least one finance lease classification criterion.
Is a capital lease the same as a finance lease?
A finance lease is the current ASC 842 terminology for the category previously called a capital lease under ASC 840. Although the concepts are similar, their classification rules and related accounting standards are not identical.
How is interest calculated on a finance lease?
Interest expense is generally calculated by applying the appropriate periodic discount rate to the outstanding lease liability, taking payment timing into account. As the liability decreases, the interest expense typically declines.
Are finance leases recorded on the balance sheet?
Yes. Finance leases are recognized as ROU assets and lease liabilities on the lessee's balance sheet under ASC 842.
What is the difference between finance lease amortization and lease liability reduction?
ROU asset amortization allocates the cost of the right to use an asset over the appropriate period. Lease liability reduction reflects payments applied against the outstanding obligation after accounting for interest accrual.
Does a finance lease always transfer ownership?
No. Ownership transfer is only one of the five criteria for finance lease classification. A lease can qualify based on its term, the present value of payments, a reasonably certain purchase option, or the specialized nature of the asset.
Lease management that works for real estate and finance
15,000 sq ft
90 days notice
March 2026
Action required