Operating Lease Journal Entries Under ASC 842: Examples
What is the journal entry for an operating lease at commencement?
Debit the ROU asset and credit the lease liability for the present value of the lease payments. Adjust the ROU asset for initial direct costs, prepaid rent and lease incentives.
Operating Lease Journal Entries Under ASC 842: Examples
Meta Description: Step-by-step operating lease journal entries under ASC 842: commencement, monthly entries, current vs. non-current liability, modifications and terminations.
Operating lease journal entries under ASC 842 record a right-of-use (ROU) asset and a lease liability when the lease begins. Each month after that, they record the lease payment, a single straight-line lease expense, interest accretion on the liability and the matching reduction of the ROU asset. Unlike a finance lease, an operating lease never shows separate interest and amortization expense: the whole cost is recognized as one operating expense. The entries also change when the lease is modified or terminated.
For commercial tenants, CPAs and accounting and finance teams, lease journal entries are a month-end task. Getting them right comes down to three things:
- initial recognition and measurement
- the monthly entries for payments, expense and the balance sheet
- adjustments when the lease changes
This guide walks through each operating lease journal entry with a worked example, including modifications and terminations.
Why are operating lease journal entries important?
Lease journal entries make sure lease obligations and the related assets are accurately recorded on the balance sheet and income statement. They support compliance with ASC 842 under US GAAP and give stakeholders a true picture of the company’s financial position.
When companies lease assets such as office space, stores or equipment, they must record those arrangements accurately in their financial statements. Most real estate leases are operating leases, so for many companies these are the most common lease entries they record. Errors are easy to make and hard to spot: a wrong straight-line figure or a missed remeasurement carries through every month for the rest of the lease.
What are the key concepts in lease accounting?
Four concepts underpin all lease journal entries: lease classification, lease term, lease payments, and the discount rate used to calculate the present value of future obligations.
1. Lease Classification
Under ASC 842, a lease is either an operating lease or a finance lease. It’s a finance lease if it meets any one of five criteria, such as transferring ownership, including a purchase option the lessee is reasonably certain to exercise, or covering the major part of the asset’s economic life. Otherwise, it’s an operating lease. Most office, retail and restaurant leases are operating leases. Classification determines how the lease cost is recognized in the income statement. See how to perform a lease classification test.
2. Lease Term
The lease term is the period during which the lessee has the right to use the leased asset. It includes the non-cancellable period plus any renewal periods the lessee is reasonably certain to exercise, and any periods after a termination option the lessee is reasonably certain not to exercise.
3. Lease Payments
Lease payments include fixed payments (such as base rent), variable payments based on an index or rate (such as CPI), and amounts for purchase options or termination penalties the lessee expects to pay. They don’t include variable payments based on usage or sales, or variable CAM, taxes and insurance that change year to year. Those are expensed as incurred. Fixed charges for non-lease services are included only if you elect to combine lease and non-lease components.
4. Discount Rate
The discount rate is the interest rate used to calculate the present value of future lease payments. It’s the rate implicit in the lease if that can be readily determined. Otherwise it’s the lessee’s incremental borrowing rate, or the risk-free rate for private companies that elect it.
Which accounts are used in operating lease journal entries?
Operating lease journal entries under ASC 842 usually involve four main accounts:
- ROU Asset: records the lessee’s right to use the leased asset over the lease term. The initial balance starts with the lease liability and is adjusted for items such as prepaid rent, initial direct costs and lease incentives.
- Lease Liability: records the present value of the remaining lease payments. The liability decreases when lease payments are made and increases each period for accretion.
- Operating Lease Expense: records the single straight-line lease expense recognized on the income statement each period.
- Cash: records the actual lease payment made to the lessor.
For balance sheet presentation, the lease liability is usually separated into:
- Current Lease Liability: the portion expected to be paid within the next 12 months.
- Non-Current Lease Liability: the portion due after the next 12 months.
Items such as initial direct costs, prepaid rent and lease incentives affect the initial measurement of the ROU asset, but they are not separate recurring accounts in every monthly operating lease journal entry.
Operating Lease Journal Entries: Step-by-Step Example
Here is the example lease used for every entry below:
- Office lease, 24 months
- Rent: $10,000 per month, paid at the beginning of each month
- Discount rate: 6% per year (0.5% per month)
- Initial direct costs: $2,400 broker commission, paid at commencement
- Operating lease
The lease liability at commencement is $226,756.81 (the present value of 24 payments of $10,000). The ROU asset is $226,756.81 + $2,400 = 229,156.81.Thestraight-lineleaseexpenseis(240,000 + $2,400) ÷ 24 = $10,100 per month.
1. Initial Recognition
On the commencement date, record the ROU asset and lease liability, and the initial direct costs paid:
- Debit: ROU Asset, $229,156.81
- Credit: Lease Liability, $226,756.81
- Credit: Cash, $2,400.00
For the balance sheet, split the liability into current and non-current portions. In this example, $109,986.54 of the liability will be paid down in the next 12 months (current), and $116,770.27 is non-current.
2. Subsequent Measurement: The Monthly Entries
Many teams record operating leases in two steps each month.
When the rent is paid (start of the month):
- Debit: Lease Liability, $10,000.00
- Credit: Cash, $10,000.00
At month-end, record the straight-line lease expense. Interest accretion increases the lease liability, and the rest of the expense reduces the ROU asset:
- Debit: Operating Lease Expense, $10,100.00
- Credit: Lease Liability (accretion), $1,083.78
- Credit: ROU Asset, $9,016.22
The accretion is 0.5% of the liability outstanding after the payment ($216,756.81 × 0.5% = 1,083.78).TheROUassetreductionistheleaseexpenseminustheaccretion(10,100.00 − $1,083.78). The accretion is not recorded as interest expense. For an operating lease, the full $10,100 is reported as a single operating expense.
Full 12-Month Operating Lease Example
The table below shows how the lease liability and ROU asset move during the first 12 months.
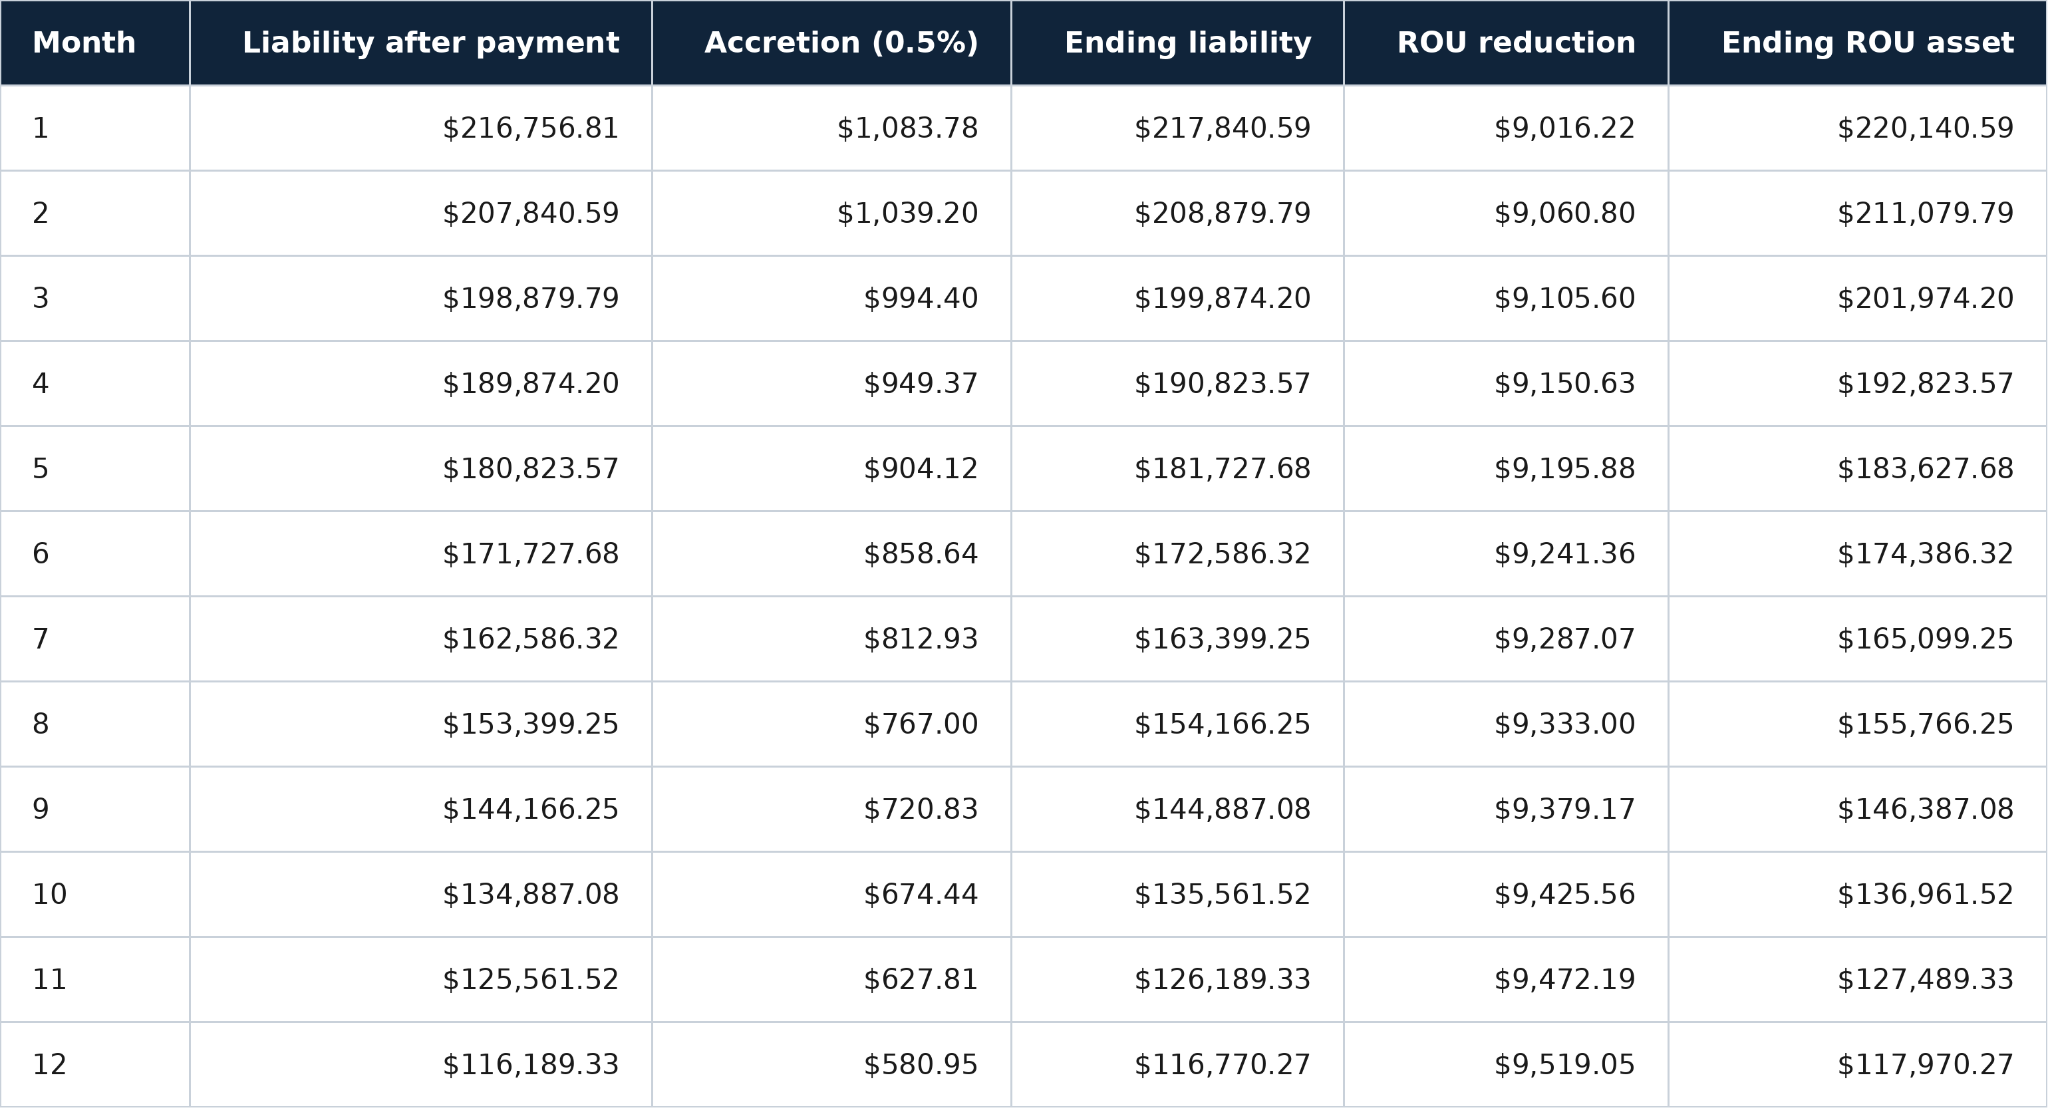
Each month, as the accretion falls, more of the fixed $10,100 expense goes to reducing the ROU asset. Both balances reach zero at the end of month 24.
For the complete schedule and formulas, download Occupier’s free Lease Amortization Schedule Excel Template.
The downloadable template calculates lease liabilities, ROU asset balances, interest or accretion, payments, and the journal-entry amounts used throughout the lease term.
Current vs. non-current reclass. At each reporting date, reclassify from non-current to current so the current portion equals the principal due over the next 12 months:
- Debit: Lease Liability: Non-Current
- Credit: Lease Liability: Current
3. Lease Modifications
When lease terms change, such as a longer term or new rent, the lessee remeasures the lease liability using an updated discount rate and adjusts the ROU asset by the same amount. The exception is a modification that grants an additional right of use at a stand-alone price, which is treated as a separate lease.
Example: At the end of month 12, the tenant extends the lease by 12 months at $10,500 per month, and its discount rate is now 7%. Before the change, the lease liability is $116,770.27 and the ROU asset is $117,970.27. Remeasuring the remaining 24 payments at 7% gives a new lease liability of $230,074.30, an increase of $113,304.03:
- Debit: ROU Asset, $113,304.03
- Credit: Lease Liability, $113,304.03
The straight-line expense is then recalculated over the remaining term. Take the total lease payments plus initial direct costs, less the lease expense already recognized ($368,400 − $121,200 = $247,200), and spread it over the remaining 24 months: $10,300 per month from month 13. See how to account for lease modifications under ASC 842.
4. Lease Termination
When a lease is terminated before its original end date, remove the lease liability and ROU asset and recognize the difference, plus any termination payment, as a gain or loss.
Example: Going back to the original lease, the tenant terminates at the end of month 18 and pays the landlord a $15,000 termination fee. At that date, the lease liability is $59,258.66 and the ROU asset is $59,858.66:
- Debit: Lease Liability, $59,258.66
- Debit: Loss on Lease Termination, $15,600.00
- Credit: ROU Asset, $59,858.66
- Credit: Cash, $15,000.00
The $15,600 loss is the $15,000 fee plus the $600 by which the ROU asset exceeded the liability. If the termination is agreed now but takes effect later, treat it as a modification that shortens the lease term instead. See partial lease terminations for when only part of the space is given back.
See how Occupier automates operating lease journal entries →
How are short-term operating leases recorded?
If a lease has a term of 12 months or less and no purchase option the lessee is reasonably certain to exercise, the lessee can elect the short-term lease exemption. No ROU asset or lease liability is recorded. Lease payments are simply expensed straight-line over the term:
- Debit: Lease Expense
- Credit: Cash
The election is made by class of underlying asset, and short-term lease cost must still be disclosed. See ASC 842 long-term vs. short-term leases.
What do real estate and finance teams need to remember about lease accounting journal entries?
Accurate operating lease journal entries depend on correct lease classification, consistent monthly entries, and timely remeasurement when leases are modified or terminated. The most common errors are:
- expensing the cash payment instead of the straight-line lease cost
- recording accretion as interest expense
- forgetting the current and non-current reclass
- missing a lease change that should have triggered remeasurement
The last one is usually a communication problem, not an accounting one. Real estate signs the amendment, and finance finds out at year-end. Lease accounting software closes that gap. Occupier’s lease accounting software:
- generates operating and finance lease journal entries automatically
- recalculates them when a lease is amended
- exports them to your ERP
This keeps real estate and finance working from the same lease data.
For the finance lease equivalent, see Mastering Finance Lease Accounting under ASC 842, which explains the separate finance lease interest and ROU asset amortization entries.
Operating Lease Journal Entries FAQs
What is the journal entry for an operating lease at commencement?
Debit the ROU asset and credit the lease liability for the present value of the lease payments. Adjust the ROU asset for initial direct costs, prepaid rent and lease incentives.
What are the monthly journal entries for an operating lease under ASC 842?
Record the payment (debit lease liability, credit cash). Then record the straight-line lease expense, credit the lease liability for interest accretion, and credit the ROU asset for the difference.
Is interest recorded on an operating lease?
The lease liability accretes interest, but it isn’t reported as interest expense. For an operating lease, it’s part of the single straight-line operating lease expense.
How is operating lease expense calculated under ASC 842?
Total lease payments plus initial direct costs, less lease incentives, divided by the lease term. It’s recognized evenly each period, regardless of when cash is paid.
Where can I download an operating lease amortization schedule?
Occupier provides a free Lease Amortization Schedule Excel Template that can be used to calculate lease liability, ROU asset, payments, and journal-entry amounts.
What is the journal entry for an operating lease modification?
Remeasure the lease liability with an updated discount rate. Debit or credit the ROU asset for the change, and credit or debit the lease liability by the same amount.
What is the journal entry when an operating lease is terminated early?
Debit the lease liability, credit the ROU asset, credit cash for any termination fee, and record the difference as a gain or loss.
Lease management that works for real estate and finance
15,000 sq ft
90 days notice
March 2026
Action required