Lease Incentives: Accounting Best Practices Under ASC 842

What is a lease incentive under ASC 842?
A payment or reimbursement from the lessor to the lessee, or a cost the lessor takes on for the lessee, such as the lessee’s old lease, in connection with a new lease.
A lease incentive is a payment, reimbursement, or other benefit a landlord provides to a tenant for entering into a lease. Common examples are a tenant improvement allowance, a cash payment, or taking over the tenant’s old lease. Under ASC 842 and IFRS 16, incentives received at or before commencement reduce the initial right-of-use (ROU) asset, and incentives still receivable reduce the lease payments used to measure the lease liability. Finance teams need to identify each incentive, determine when it’s paid, and decide whether any related improvements are lessee or lessor assets before recording the journal entry.
During lease negotiations, it’s common for landlords (lessors) and tenants (lessees) to agree on terms that make a deal more attractive. Lessors want their space to be competitive, and lessees want the best deal they can get. Some of those negotiated terms are lease incentives, and ASC 842 has specific rules for how they’re recorded.
This guide covers what counts as a lease incentive, how incentives are measured based on when they’re paid, how tenant improvement allowances fit in, and a worked example.
What is a lease incentive under ASC 842 and IFRS 16?
A lease incentive is a payment made to, or on behalf of, the lessee in connection with a lease. These incentives work like “lease specials” to encourage the tenant to sign.
ASC 842 defines a lease incentive as:
- Payments made to or on behalf of the lessee
- Losses incurred by the lessor as a result of assuming a lessee’s pre-existing lease with a third party
IFRS 16 defines a lease incentive as payments made by a lessor to a lessee associated with a lease, or the reimbursement or assumption by a lessor of costs of a lessee.
Many features can be negotiated into a lease, but not all of them are lease incentives. The test is whether the lessor pays cash to the lessee, pays costs on the lessee’s behalf, or takes on the lessee’s obligations.
Common lease incentives:
- A cash payment from the lessor to the lessee
- A tenant improvement allowance (TIA) used to build out the space, where the improvements belong to the tenant
- Moving expense reimbursements
- The lessor “buying out” or taking over the lessee’s previous lease
Not lease incentives:
- Free or reduced rent periods. No cash moves from the lessor to the lessee. The benefit is already captured because those months have little or no lease payment, which lowers the lease liability and the straight-line lease cost.
- Below-market rent. This is also already reflected in the lease payments.
- Allowances for improvements the lessor owns. The lessor is paying for its own asset.
Lease incentives are often exchanged at the start of a lease, but it’s also common for them to be paid after the commencement date. That timing drives the accounting.
How are lease incentives accounted for under ASC 842 and IFRS 16?
Lease incentives fall into three categories based on timing. Each one is recorded differently.
1. Incentives paid at or before commencement
These reduce the ROU asset at initial recognition:
ROU asset = Lease liability + Initial direct costs + Prepaid lease payments − Lease incentives received
The lease liability isn’t affected, because the incentive has already been received.
2. Incentives payable at commencement but not paid until after commencement
These reduce the lease payments used to measure the lease liability. The incentive is treated as a negative lease payment in the period it’s expected to be received. This lowers both the lease liability and the ROU asset at commencement.
When the cash arrives, the lessee records it against the lease liability.
3. Contingent lease incentives
Some incentives depend on a future event, such as completing construction or meeting a condition in the lease. These are neither paid nor payable at commencement. See the contingent incentives section below.
In every case, the incentive affects the accounting for the rest of the lease. For an operating lease, it lowers the straight-line lease cost recognized each period. For a finance lease, it lowers the ROU asset and so reduces amortization expense. Tenant improvements themselves are amortized separately as leasehold improvements.
How does the timing of a tenant improvement allowance affect the accounting?
The accounting changes depending on whether the tenant improvement allowance is received before or at commencement, or whether it is payable at commencement but received later.
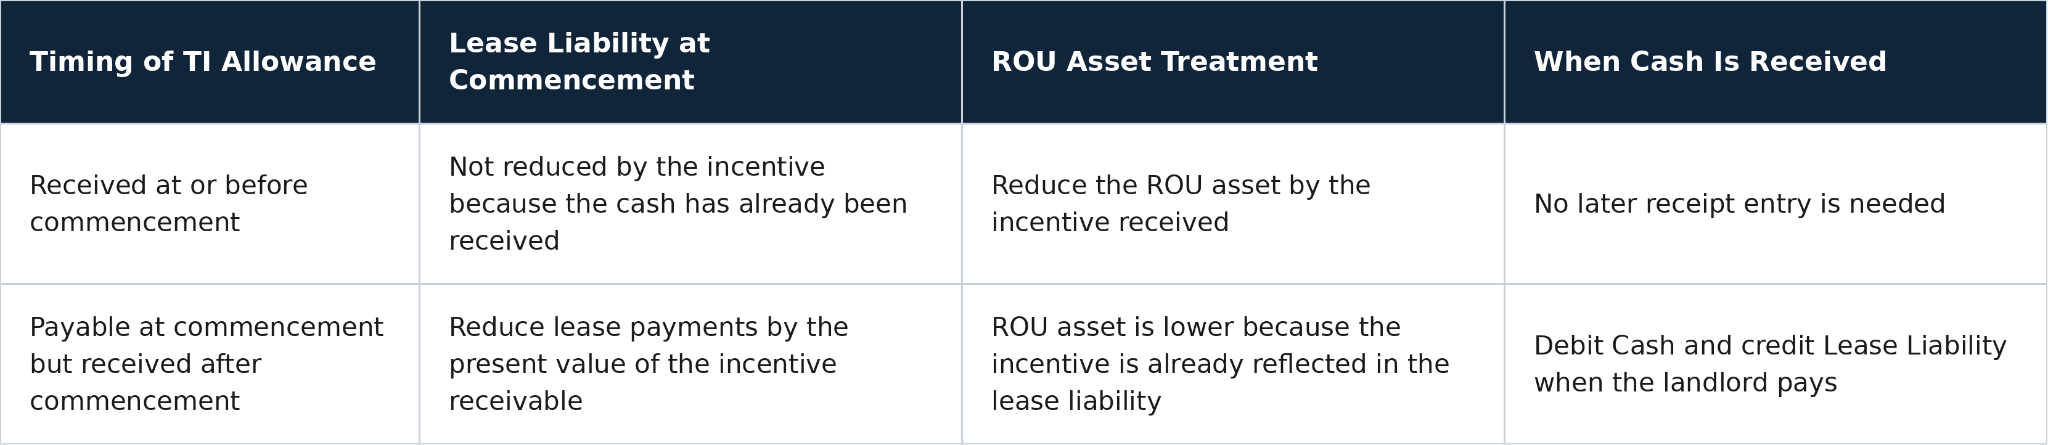
The economic benefit may be similar, but the timing changes which balance is adjusted at commencement and how the later cash receipt is recorded.
How is a tenant improvement allowance reported under ASC 842?
A tenant improvement allowance is the most common lease incentive in commercial real estate. It’s money the landlord gives the tenant to build out or renovate the space.
It’s important to separate the allowance from the improvements it pays for:
- The allowance is the lease incentive. If the improvements are lessee assets, the allowance reduces the ROU asset, or the lease payments if it’s received after commencement.
- The improvements are recorded separately as leasehold improvements at their full cost, and amortized over the shorter of their useful life and the lease term. See our guide to leasehold improvements.
Under ASC 840, lease incentives like TI allowances, moving expenses and reduced rent were recorded as a separate liability, which was reduced straight-line over the lease term. Under ASC 842, that liability no longer exists. The incentive is built into the ROU asset and lowers the lease cost over the life of the lease. Any remaining ASC 840 incentive liability was deducted from the ROU asset on the adoption date, the same way deferred rent was.
First and foremost, determine who owns the leasehold improvement asset. Is it a lessee asset or a lessor asset?
- Lessee asset: The allowance is a lease incentive.
- Lessor asset: The allowance is not a lease incentive. The lessor is paying for its own asset, and any amounts the lessee contributes toward lessor-owned improvements are generally treated as lease payments.
For the full decision process and the accounting for lessor assets, see our guide to tenant improvement allowance accounting.
What does lease incentive accounting look like in practice?
In the example below, a retailer receives a $50,000 fit-out contribution from its landlord. The lessor is reimbursing the lessee for fittings and fixtures such as dressing rooms, clothing storage and check-out stations. The improvements are lessee assets, so the reimbursement is a lease incentive.
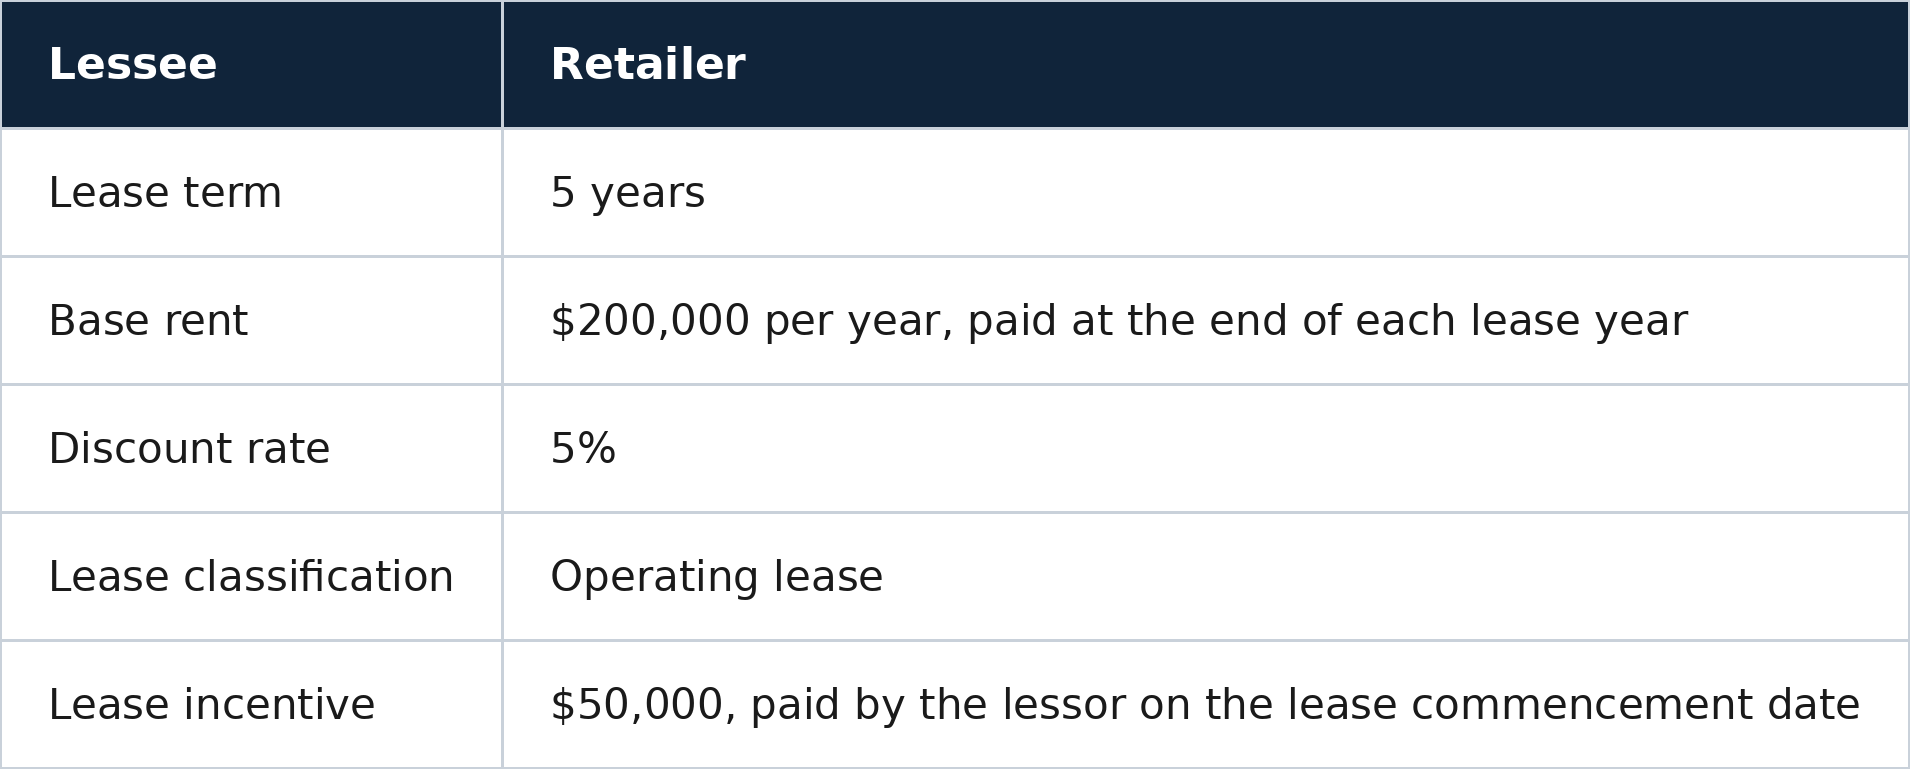
Step 1: Calculate the lease liability.
Discounting the five annual payments of $200,000 at 5% gives a present value of $865,895.33. This is the lessee’s lease liability at commencement. You can calculate it with Occupier’s free present value calculator.
Step 2: Calculate the ROU asset.
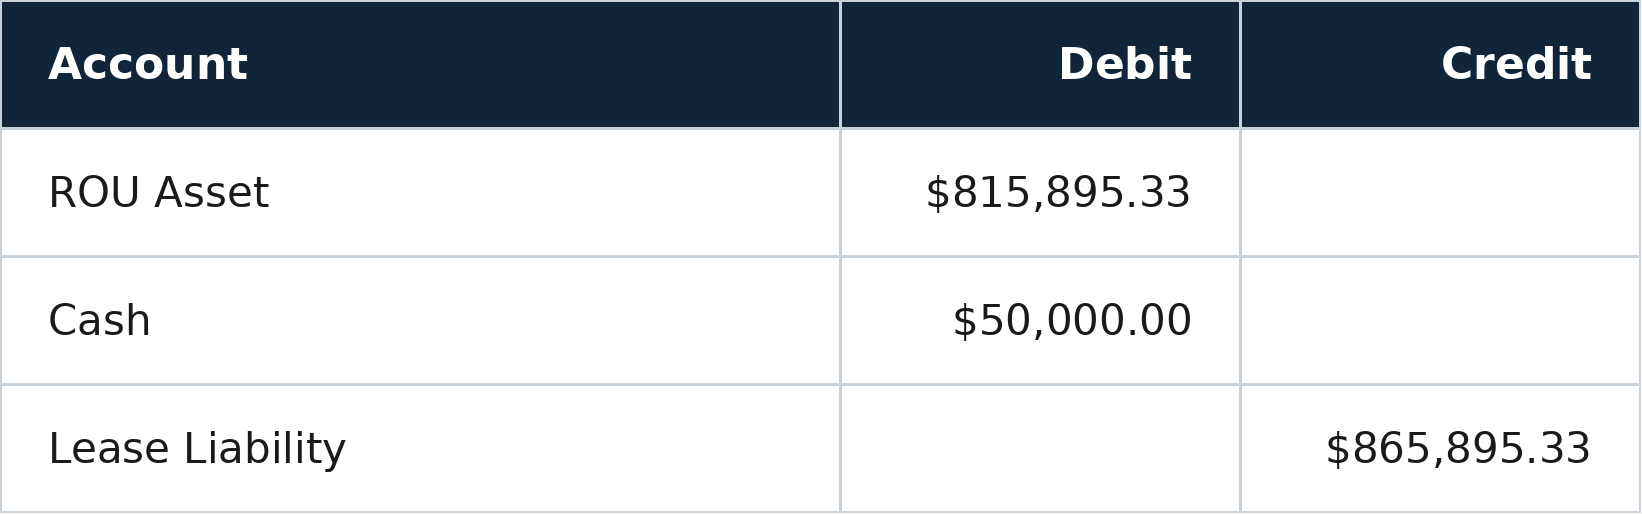
The lessee received the $50,000 incentive at commencement, so it’s subtracted from the lease liability:
$865,895.33 − $50,000 = $815,895.33
Journal Entry Recorded at the Lease Commencement Date
Step 3: Recognize the lease cost.
The incentive is spread over the lease term through a lower straight-line lease cost. Total cash rent is $1,000,000, less the $50,000 incentive, over 5 years:
$950,000 ÷ 5 = $190,000 per year
Cash rent is $200,000 a year, so the incentive lowers the reported lease cost by $10,000 every year.
See how Occupier automates lease incentive accounting →
What if the lease incentive is paid after commencement?
Now suppose the same $50,000 is payable at commencement, but the landlord pays it six months later.
Instead of reducing the ROU asset directly, the incentive is treated as a negative lease payment:
- Lease liability at commencement: $865,895.33 for the rent, less $48,795.00 for the incentive receivable in six months, which gives $817,100.33.
- ROU asset at commencement: also $817,100.33, because the incentive is already reflected in the liability.
- When the cash is received: debit Cash and credit Lease Liability for $50,000.
Journal Entry When the TI Allowance Is Received After Commencement
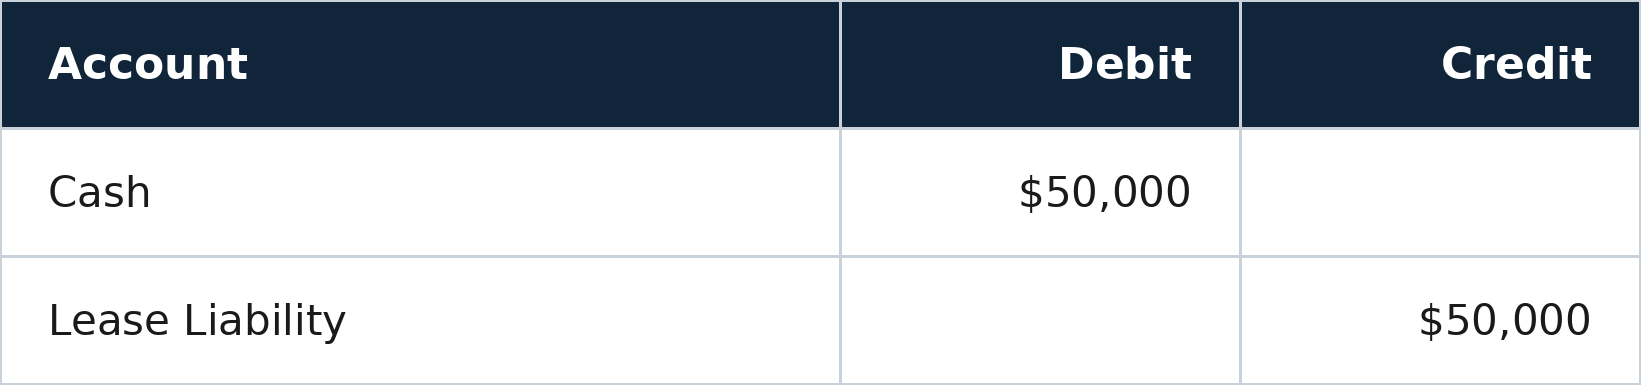
The total benefit over the lease is the same. The difference is timing: the incentive reduces the liability at commencement and increases it when the landlord pays.
Track allowances that are still owed. If a landlord pays late, or pays less than agreed, the lease accounting needs to be updated.
How are contingent lease incentives accounted for under ASC 842?
Contingent lease incentives are neither paid nor payable at commencement, because they depend on a future event. ASC 842 doesn’t directly address this category, so there are different interpretations of how to account for it.
A common approach is to estimate the amount and timing of the incentive and account for it as payable at commencement. If the actual amount or timing turns out to be significantly different, remeasure the lease liability and ROU asset.
Another approach is to recognize the incentive only when the contingency is resolved.
Choose one approach, document it in your lease accounting policy, and apply it consistently. See our guide to writing a lease accounting policy memo.
What are the best practices for managing lease incentives under ASC 842?
Lease incentives can appear in both operating and finance leases. They affect the ROU asset, journal entries and lease expense for the entire term. To get them right:
- Read the whole lease, including amendments. Incentives can be buried in work letters, side letters and amendments, not just in the main rent clause.
- Don’t double count free rent. Free rent is already captured in the lease payments and shouldn’t be deducted again as an incentive.
- Record the timing. Note whether each incentive is received at or before commencement, receivable later, or contingent.
- Decide on asset ownership first. For tenant improvement allowances, determine whether the improvements are lessee or lessor assets before recording anything.
- Keep improvements and allowances separate. Record leasehold improvements at their full cost, and the allowance as an incentive.
- Follow up on receivables. Landlords don’t always pay allowances on time. Track what’s still owed and update the accounting when it’s paid.
Tracking all of this in Excel across a portfolio of leases is error-prone, especially when allowances arrive months after commencement. Occupier’s lease accounting software applies each incentive to the ROU asset and lease liability, generates the journal entries, and keeps real estate and finance working from the same lease data.
Request a demo to see how it works.
Lease Incentives FAQs
What is a lease incentive under ASC 842?
A payment or reimbursement from the lessor to the lessee, or a cost the lessor takes on for the lessee, such as the lessee’s old lease, in connection with a new lease.
Is free rent a lease incentive under ASC 842?
No. Free rent involves no payment from the lessor, so it’s reflected in the lease payments rather than treated as an incentive.
How do lease incentives affect the ROU asset?
Incentives received at or before commencement are deducted from the ROU asset. Incentives still receivable reduce the lease liability, and therefore the ROU asset, at commencement.
Is a tenant improvement allowance a lease incentive?
Yes, if the improvements it funds are lessee assets. If they’re lessor assets, the allowance isn’t a lease incentive.
How are lease incentives recognized in the income statement?
For an operating lease, they reduce the straight-line lease cost over the lease term. For a finance lease, they reduce the ROU asset and therefore the amortization expense.
What happened to lease incentive liabilities at ASC 842 transition?
Any remaining ASC 840 lease incentive liability was removed and deducted from the ROU asset on the adoption date.

Lease management that works for real estate and finance
15,000 sq ft
90 days notice
March 2026
Action required