Leasehold Improvements: Accounting, Amortization & Tax Treatment
What are leasehold improvements?
Leasehold improvements are changes made to leased property to make the space suitable for the tenant's operations. Examples include interior build-outs, flooring, lighting, walls, and certain electrical or plumbing upgrades.
Leasehold improvements are changes a tenant makes to leased space to make it suitable for its business, such as building out offices, installing lighting and flooring, or upgrading electrical systems.
For accounting purposes, qualifying leasehold improvements are generally capitalized as fixed assets rather than expensed immediately. They are typically amortized over the shorter of the improvement's useful life or the remaining lease term.
For US tax purposes, many qualifying interior improvements to nonresidential property may be treated as qualified improvement property (QIP), which generally has a 15-year recovery period under MACRS. Certain QIP may also qualify for bonus depreciation or Section 179 treatment, depending on the facts and applicable tax rules.
Real estate and finance teams should agree on which costs qualify, who owns the improvements for accounting purposes, and how the related lease terms affect amortization before anything is recorded.
Leasehold improvements can represent a significant part of the cost of opening, renovating, or expanding a location. Without proper accounting, businesses can amortize improvements over the wrong period, confuse them with tenant improvement allowances, or end up with unexpected write-offs when a lease terminates.
In this post, we cover:
- What counts as a leasehold improvement
- How leasehold improvements are accounted for
- How to calculate amortization
- Leasehold improvement journal entries
- QIP tax treatment
- Who owns improvements when the lease ends
- Best practices for real estate and finance teams
What are leasehold improvements?
Leasehold improvements are changes made to leased space to make it more functional or suitable for the tenant's operations.
Common examples include:
- Building out new office space or renovating existing space
- Installing flooring, lighting, ceiling tiles, and millwork
- Upgrading electrical, plumbing, or HVAC systems serving the tenant's space
- Adding or modifying interior walls, doors, and partitions
- Installing built-in security or access control systems
- Adding or modifying restrooms, kitchens, or break rooms
- Installing structured cabling and built-in technology infrastructure
In many cases, the scope of these improvements is agreed during lease negotiations. The tenant may pay the full cost or receive financial support from the landlord through a tenant improvement allowance.
Not everything a tenant purchases qualifies as a leasehold improvement.
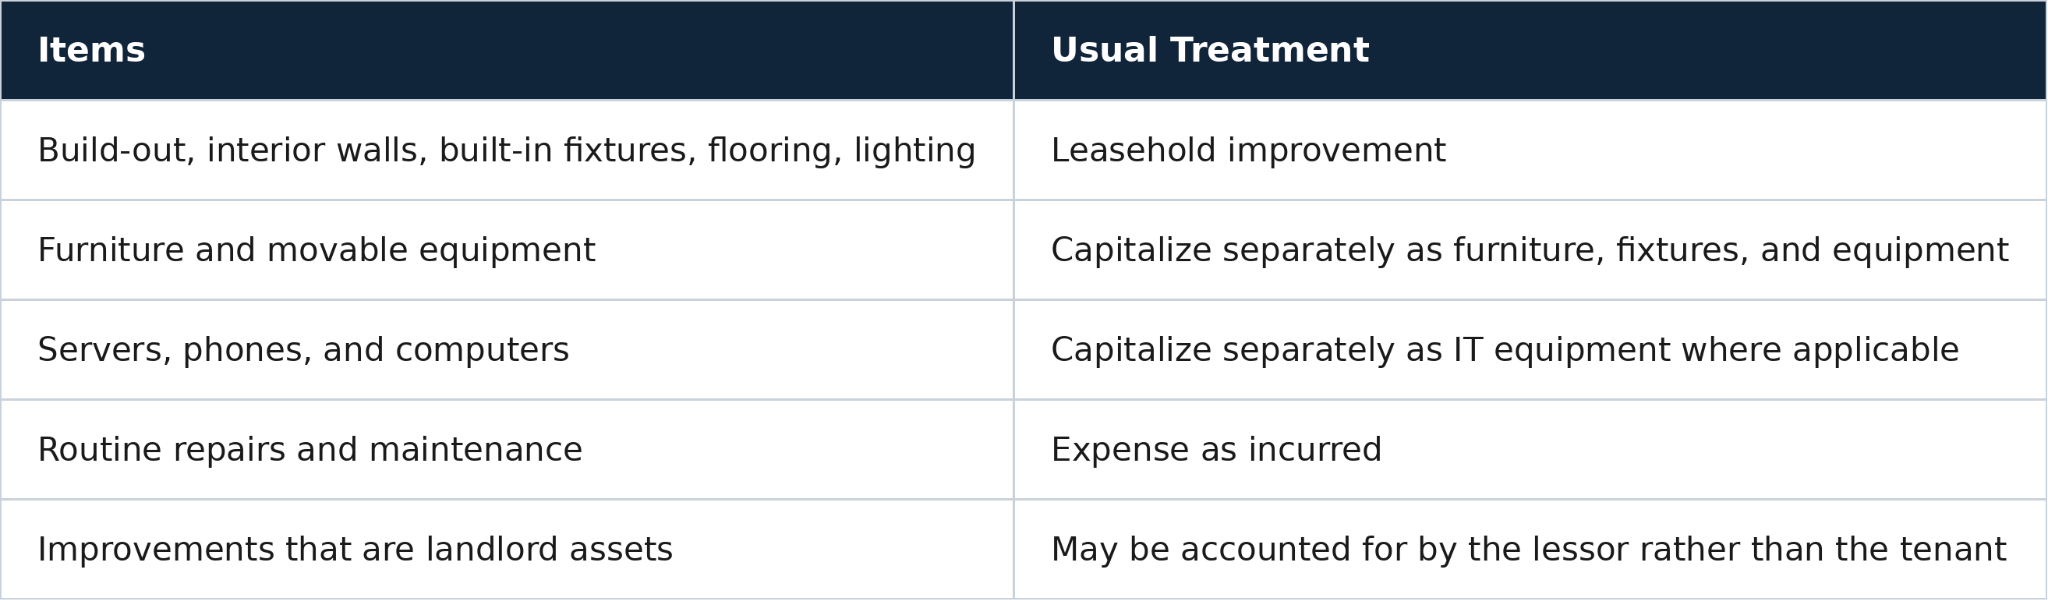
How do you know if an asset qualifies as a leasehold improvement?
One of the most important questions is whether the improvement is an asset of the tenant or the landlord.
If it is a tenant asset, it is generally capitalized as a leasehold improvement. If it is a landlord asset, the accounting can differ, particularly when the tenant contributes to the cost through lease payments or another arrangement.
Ask the following questions:
- Is the improvement specific to the tenant's use? A customized build-out designed for the tenant's operations is more likely to be treated as a tenant asset.
- Who controls the improvement during the lease? The lease agreement and construction arrangement can help determine whether the tenant or landlord controls the asset.
- Who paid for the improvement? Determine whether the tenant paid directly or whether the landlord funded the work through an allowance.
- Will the improvement benefit future tenants? General building improvements may be more likely to benefit the landlord.
- What is the expected useful life? This helps determine the appropriate amortization period.
- Must the improvement be removed at lease end? Restoration requirements can create additional accounting and cash-flow considerations.
For landlord-funded improvements, review the accounting separately from the physical improvement itself. A tenant improvement allowance may affect the ROU asset even though the underlying leasehold improvement is recorded separately.
How are leasehold improvements accounted for?
Leasehold improvements that qualify as tenant assets are generally recorded within property, plant and equipment rather than as part of the ROU asset.
Understanding the distinction matters because ASC 842 governs the lease and its related ROU asset and lease liability, while tenant-owned leasehold improvements are generally accounted for separately as fixed assets.
Capitalization
Capitalize qualifying improvements when they:
- Create or enhance an asset used by the business
- Go beyond ordinary repairs and maintenance
- Provide benefits beyond the current accounting period
Routine maintenance and repairs are generally expensed as incurred.
Initial measurement
Leasehold improvements are generally recorded at cost when placed in service.
Cost may include:
- Construction costs
- Materials
- Installation
- Architecture and design fees
- Permits
- Directly attributable project costs
The asset is recorded based on its cost rather than simply at fair value.
Amortization period
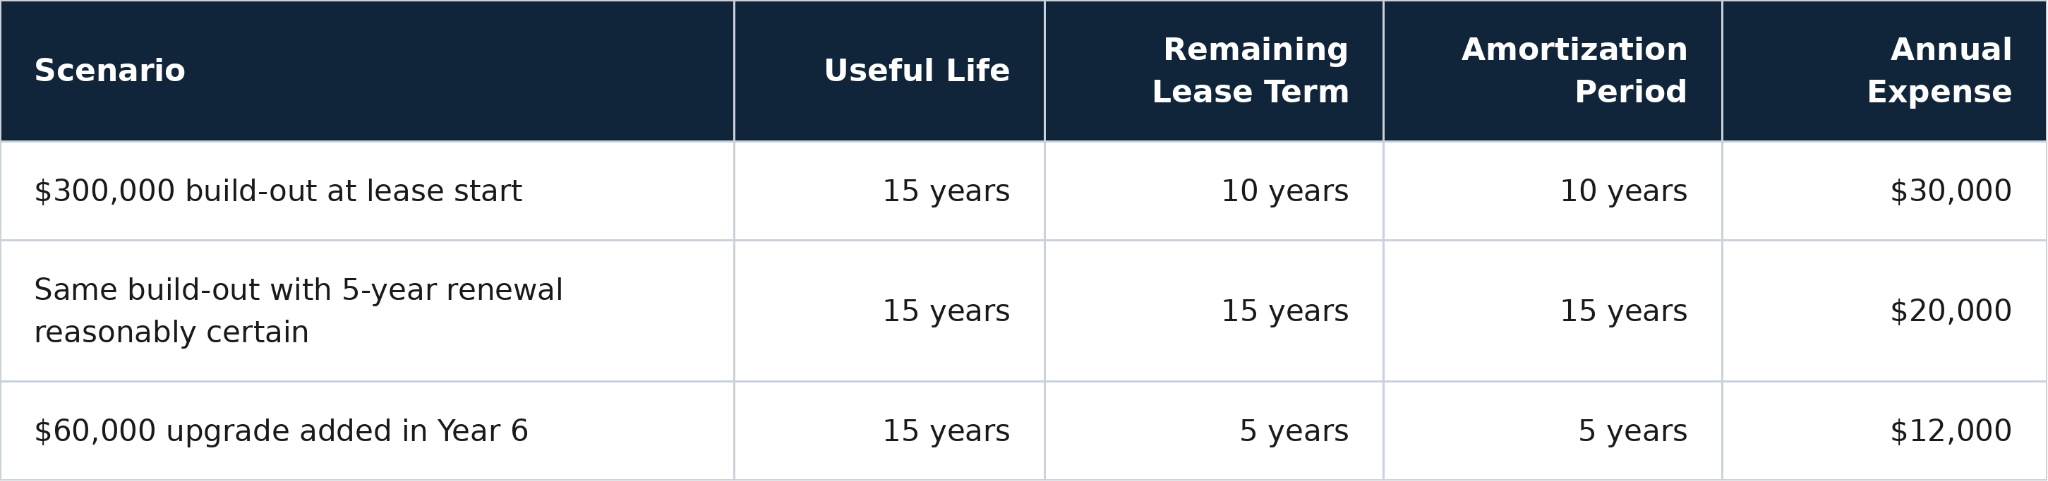
The general accounting approach is to amortize leasehold improvements over the shorter of the improvement's useful life or the remaining lease term.
For example:
- Useful life: 15 years
- Remaining lease term: 10 years
- Amortization period: 10 years
The lease term may include renewal periods when the tenant is reasonably certain to exercise the renewal option.
If circumstances change and the expected lease term changes, the amortization period may also need to be reassessed.
Exceptions
There are circumstances where the useful life rather than the shorter lease term may apply, including situations involving ownership transfer or a purchase option that the tenant is reasonably certain to exercise.
Common-control lease arrangements can also have special accounting considerations.
Changes during the lease
If the lease term changes because of a renewal, extension, early termination, or other modification, finance teams should evaluate whether the amortization period for related leasehold improvements also needs to change.
If a location closes or improvements are abandoned before they are fully amortized, the remaining carrying amount may need to be evaluated for impairment or write-off.
How do you calculate amortization expense for leasehold improvements?
The basic calculation is:
Leasehold Improvement Amortization = Cost ÷ Amortization Period
The amortization period is generally the shorter of:
- Useful life of the improvement
- Remaining lease term
Most companies use straight-line amortization.
Example
Assume a tenant spends $300,000 on a build-out.
- Useful life: 15 years
- Remaining lease term: 10 years
Because the lease term is shorter, the improvement is amortized over 10 years.
$300,000 ÷ 10 years = $30,000 annual amortization expense
If the company incorrectly used the 15-year useful life, it would record only $20,000 per year and would still have $100,000 of unamortized book value when the lease ends.
How do you record leasehold improvements in a journal entry?
When a tenant pays for a qualifying leasehold improvement, the cost is generally capitalized rather than immediately expensed.
Using the $300,000 example above:
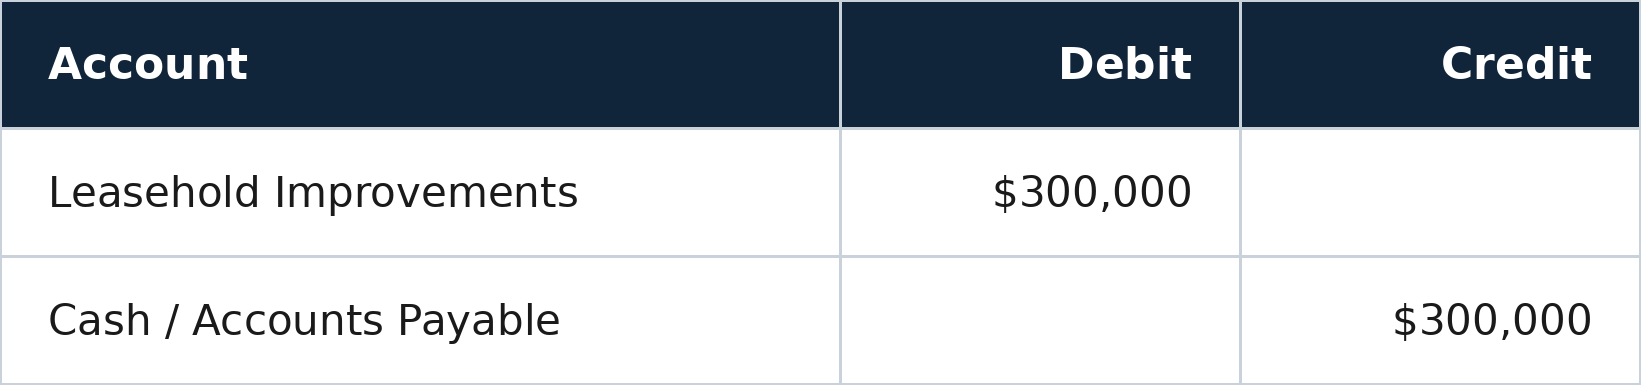
This records the improvement as a fixed asset when the qualifying costs are incurred and the asset is ready for use.
Annual amortization entry
Because the $300,000 improvement is amortized over 10 years, the annual amortization expense is $30,000.
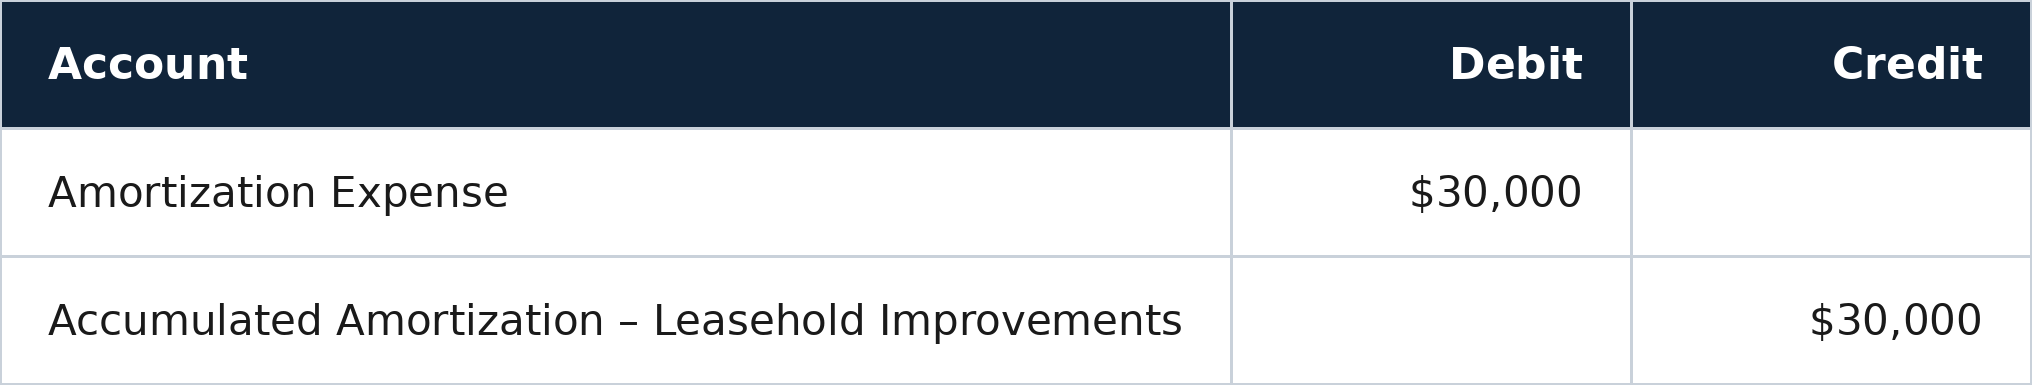
The exact account names may vary by company, but the general treatment is to recognize the cost as an asset and expense it systematically over the appropriate amortization period.
Leasehold improvements vs. tenant improvement allowance: what's the difference?
Leasehold improvements and tenant improvement allowances are related, but they are not the same thing.
Leasehold improvements are the physical improvements made to the space.
Tenant improvement allowances are amounts the landlord agrees to contribute toward the cost of those improvements.
When the improvements are tenant assets, they are generally recorded at their qualifying cost.
The landlord's allowance may be accounted for separately as a lease incentive that reduces the ROU asset under ASC 842.
Keeping these amounts separate matters because simply netting the landlord allowance against the fixed asset can misstate both the leasehold improvement balance and the lease accounting balances. Occupier's guide to tenant improvement allowance accounting explains the lease incentive treatment in more detail.
How are leasehold improvements treated for tax purposes?
Book accounting and tax accounting do not necessarily follow the same rules.
For US federal tax purposes, many interior improvements to nonresidential buildings may qualify as qualified improvement property, or QIP.
QIP generally includes qualifying improvements made to the interior portion of nonresidential real property after the building was first placed in service.
QIP generally excludes:
- Enlargement of the building
- Elevators and escalators
- Internal structural framework
15-year recovery period
Qualified improvement property generally has a 15-year recovery period under the General Depreciation System.
This differs from the longer recovery period generally associated with nonresidential real property.
Bonus depreciation
Certain qualifying QIP may also qualify for bonus depreciation depending on the property's acquisition and placed-in-service date and the tax rules in effect.
Businesses should verify current eligibility with a tax professional before making the election.
Section 179
Qualified improvement property can also be eligible for Section 179 treatment in certain circumstances.
Certain improvements to nonresidential property, including qualifying HVAC, roofing, fire protection, alarm, and security systems, may also qualify depending on the applicable tax rules.
Because book amortization and tax depreciation can follow different periods and rules, leasehold improvements frequently create book-tax differences.
Tax treatment is highly fact-specific, so businesses should confirm QIP, bonus depreciation, and Section 179 eligibility with their tax advisor.
Who owns leasehold improvements at the end of the lease?
In many commercial leases, improvements that are permanently attached to the property remain with the building when the lease ends.
The exact treatment depends on the lease's ownership, surrender, and restoration provisions.
Permanently attached improvements
Built-in walls, flooring, lighting, plumbing, and similar improvements often remain in place and may become the landlord's property at the end of the lease.
Trade fixtures
Trade fixtures are different.
Items installed specifically for the tenant's business that can be removed without materially damaging the premises may remain the tenant's property.
Examples may include:
- Specialized equipment
- Removable shelving
- Certain signage
- Business-specific fixtures
The tenant may be required to repair any damage caused during removal.
Restoration requirements
Some leases require tenants to remove improvements and return the property to its original or agreed condition.
These obligations can create significant costs at lease end, particularly when the tenant has installed extensive build-outs or specialized systems.
Review the surrender and restoration clauses well before the lease expires so the business can budget accordingly.
What happens to leasehold improvements when a lease ends early?
An early termination can shorten the period over which leasehold improvements provide economic benefit.
If the tenant knows it will leave the property before originally expected, finance teams should evaluate whether the amortization period needs to be shortened.
If the lease ends and the tenant can no longer use the improvement, any remaining carrying value may need to be written off.
The business should also review:
- Restoration requirements
- Removal costs
- Impairment indicators
- Lease modification accounting
- Remaining ROU asset and lease liability balances
The remaining lease liability and ROU asset are separate from the leasehold improvement balance. Occupier's guide to lease liabilities explains how these lease balances affect the balance sheet under ASC 842.
Real estate teams should communicate termination decisions to finance as early as possible because lease changes can affect both the lease accounting and related fixed assets.
What are the best practices for accounting for leasehold improvements?
Accurate leasehold improvement accounting depends on good records and coordination between real estate and finance teams.
- Track each project separately. Record the location, cost, placed-in-service date, useful life, and related lease.
- Separate different asset types. Keep leasehold improvements separate from furniture, IT equipment, routine repairs, and tenant improvement allowances.
- Tie amortization to the lease term. Use the shorter of useful life and remaining lease term where applicable.
- Update estimates when lease decisions change. Renewals, extensions, early exits, and partial terminations may affect amortization.
- Watch for impairment indicators. Location closures and poor performance may require additional review.
- Track restoration obligations. Know what needs to be removed or restored when the lease ends.
- Review schedules regularly. Compare fixed asset records with the active lease portfolio so both teams are working from the same information.
Maintaining this connection between the fixed asset records and the underlying leases is also part of effective lease management.
What do real estate and finance teams need to know about leasehold improvements?
Leasehold improvements affect the balance sheet, income statement, cash planning, and tax reporting.
The most important accounting principle is that qualifying improvements should generally be capitalized and amortized over the shorter of their useful life or the applicable remaining lease term.
Real estate decisions can also change the accounting. Renewing, extending, partially terminating, or exiting a lease can affect the amortization period and the amount ultimately written off.
Occupier's lease accounting software helps real estate and finance teams keep lease terms, critical dates, amendments, and ASC 842 information aligned so accounting teams can respond when lease decisions change.
Request a demo to see how Occupier can help real estate and finance teams manage lease data throughout the lease lifecycle.
Frequently Asked Questions
What are leasehold improvements?
Leasehold improvements are changes made to leased property to make the space suitable for the tenant's operations. Examples include interior build-outs, flooring, lighting, walls, and certain electrical or plumbing upgrades.
Are leasehold improvements depreciated or amortized?
Leasehold improvements are commonly described as being amortized over their accounting life, although they are fixed assets and the expense functions similarly to depreciation. Companies should follow their accounting policies and applicable guidance when naming and presenting the expense.
What is the useful life of leasehold improvements?
For book accounting, qualifying leasehold improvements are generally amortized over the shorter of their useful life or the remaining lease term, subject to applicable exceptions. For US tax purposes, qualifying QIP generally has a 15-year recovery period.
Are leasehold improvements part of the ROU asset?
Generally, no. Tenant-owned leasehold improvements are recorded separately as property, plant and equipment. A landlord-funded tenant improvement allowance may affect the ROU asset, but the physical improvement itself is accounted for separately when it is the tenant's asset.
What is the journal entry for leasehold improvements?
When a tenant pays for a qualifying improvement, it generally debits Leasehold Improvements and credits Cash or Accounts Payable. Amortization is then recorded periodically by debiting Amortization Expense and crediting Accumulated Amortization.
What happens to leasehold improvements if a lease ends early?
The company should reassess the remaining useful period. If the tenant leaves the space and no longer benefits from the improvement, any remaining carrying value may need to be accelerated, impaired, or written off depending on the circumstances.
Can a tenant take leasehold improvements when they leave?
Permanently attached improvements often remain with the property, depending on the lease. Removable trade fixtures may remain the tenant's property, although the tenant may be required to repair damage caused by their removal.
Are leasehold improvements eligible for bonus depreciation?
Certain leasehold improvements that qualify as QIP may be eligible for bonus depreciation depending on current federal tax rules, acquisition date, placed-in-service date, and other eligibility requirements. Businesses should confirm the treatment with their tax advisor.
Lease management that works for real estate and finance
15,000 sq ft
90 days notice
March 2026
Action required