IFRS 16 Lease Accounting: Guide, Example & Journal Entries
IFRS 16 is a new standard for lease accounting issued by the International Financial Reporting Standards (IFRS) foundation along with its International Accounting Standards Board (IASB). The goal of IFRS 16 is to offer a comprehensive model for lesse
IFRS 16 lease accounting requires organizations reporting under International Financial Reporting Standards to recognize most leases as right-of-use (ROU) assets and lease liabilities. Lessees generally record depreciation on the ROU asset and interest on the outstanding liability throughout the lease term.
The standard replaced IAS 17 and became effective for annual reporting periods beginning on or after January 1, 2019. It introduced a largely single-model approach to lessee accounting, bringing many lease obligations that were previously disclosed off the balance sheet into recognized assets and liabilities.
For businesses managing commercial properties, equipment, or international lease portfolios, applying IFRS 16 requires careful attention to payment schedules, discount rates, contractual options, and subsequent changes.
This guide explains the accounting process with a worked lease example, journal entries, recognition exemptions, and the reporting considerations finance teams need to understand.
What Is IFRS 16 Lease Accounting?
IFRS 16 is the international accounting standard governing how organizations recognize, measure, present, and disclose lease arrangements.
Issued by the International Accounting Standards Board (IASB), the standard aims to provide financial statement users with a clearer understanding of an organization's rights to use leased assets and its obligations to make payments.
Before IFRS 16, lessees generally classified leases as operating or finance leases under IAS 17. Many operating leases did not result in recognized lease assets and liabilities.
IFRS 16 changed this approach by introducing a largely single accounting model for lessees.
For example, a retail company entering a five-year lease for a storefront generally recognizes an ROU asset representing its right to occupy the property and a liability associated with qualifying future rental payments.
The standard applies to qualifying leases within its scope, including commercial property, vehicles, equipment, and other underlying assets.
However, IFRS 16 does not require every lease to be recognized on the balance sheet. Certain short-term leases and leases of low-value assets may qualify for recognition exemptions.
How to Identify a Lease Under IFRS 16
Before calculating an asset or liability, the organization must establish whether the contract contains a lease.
Under IFRS 16, a contract contains a lease when it conveys the right to control the use of an identified asset for a period of time in exchange for consideration.
Two elements are central to this assessment.
First, the customer must have the right to obtain substantially all the economic benefits from using the identified asset.
Second, the customer must have the right to direct how and for what purpose the asset is used, subject to the applicable decision-making criteria.
For example, a company leasing a specified warehouse and deciding how the space is used may control the underlying asset.
A company purchasing general warehousing services may not have that same control if the supplier determines which facilities are used and how the services are delivered.
The contract's title does not determine the accounting treatment. A service agreement may contain an embedded lease when the underlying conditions are satisfied.
Determining the Lease Term
The accounting lease term is not always limited to the initial non-cancellable period stated in the contract.
It may also include extension periods the lessee is reasonably certain to exercise and periods covered by termination options the lessee is reasonably certain not to exercise.
Consider a business entering a five-year office lease with an additional three-year renewal option.
If the business is reasonably certain to exercise the renewal option, the accounting lease term generally includes the additional three years.
Relocation costs, significant leasehold improvements, operational dependencies, and other economic incentives may influence the assessment.
Correctly determining the lease term is essential because it affects the measurement of the liability and the period over which the ROU asset is depreciated.
Measuring the Initial Lease Liability
The initial lease liability represents the present value of qualifying lease payments that remain unpaid at the commencement date.
The calculation uses the interest rate implicit in the lease when that rate is readily determinable. Otherwise, the lessee uses its incremental borrowing rate.
The payments included in the measurement depend on the contractual terms.
Common components include fixed payments, in-substance fixed payments, certain variable payments linked to an index or rate, and other qualifying amounts such as expected payments under residual value guarantees.
Not every variable payment is included.
For example, percentage rent calculated solely from future store sales is generally excluded from the initial lease liability unless it is in-substance fixed.
Such payments are ordinarily recognized in the period when the event or activity triggering them occurs.
Separating Lease and Service Components
Some commercial agreements combine the right to use an asset with additional services.
An office lease might include building maintenance, cleaning, or security services.
IFRS 16 generally requires lessees to separate lease and non-lease components and allocate consideration appropriately.
However, a practical expedient permits lessees to elect, by class of underlying asset, not to separate non-lease components from associated lease components.
That election can increase the amounts included in the recognized lease liability because services may be accounted for together with the lease.
Organizations should establish an appropriate accounting policy and apply it consistently to the relevant asset class.
How to Calculate the Right-of-Use Asset
The ROU asset represents the lessee's right to use the underlying asset during the lease term.
Its initial carrying amount generally starts with the initial lease liability and includes adjustments for payments made at or before commencement, qualifying initial direct costs, lease incentives, and relevant restoration obligations.
A simplified calculation is:
Initial ROU Asset = Initial Lease Liability + Prepayments + Initial Direct Costs + Restoration Costs − Lease Incentives Received
Not every arrangement contains all these components.
For example, an office tenant may make an advance rental payment before commencement or agree to restore the premises when the lease ends.
These terms can cause the initial ROU asset to differ from the lease liability.
Under the cost model, the ROU asset is subsequently reduced through depreciation and impairment and adjusted for relevant lease remeasurements.
The depreciation period generally depends on the lease term, the underlying asset's useful life, and whether ownership transfers or a purchase option is reasonably certain to be exercised.
IFRS 16 Lease Accounting Example
Consider a company entering a three-year lease for equipment used in its operations.
The agreement has the following terms:
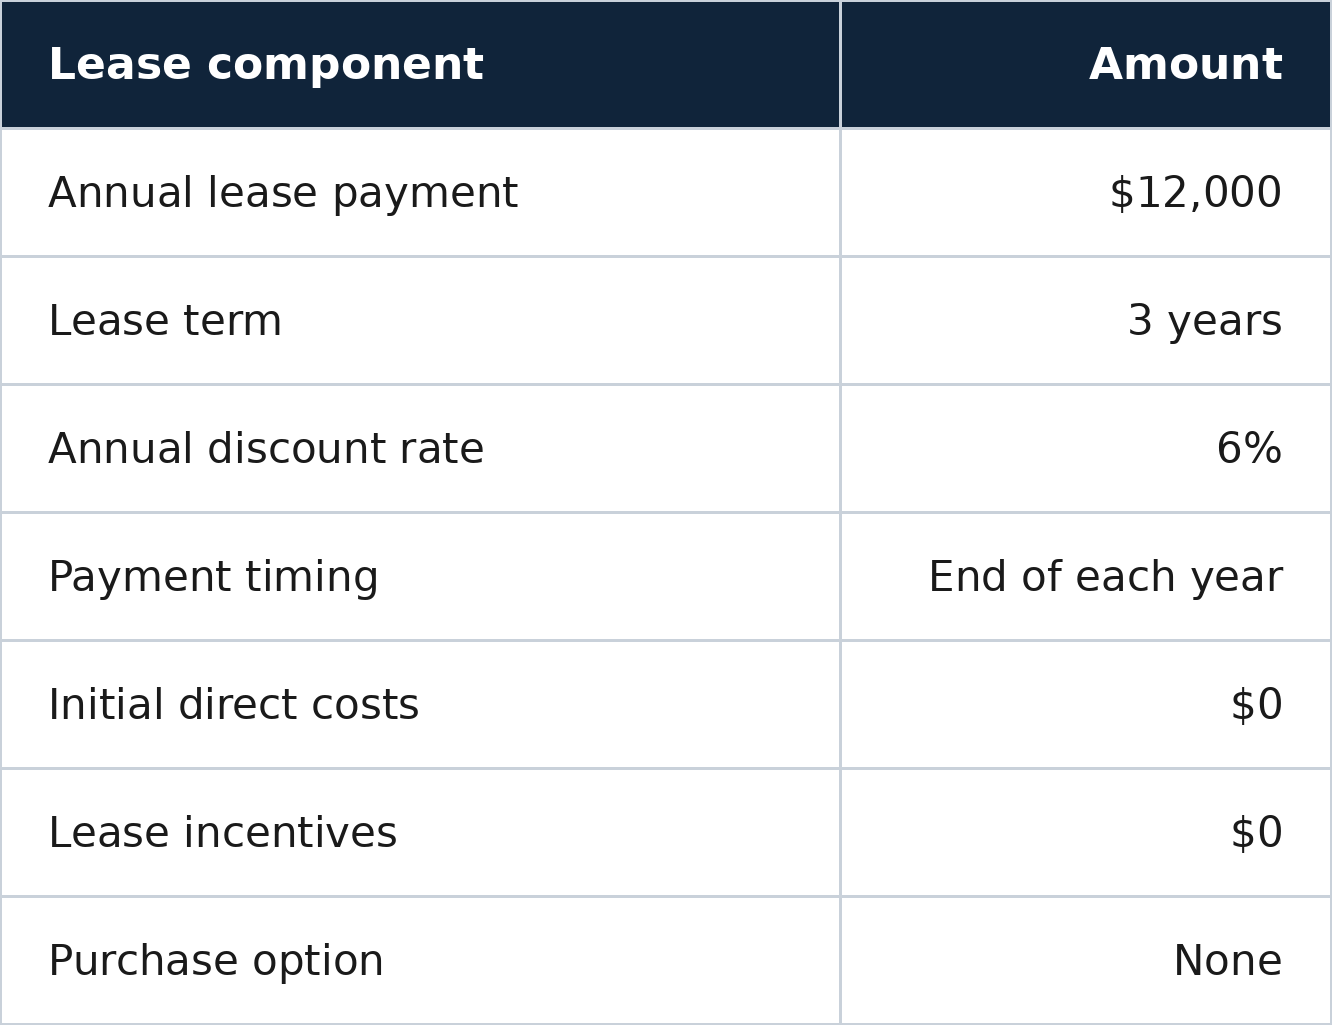
Assume the company has no prepaid amounts, restoration obligations, impairment charges, or lease modifications.
Step 1: Calculate the Initial Liability
The company calculates the present value of three annual payments using a 6% discount rate.
For equal payments made at the end of each period:
Present Value = Payment × [1 − (1 + r)^−n] ÷ r
Where:
- Payment = $12,000
- r = 0.06
- n = 3
The calculation is:
$12,000 × [1 − (1.06)^−3] ÷ 0.06
Initial lease liability = $32,076.14
Because the company has no prepayments, initial direct costs, incentives, or restoration obligations, the initial ROU asset is also $32,076.14.
Step 2: Calculate the First Year's Interest
Interest expense is calculated using the outstanding liability and annual discount rate.
$32,076.14 × 6% = $1,924.57
At the end of the first year, the company makes a $12,000 lease payment.
The portion reducing the liability is:
$12,000 − $1,924.57 = $10,075.43
The closing lease liability becomes:
$32,076.14 − $10,075.43 = $22,000.71
The same principle applies in subsequent periods, using the applicable outstanding liability.
Step 3: Calculate ROU Asset Depreciation
Assume the equipment's useful life exceeds the three-year lease term, ownership does not transfer, and there is no purchase option.
The company depreciates the ROU asset over the lease term using a straight-line method.
$32,076.14 ÷ 3 = $10,692.05 annually
The first year's combined lease-related expense is:
$1,924.57 interest + $10,692.05 depreciation = $12,616.62
The recognized expense differs from the $12,000 annual payment because depreciation and interest are calculated separately.
IFRS 16 Lease Liability Amortization Schedule
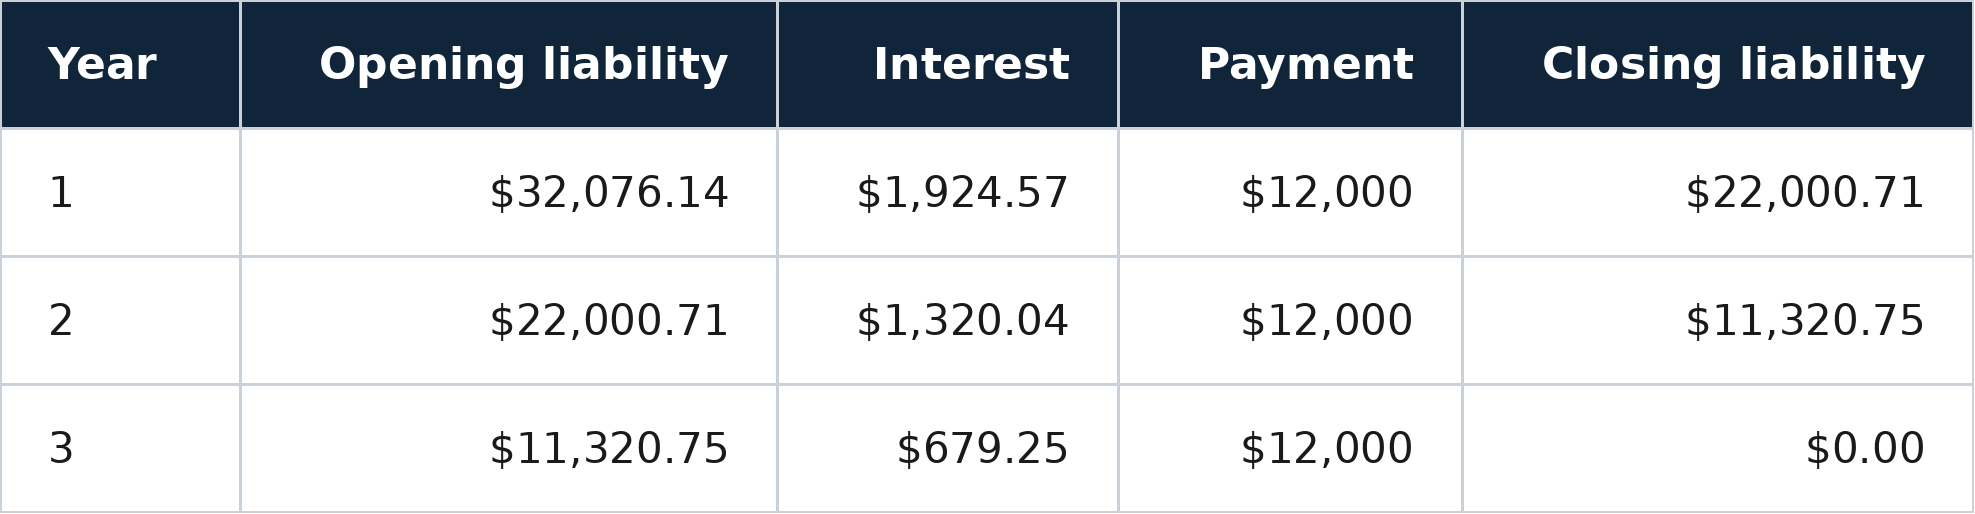
Amounts are rounded to two decimal places. The closing balance reaches zero using unrounded calculations.
This schedule shows how interest expense declines as the outstanding lease liability decreases.
The ROU asset follows a separate depreciation schedule, meaning the asset and liability balances will generally differ after commencement.
For businesses that need to understand the broader relationship between lease recognition, reporting, and accounting schedules, Occupier's lease accounting overview provides additional context.
IFRS 16 Journal Entries for the Worked Example
Using the three-year equipment lease, the company records separate transactions for initial recognition, interest, payments, and depreciation.
Initial Recognition at Commencement
At the commencement date:
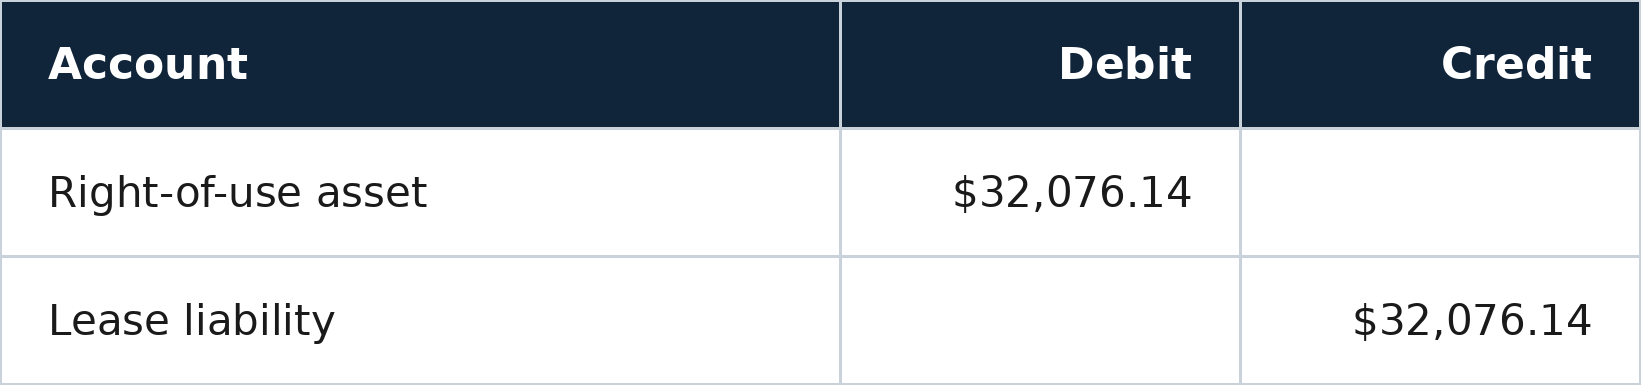
The entry recognizes the right to use the equipment and the obligation associated with the qualifying unpaid lease payments.
First-Year Interest Expense
At the end of year one, before the payment:
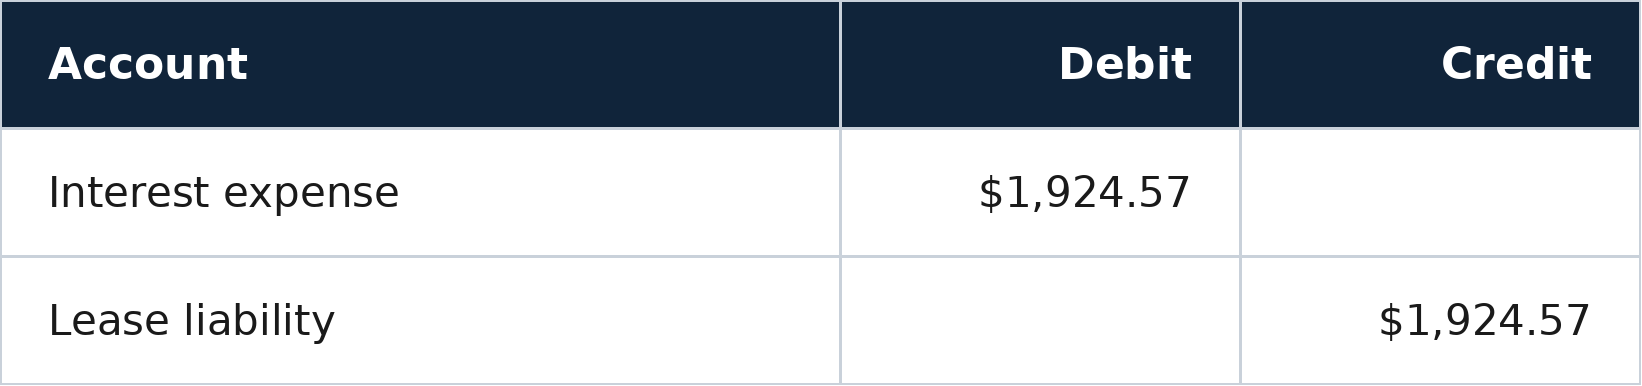
The liability increases through interest accretion during the period.
First Annual Payment
When the company pays $12,000:
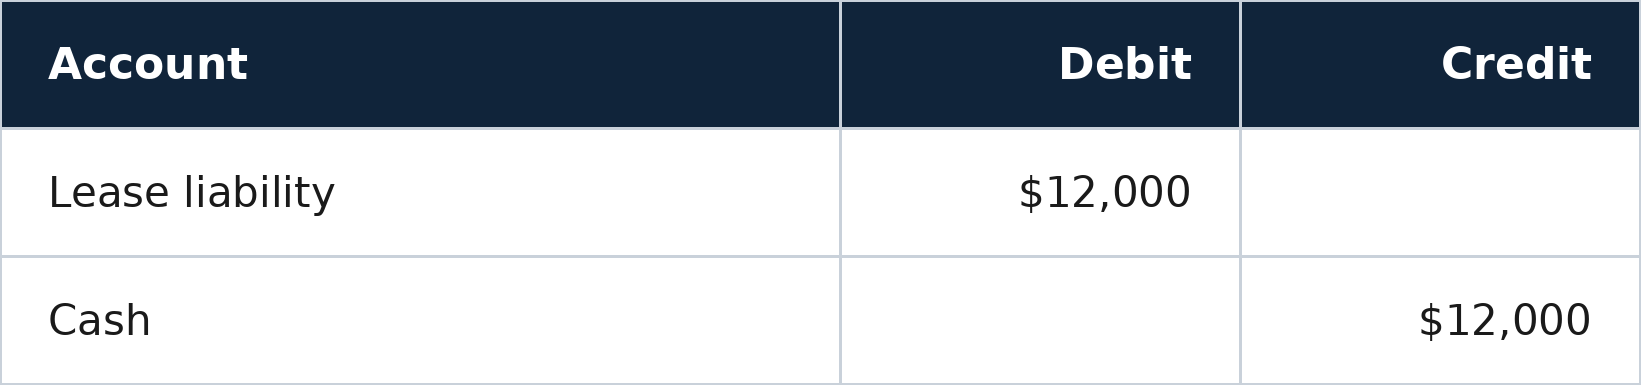
The remaining lease liability is $22,000.71.
First-Year ROU Asset Depreciation
The company separately records the consumption of its right to use the equipment.
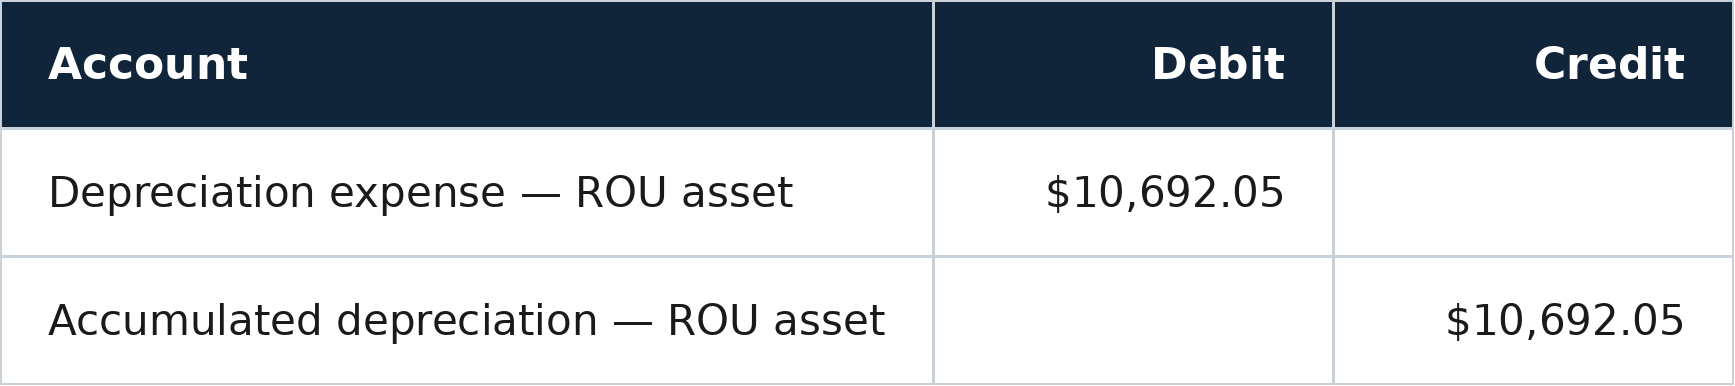
The process continues throughout the lease term using the appropriate interest and depreciation calculations.
More complex agreements may also require entries for lease modifications, remeasurements, impairments, variable payments, or other contractual changes.
Which Leases Qualify for IFRS 16 Recognition Exemptions?
IFRS 16 provides two recognition exemptions designed to reduce the accounting burden for qualifying arrangements.
These exemptions are optional accounting policy elections, not automatic exclusions from the standard.
Short-Term Lease Exemption
A short-term lease has a lease term of 12 months or less at commencement and does not contain a purchase option.
When the lessee elects the exemption, it generally recognizes the related payments as expenses instead of recording an ROU asset and lease liability.
For example, a business renting temporary office space for nine months may qualify if the relevant conditions are met.
However, a lease with a nine-month initial term and an extension option must be assessed using the accounting lease term, not simply the original contracted period.
The short-term lease election is made by class of underlying asset.
If a lease modification or change in the lease term causes the arrangement to be treated as a new lease for these purposes, the exemption must be reassessed.
Low-Value Asset Exemption
IFRS 16 also permits an exemption for leases of qualifying low-value underlying assets.
Examples may include certain tablets, personal computers, small office furniture, and telephones.
The assessment considers the value of the underlying asset when new, regardless of the age of the particular item being leased.
The IASB referred to assets valued in the order of US$5,000 or less when developing the exemption. However, IFRS 16 does not establish a mandatory universal $5,000 threshold.
The asset must also satisfy the relevant independence and dependency conditions.
For example, a vehicle would not ordinarily qualify merely because it has depreciated substantially in value.
The exemption is not available for a head lease when the lessee subleases or expects to sublease the underlying asset.
Unlike the short-term election, the low-value exemption may be applied on a lease-by-lease basis.
When an exemption is elected, qualifying payments are generally expensed over the lease term using a straight-line or other appropriate systematic method.
When Does IFRS 16 Require Lease Remeasurement?
Initial lease measurements are not necessarily fixed for the entire contract.
Changes in contractual rights, payment obligations, or relevant assessments may require a lessee to remeasure its lease liability.
However, the accounting treatment depends on the nature of the change.
Changes in Lease Term or Purchase Options
A reassessment of the lease term may be required when a significant event or change in circumstances within the lessee's control affects whether it is reasonably certain to exercise an extension or termination option.
Similarly, changes in the assessment of a purchase option may require remeasurement.
For these events, the lessee generally uses a revised discount rate.
For example, if a company becomes reasonably certain to extend an existing property lease following a significant operational decision, its accounting lease term may need to be reassessed.
Changes in Index-Linked Payments
Some commercial leases include rental increases linked to an inflation index or another specified rate.
Payments based on an index or rate are initially measured using the index or rate applicable at commencement.
When the contractual cash flows change because of an index or rate adjustment, the lease liability may require remeasurement.
The original discount rate is generally retained for these changes, except where the relevant requirements specify otherwise, such as certain floating interest rate changes.
Lease Modifications
A lease modification changes the scope or consideration of the agreement beyond the original contract terms.
Examples include adding premises, reducing leased space, or negotiating a new payment arrangement.
Depending on the circumstances, the modification may be accounted for as a separate lease or through remeasurement of the existing lease.
The effect on the ROU asset and any resulting gain or loss depends on the nature of the modification.
Finance teams should retain executed amendments, document their conclusions, and update accounting schedules when required.
How Are Foreign Currency Leases Treated?
International businesses may enter leases denominated in currencies other than their functional currency.
These arrangements introduce an additional reporting consideration because the lease liability and ROU asset may be treated differently under the relevant foreign currency requirements.
A lease liability denominated in a foreign currency is generally a monetary liability under IAS 21.
It is retranslated using the applicable closing exchange rate, with exchange differences normally recognized in profit or loss unless another specific requirement applies.
An ROU asset measured under the historical cost model is generally a non-monetary asset and is not retranslated in the same way.
For example, a company with a euro functional currency may lease equipment with payments denominated in U.S. dollars.
Exchange rate movements can change the euro carrying amount of the liability even when the contractual dollar payments remain unchanged.
Organizations should maintain consistent exchange-rate records and reconcile the resulting movements.
Occupier's guide to foreign exchange lease accounting provides a more detailed discussion of currency-related lease reporting.
What Should IFRS 16 Financial Statements Disclose?
IFRS 16 establishes presentation and disclosure requirements intended to help users understand lease activity, financial commitments, and associated cash flows.
On the statement of financial position, lessees must present or disclose ROU assets and lease liabilities according to the applicable requirements.
In profit or loss, interest expense and depreciation are generally recognized separately under the main lessee accounting model.
The statement of cash flows generally presents the principal portion of lease liability payments as financing activities. Interest payments are presented according to the applicable IAS 7 requirements and accounting policies.
Companies must also consider disclosures relating to lease costs, additions to ROU assets, short-term and low-value lease expenses, variable payments, and maturity information.
The specific disclosures depend on the organization's lease activities and applicable materiality considerations.
Using Roll Forward Reports to Support Disclosures
Finance teams often use reconciliations to explain changes in ROU assets and lease liabilities between reporting periods.
These reports can help distinguish additions, payments, depreciation, interest, modifications, and other movements.
A lease roll forward report can support the reconciliation of accounting schedules with the general ledger and help accountants prepare supporting information for reporting reviews.
However, IFRS 16 does not require every lessee to publish one particular standalone roll forward report format.
How Is IFRS 16 Different From ASC 842?
Both IFRS 16 and ASC 842 generally require lessees to recognize most leases on the balance sheet.
The main difference is their subsequent accounting model.
IFRS 16 generally follows a single lessee accounting model that recognizes depreciation and interest separately.
ASC 842 retains separate operating and finance lease classifications, resulting in different expense recognition and presentation.
The standards also differ in certain exemptions, reassessment requirements, and other measurement details.
For multinational businesses reporting under both international and U.S. accounting frameworks, these differences can affect financial reporting processes and reconciliation requirements.
Occupier's dedicated comparison of IFRS 16 vs. ASC 842 explains those differences in greater detail.
Maintaining IFRS 16 Accuracy Across a Lease Portfolio
Applying IFRS 16 consistently becomes more challenging when organizations manage numerous properties, equipment agreements, currencies, and legal entities.
Each lease may have a different commencement date, payment structure, discount rate, or contractual option.
Finance teams also need timely information about amendments, rent changes, and new agreements negotiated by other departments.
An effective process should centralize lease information, document important assumptions, and establish clear responsibilities for recording changes.
Regular reconciliation of lease liabilities, ROU assets, and related accounting entries helps identify discrepancies before financial statements are finalized.
For businesses managing larger portfolios, lease accounting software can help organize lease information and support accounting schedules, calculations, and financial reporting.
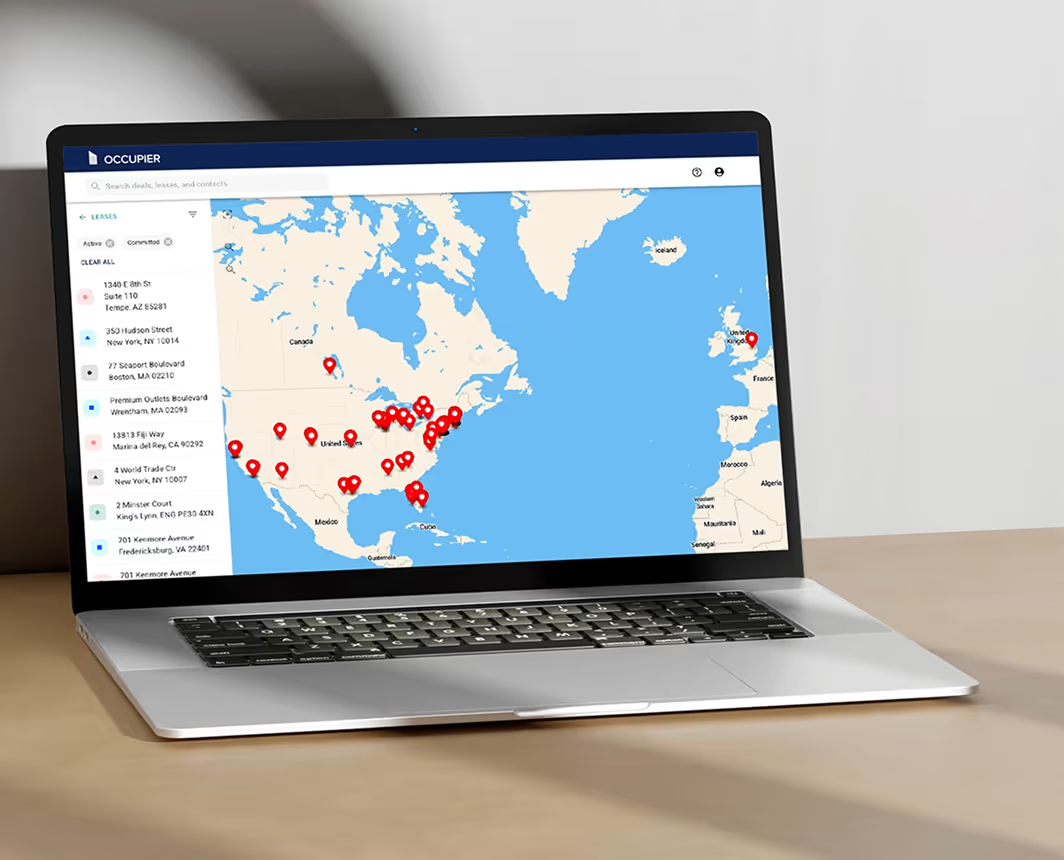
Occupier connects lease records with accounting workflows, allowing real estate and finance teams to work from more consistent information across commercial locations.
Organizations should confirm that any system they evaluate supports their required IFRS 16 calculations, disclosures, currencies, and reporting integrations.
Frequently Asked Questions About IFRS 16
Is IFRS 16 still applicable in 2026?
Yes. IFRS 16 remains the international accounting standard for leases. It became effective for annual reporting periods beginning on or after January 1, 2019, and continues to apply, subject to relevant amendments.
Does IFRS 16 require all leases to appear on the balance sheet?
No. Most qualifying leases are recognized as ROU assets and lease liabilities, but eligible short-term leases and leases of low-value assets may qualify for recognition exemptions when the appropriate elections are made.
How is the IFRS 16 lease liability calculated?
The initial lease liability is calculated using the present value of qualifying lease payments remaining unpaid at commencement. The discount rate, payment timing, and lease term all influence the result.
What is the difference between an ROU asset and a lease liability?
An ROU asset represents the lessee's right to use an underlying asset. A lease liability represents the obligation to make qualifying future lease payments. Their initial values may differ, and their balances generally change differently over time.
Is depreciation required under IFRS 16?
Under the main lessee accounting model, ROU assets are generally depreciated over the appropriate period. The depreciation method and period depend on the asset and relevant contractual terms.
Are variable lease payments included in the IFRS 16 liability?
Certain variable payments, including those dependent on an index or rate, are included in the initial measurement. Payments based solely on future sales or usage are generally excluded unless they are in-substance fixed.
Do IFRS 16 leases require separate interest and depreciation entries?
Under the standard's main lessee accounting model, interest expense on the lease liability and depreciation of the ROU asset are generally recognized separately. Different treatment applies when a qualifying recognition exemption is elected.
Lease management that works for real estate and finance
15,000 sq ft
90 days notice
March 2026
Action required