Lease Assets and Liabilities: How They Work
What is the difference between a lease asset and a lease liability?
A lease asset represents the lessee's right to use an underlying asset during the lease term. A lease liability represents the obligation to make qualifying future payments. Both generally arise from the same lease agreement but are measured and adjusted according to different requirements.
Lease assets and liabilities represent two sides of a company's lease agreement. The lease asset reflects the right to use a property or piece of equipment, while the lease liability represents the obligation to make qualifying future payments.
Under ASC 842, businesses generally recognize both amounts on the balance sheet when a qualifying lease commences. This applies to most operating and finance leases, making the financial commitments associated with leased properties and equipment more visible.
For commercial tenants managing offices, retail stores, warehouses, or equipment, understanding these balances is essential for accurate accounting and financial reporting.
Although lease assets and liabilities are closely related, they are not interchangeable. Their balances can change differently throughout the lease term, and certain contractual events affect one without affecting the other.
This guide explains what lease assets and liabilities are, how they are calculated, and how they affect financial statements.
What Are Assets in Lease Accounting?
In general accounting, an asset is an economic resource controlled by an organization as a result of past events.
Assets can include cash, inventory, equipment, buildings, and contractual rights that provide economic benefits.
When a company leases property or equipment, it does not necessarily own the underlying asset. Instead, it obtains a contractual right to use that asset for a specified period.
Under ASC 842, this right is generally recognized as a right-of-use (ROU) asset.
For example, a retailer entering a five-year lease for a storefront does not record ownership of the building simply because it occupies the premises.
Instead, the retailer recognizes an ROU asset representing its right to use the property during the accounting lease term.
The asset provides economic benefits because the company can use the premises to operate its business.
Tangible Assets vs. Right-of-Use Assets
Tangible assets are physical resources such as buildings, vehicles, machinery, and equipment.
A lease may involve a tangible underlying asset, but the lessee's ROU asset represents its contractual right to use that resource.
This distinction matters because the accounting treatment of an owned building differs from the accounting treatment of a leased building.
For example, a company purchasing a warehouse generally records the purchased property under the applicable property, plant, and equipment guidance.
A company leasing the same warehouse generally records an ROU asset and lease liability under ASC 842.
Although a right-of-use asset represents a contractual right, it is presented under the lease accounting requirements rather than automatically grouped with ordinary intangible assets.
For detailed ROU asset measurement and journal entries, see Occupier's ROU asset guide.
What Are Liabilities in Lease Accounting?
A liability represents a present obligation arising from past events that requires an organization to transfer economic resources.
In lease accounting, the lease liability reflects the obligation to make qualifying payments associated with a lease agreement.
Under ASC 842, the initial liability is generally measured using the present value of lease payments that remain unpaid at commencement.
This is different from simply adding together every payment listed in the agreement.
For example, a tenant might agree to pay $20,000 annually for five years.
The undiscounted payments total $100,000, but the initial lease liability will generally be lower because qualifying future payments are discounted to their present value.
The amount depends on payment timing, the accounting lease term, the discount rate, and which payments must be included.
What Is Included in a Lease Liability?
Qualifying payments can include fixed payments, in-substance fixed payments, certain variable amounts based on an index or rate, and other amounts specified under the applicable standard.
Not every payment appearing in a commercial lease is automatically included.
For example, variable percentage rent based on a retailer's future sales is generally excluded from the initial liability unless it is in-substance fixed.
Similarly, certain maintenance or service charges may be accounted for separately, depending on the lease terms and relevant accounting policy elections.
Understanding which payments belong in the liability helps companies avoid overstating or understating their financial obligations.
Lease Assets vs. Lease Liabilities: Key Differences
Lease assets and liabilities originate from the same agreement but represent different financial elements.
The asset reflects an economic right, while the liability reflects a contractual payment obligation.
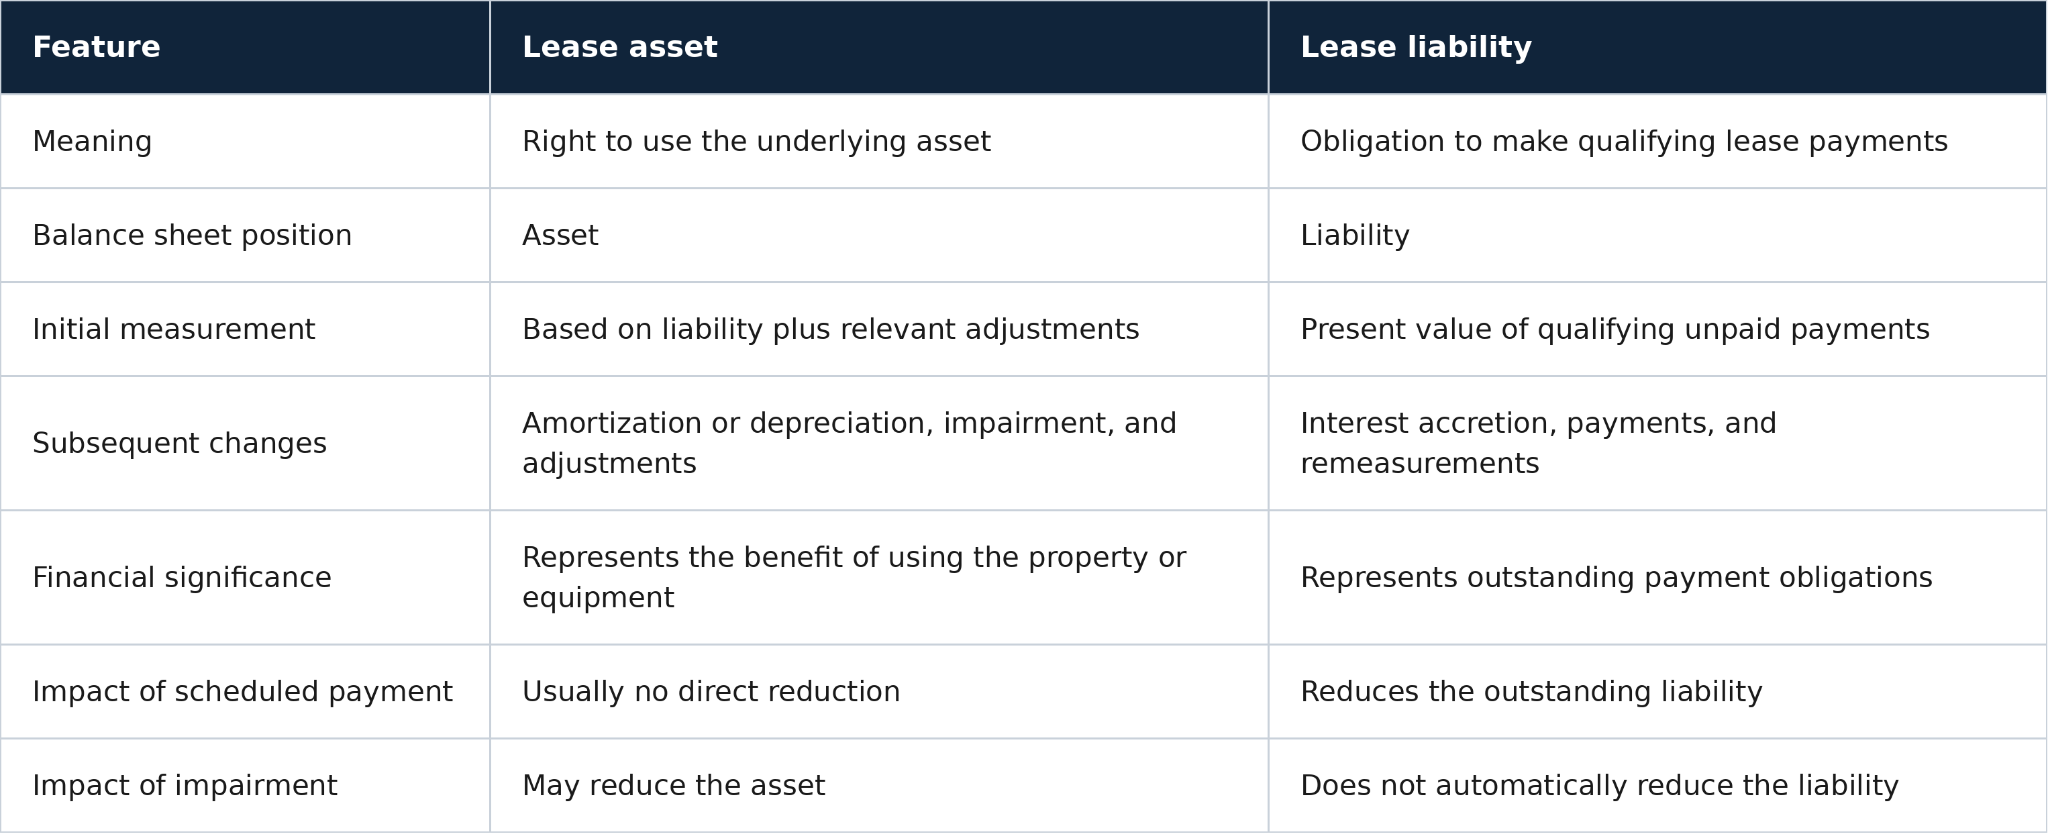
One important distinction is that the balances are not required to remain equal throughout the agreement.
A lease liability generally decreases through payments and increases through interest accretion.
The related ROU asset follows the subsequent measurement rules for the lease's classification and applicable accounting standard.
Why Are Lease Assets and Liabilities Recorded Together?
Recognizing both balances reflects the rights and obligations created by a lease.
Under the previous U.S. lease accounting standard, ASC 840, operating lease arrangements generally did not result in recognition of the full right-to-use asset and corresponding obligation.
ASC 842 changed this approach.
Most qualifying operating and finance leases now appear on the lessee's balance sheet.
Consider a business signing a long-term office lease.
The business receives the economic benefit of using the office, but it also assumes an obligation to make payments during the lease term.
Recording only rental expenses would not fully present those rights and obligations on the balance sheet.
Recognizing the ROU asset and lease liability provides financial statement users with a clearer picture of the company's leasing commitments.
The two balances are initially connected, but their subsequent accounting depends on the lease classification and relevant contractual events.
How Are Initial Lease Assets and Liabilities Calculated?
The first step is determining the lease liability at commencement.
For a typical qualifying lease, the liability is measured using the present value of unpaid lease payments included under ASC 842.
The ROU asset begins with the initial liability and is adjusted for relevant amounts.
A simplified formula is:
Initial ROU Asset = Initial Lease Liability + Qualifying Prepayments + Initial Direct Costs − Lease Incentives Received
Other required adjustments may apply depending on the agreement.
For example, a tenant might pay rent before commencement or receive an incentive from the landlord.
These amounts can cause the initial asset and liability to differ.
Lease Asset and Liability Calculation Example
Suppose a business enters a three-year equipment lease with the following terms:
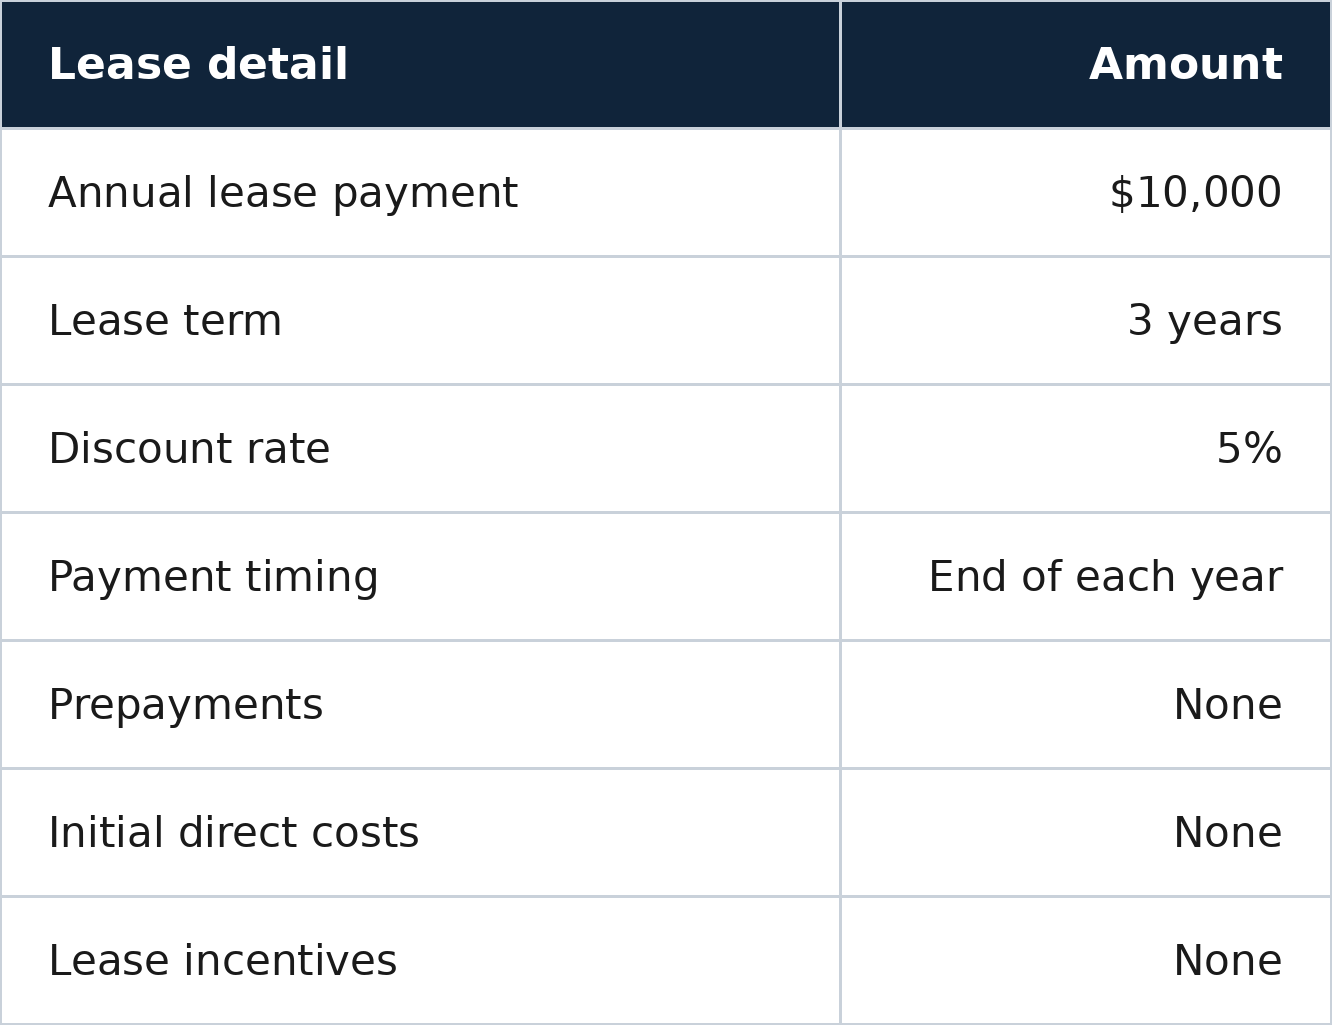
The initial lease liability is calculated using the present value of three annual payments:
Present Value = Payment × [1 − (1 + r)^−n] ÷ r
Using a $10,000 payment, 5% discount rate, and three-year term:
Initial lease liability = $27,232.48
Because there are no prepayments, incentives, or other adjustments in this example:
Initial ROU asset = $27,232.48
The business recognizes both amounts when the lease commences.
How Do Lease Assets and Liabilities Appear on the Balance Sheet?
Under ASC 842, operating and finance lease ROU assets and liabilities are presented or disclosed separately from one another and from other assets and liabilities, as required by the standard.
The initial recognition entry for the example is:
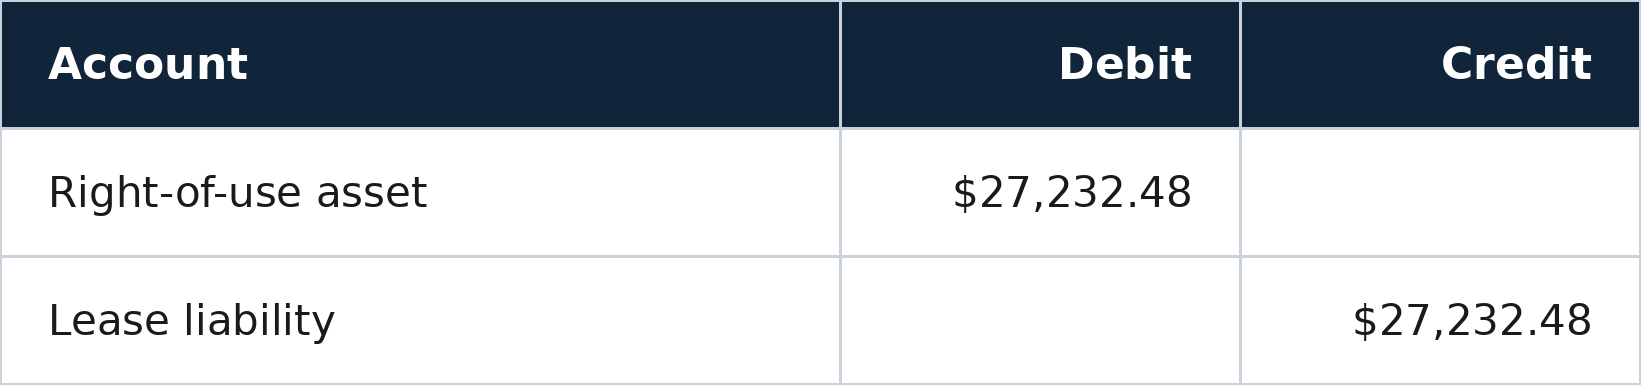
The journal entry increases total reported assets and liabilities by equal amounts under these simplified assumptions.
It does not create immediate revenue or expense merely because the lease has commenced.
The classification of the agreement determines how subsequent lease costs are recognized.
Current vs. Noncurrent Lease Liabilities
Lease liabilities are generally separated into current and noncurrent portions under applicable balance sheet presentation requirements.
The current portion represents the amount expected to be settled within the next reporting year or normal operating cycle, as applicable.
The noncurrent portion reflects obligations expected to be settled later.
For example, a business may have a total lease liability of $500,000, with $85,000 classified as current and $415,000 as noncurrent.
The ROU asset is generally presented as a noncurrent asset rather than divided into matching current and noncurrent portions.
This means the current liability cannot simply be calculated by dividing the total ROU asset into annual amounts.
Why Do Lease Asset and Liability Balances Change Differently?
After commencement, scheduled payments reduce the lease liability while interest accrues on the outstanding balance.
The ROU asset is accounted for separately according to the lease classification.
Using the previous three-year example, the first year's interest is:
$27,232.48 × 5% = $1,361.62
After the annual $10,000 payment, the liability becomes:
$27,232.48 + $1,361.62 − $10,000 = $18,594.10
The payment reduces the liability, but it does not directly reduce the ROU asset by the same amount.
For an ASC 842 finance lease, the ROU asset is generally amortized separately from the recognition of interest expense.
For an operating lease, a single lease cost is generally recognized, and the ROU asset reduction is determined through the operating lease accounting model.
Consequently, the asset and liability balances often differ after the first reporting period.
The accounting is also affected by modifications, impairments, and other changes during the lease term.
How Do Lease Modifications Affect Assets and Liabilities?
Commercial lease agreements often change before their scheduled expiration.
A tenant may extend the term, add space, reduce its occupied area, or negotiate different rental payments.
Certain changes require remeasurement of the lease liability and a corresponding adjustment to the ROU asset.
For example, a retailer may extend an existing lease for another three years.
If the change meets the relevant remeasurement requirements, the accounting team must reassess the qualifying payments and applicable discount rate.
The resulting change may increase the lease liability and ROU asset.
However, not every contractual change is treated identically.
A partial termination may require a reduction in the ROU asset and recognition of a gain or loss.
Finance teams should evaluate the specific event and document its accounting treatment rather than automatically applying the same adjustment to both balances.
What Happens When a Lease Asset Is Impaired?
An ROU asset may be subject to impairment when relevant circumstances indicate that its carrying amount may not be recoverable.
For example, a retailer might decide to close an underperforming location while remaining responsible for several years of rental payments.
The decision could create an impairment indicator for the related asset.
Under U.S. GAAP, applicable impairment requirements must be considered when evaluating the ROU asset.
An impairment charge may reduce the carrying amount of the asset.
However, reducing the ROU asset does not automatically eliminate the lease liability.
The contractual obligation to pay rent may continue even when the property is no longer being used for business operations.
This is an important distinction for companies planning closures, relocations, or restructuring activities.
How Do Lease Assets and Liabilities Affect Financial Ratios?
Recognizing leases on the balance sheet can influence financial ratios used by management, lenders, and investors.
For example, recognizing additional lease liabilities may increase reported financial obligations and affect leverage-related measures.
The impact depends on how the relevant ratio is defined.
Debt and Leverage Measures
Some leverage calculations include lease liabilities, while others distinguish them from conventional borrowing.
For businesses operating many leased locations, recognizing lease obligations may substantially increase reported liabilities.
However, a higher reported liability does not necessarily mean the business has borrowed additional cash.
The recognition reflects obligations already created by the lease agreements.
Current Ratio
The current ratio compares current assets with current liabilities.
Recognizing the current portion of lease liabilities can affect the calculation, depending on the organization's existing balances.
For example, a company with significant lease commitments may report a lower current ratio after recognizing additional current liabilities.
The effect should be considered alongside other working capital obligations.
Business Valuation and Financial Analysis
Analysts may adjust financial metrics to compare companies with different ownership and leasing strategies.
A business leasing most of its locations can have a different asset and liability profile from a company owning similar properties.
Understanding lease-related balances allows analysts to make more informed comparisons.
For a closer examination of these financial effects, see Occupier's lease liabilities guide.
Common Mistakes When Recording Lease Assets and Liabilities
Errors often occur when companies use incomplete contractual data or assume the asset and liability should always have identical balances.
One common issue is including the wrong payments in the liability calculation.
For example, a tenant may mistakenly include variable charges based on future operating expenses when those payments do not qualify for initial recognition.
Another mistake is failing to account for advance payments, incentives, or initial direct costs when measuring the ROU asset.
Businesses may also miss executed amendments that change the accounting lease term or payment schedule.
Incorrect assumptions about renewal options can affect both initial recognition and subsequent reporting.
Finally, treating an ROU asset impairment as automatic forgiveness of the liability can materially misstate the accounts.
The appropriate response is to maintain accurate contract records, review relevant accounting judgments, and reconcile the balances regularly.
Why Reconciliation Matters for Lease Balances
Accurate reporting requires finance teams to explain changes in lease assets and liabilities between reporting dates.
For example, a company's lease liabilities may increase during a quarter even though it made all scheduled rental payments.
The increase might result from newly commenced leases, interest accretion, or modifications to existing agreements.
Similarly, ROU asset balances may decline because of scheduled reductions, impairments, or terminations.
These movements should reconcile to the general ledger and supporting lease accounting schedules.
A lease roll forward report helps organize these transactions and explain changes in reported balances.
This becomes particularly valuable when a business manages numerous locations with different commencement dates, payment structures, and amendments.
Managing Assets and Liabilities Across Multiple Leases
For a company with only a few straightforward agreements, maintaining lease information may be manageable through spreadsheets and controlled accounting schedules.
However, organizations managing dozens or hundreds of leases face additional complexity.
Each agreement can have a different term, discount rate, payment schedule, or amendment history.
Real estate teams may negotiate renewals and modifications, while finance teams are responsible for updating the corresponding accounting records.
When these departments work from different information, asset and liability balances can become outdated.
A centralized process helps ensure that executed agreements, financial assumptions, and supporting documents are available to the appropriate teams.
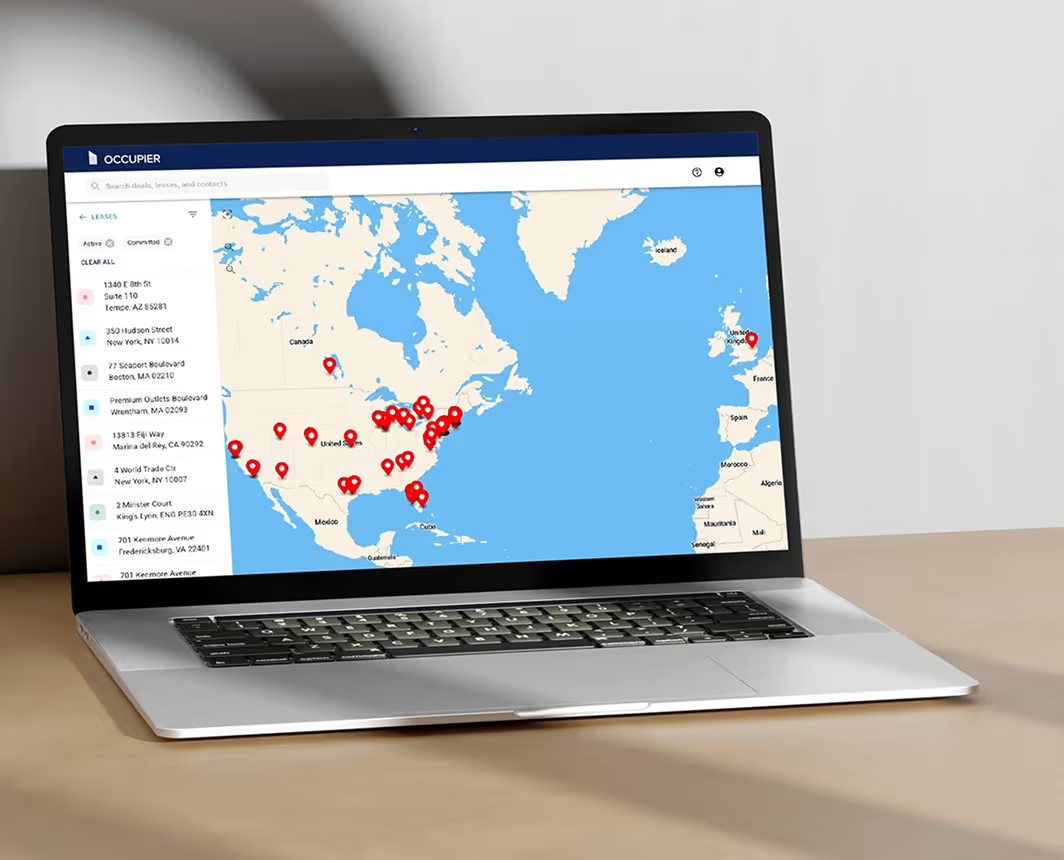
Occupier's lease accounting software supports lease calculations and financial reporting workflows while connecting relevant lease information across real estate and finance teams.
Organizations should establish clear responsibilities for communicating lease changes and reviewing their financial impact.
Frequently Asked Questions About Lease Assets and Liabilities
What is the difference between a lease asset and a lease liability?
A lease asset represents the lessee's right to use an underlying asset during the lease term. A lease liability represents the obligation to make qualifying future payments. Both generally arise from the same lease agreement but are measured and adjusted according to different requirements.
Are lease assets and liabilities always equal?
No. They may be equal at commencement under simplified circumstances, but prepayments, incentives, and initial direct costs can create differences immediately. Their balances can also change differently over time.
Is a right-of-use asset the same as the leased property?
No. An ROU asset represents the contractual right to use the property or equipment, not ownership of the underlying asset.
Are lease liabilities considered debt?
Lease liabilities represent contractual payment obligations. Whether they are included in a particular debt measure depends on the relevant accounting presentation, financial analysis, or contractual definition.
Do operating leases create assets and liabilities under ASC 842?
Yes. Most qualifying operating leases create recognized ROU assets and lease liabilities under ASC 842, subject to applicable exceptions and accounting policy elections.
Can a lease asset decrease while its liability increases?
Yes. For example, ROU asset reductions can occur during the same period that interest accrues on the lease liability. Impairment may also reduce the asset without automatically changing the liability.
Do all lease payments reduce the liability?
No. Payments included in the liability measurement generally reduce that liability when paid, but other amounts, such as certain variable expenses or separately accounted-for services, may be recognized differently.
Lease management that works for real estate and finance
15,000 sq ft
90 days notice
March 2026
Action required