Lease Accounting Guide: Standards, Process & Reporting

What Is Lease Accounting?
Lease accounting refers to the financial reporting process used to recognize and measure lease-related assets, liabilities, expenses, and other financial information.
Lease accounting is the process of recognizing, measuring, and reporting the financial impact of leased assets. For businesses that rent offices, retail stores, warehouses, equipment, or vehicles, it helps explain how lease commitments affect financial statements.
Modern lease accounting standards generally require organizations to recognize most qualifying leases on their balance sheets. This provides greater visibility into the assets businesses use and the financial obligations associated with those agreements.
However, lease accounting involves more than recording rent payments. Finance teams must evaluate lease terms, calculate liabilities, account for changes, and prepare accurate financial reports throughout the lease lifecycle.
Different accounting standards also apply depending on where and how an organization reports. Understanding ASC 842, IFRS 16, GASB 87, and FRS 102 helps businesses determine which requirements apply to their leases and how to maintain compliance.
What Is Lease Accounting?
Lease accounting refers to the financial reporting process used to recognize and measure lease-related assets, liabilities, expenses, and other financial information.
When a company leases commercial space or equipment, it typically receives the right to use an asset for an agreed period in exchange for payments.
For example, a retailer signing a five-year store lease gains the right to occupy the property while committing to future rental payments.
Under modern lease accounting requirements, qualifying arrangements generally result in an asset representing the right to use the property and a corresponding liability representing future payment obligations.
These amounts are measured and reported according to the accounting standards applicable to the organization.
Lease accounting applies to more than commercial real estate. Equipment, vehicles, machinery, and certain arrangements embedded within service contracts may also need to be evaluated.
The purpose is to provide financial statement users with a clearer understanding of an organization's leasing activities and related commitments.
How Does Lease Accounting Work for Lessees?
Lease accounting involves two parties: the lessee, who obtains the right to use an asset, and the lessor, who provides that right.
For commercial tenants, the lessee perspective is particularly important because it determines how leases appear in the company's financial statements.
While requirements vary between standards, most modern lessee accounting processes involve several common steps.
Identifying Lease Agreements
The first step is determining which contracts contain leases.
Obvious examples include agreements for offices, restaurants, warehouses, and retail locations. However, certain equipment or service agreements may also contain lease components.
Finance teams need to evaluate these arrangements under the applicable standard rather than relying only on whether the contract is labeled a lease.
Recognizing Lease Assets and Liabilities
For leases requiring balance sheet recognition, the lessee generally records two important amounts.
A right-of-use (ROU) asset represents the right to use the underlying asset during the lease term.
A lease liability represents the obligation to make future lease payments included in the required measurement.
The lease liability is generally measured using the present value of relevant future payments, while the initial ROU asset incorporates the liability and certain adjustments.
The specific calculations, exemptions, and terminology depend on the applicable accounting standard.
Recording Expenses and Payments
After initial recognition, the organization must account for lease payments, changes in the liability, and the consumption of the right-of-use asset.
The income statement treatment varies between standards.
Under ASC 842, for example, operating and finance leases have different expense recognition patterns. IFRS 16 generally uses a single lessee accounting model for recognized leases.
Finance teams must apply the appropriate treatment rather than assuming every lease produces the same financial results.
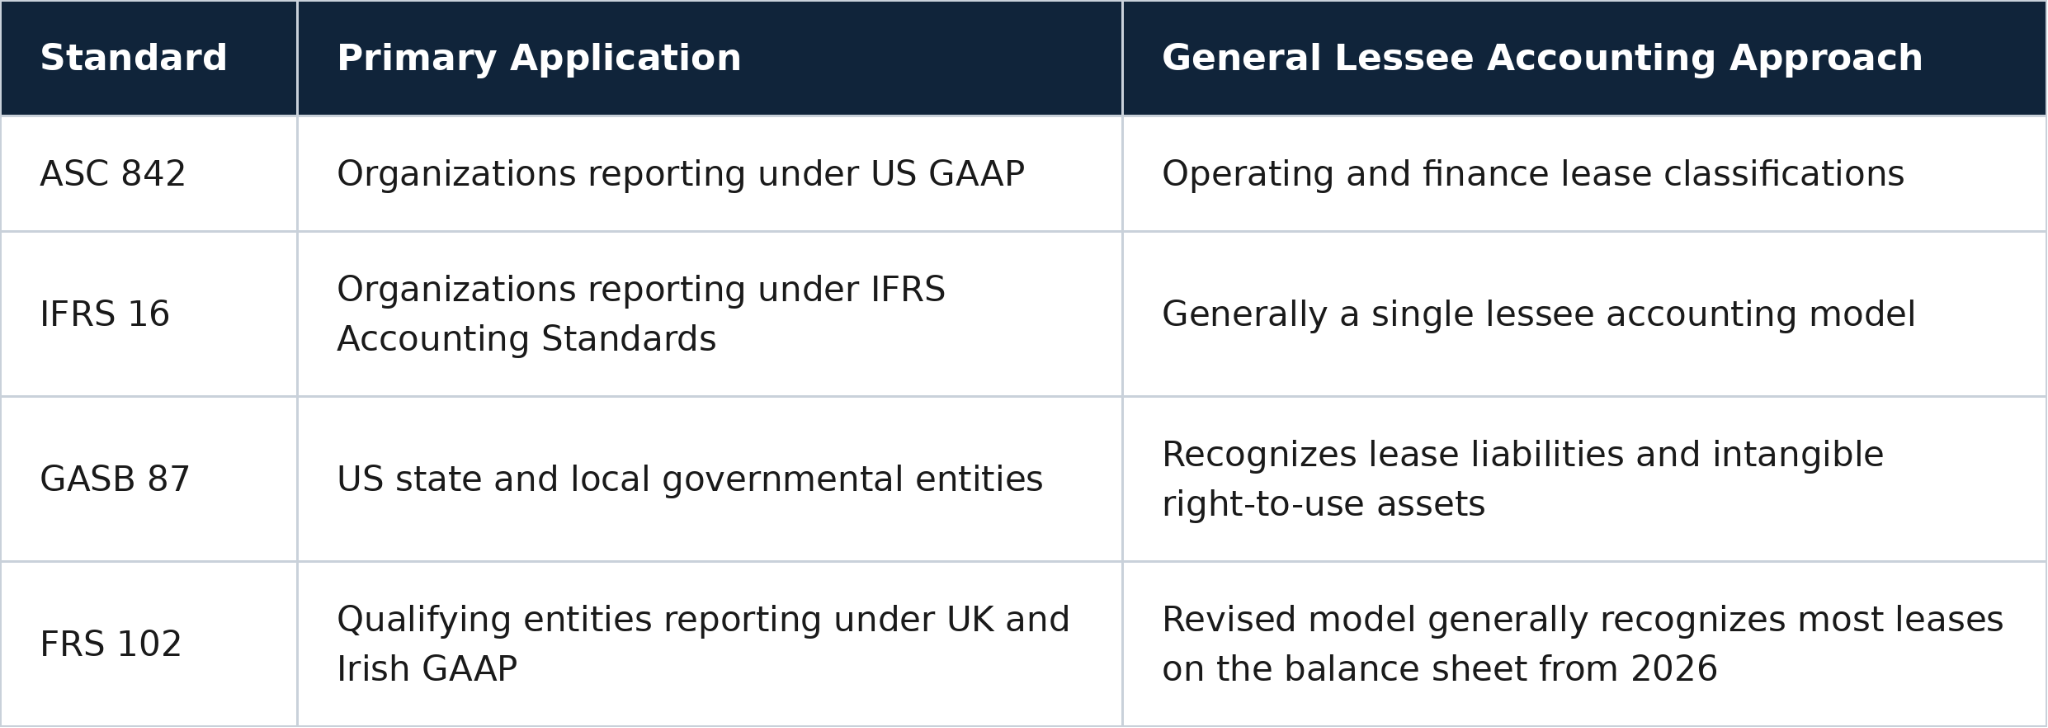
Understanding the Four Major Lease Accounting Standards
Lease accounting standards share the objective of improving financial reporting, but they are not interchangeable.
Different rules apply to US businesses, international organizations, government entities, and companies reporting under UK or Irish accounting requirements.
ASC 842: Lease Accounting Under US GAAP
ASC 842 is the lease accounting standard established by the Financial Accounting Standards Board (FASB) for organizations reporting under US Generally Accepted Accounting Principles.
It replaced ASC 840 and introduced balance sheet recognition for most operating leases in addition to finance leases.
One important feature is that ASC 842 retains two lessee classifications: operating leases and finance leases.
Although both generally result in right-of-use assets and lease liabilities, the expense recognition and presentation requirements differ.
For commercial tenants, ASC 842 compliance depends on accurate lease information, including commencement dates, payment schedules, amendments, and relevant options.
Our detailed guide to ASC 842 explains the specific accounting requirements, classification criteria, and implementation considerations.
IFRS 16: International Lease Accounting
IFRS 16 is issued by the International Accounting Standards Board (IASB) and applies to organizations reporting under IFRS Accounting Standards.
Like ASC 842, it generally requires lessees to recognize right-of-use assets and lease liabilities for qualifying agreements.
However, IFRS 16 uses a single lessee accounting model rather than maintaining the same operating-versus-finance distinction used under ASC 842.
It also provides exemptions for qualifying short-term leases and leases of low-value underlying assets.
These differences can affect expense recognition and financial reporting for multinational companies.
For example, a business with operations reporting under both US GAAP and IFRS may need different accounting schedules for the same underlying lease.
Businesses managing both frameworks can review the detailed IFRS 16 comparison to understand where the standards differ.
GASB 87: Government Lease Accounting
GASB 87 applies to US state and local governmental entities, including many public universities, school districts, and other government organizations.
The Governmental Accounting Standards Board developed the standard to improve the reporting of leasing activities in government financial statements.
Under GASB 87, governmental lessees generally recognize a lease liability and an intangible right-to-use lease asset for qualifying arrangements.
The standard follows a single-model approach based on the principle that a lease finances the right to use an underlying asset.
However, GASB 87 contains requirements and exceptions specific to governmental reporting. It should not be treated as identical to ASC 842 or IFRS 16.
Organizations subject to these requirements can review Occupier's guide to GASB 87 for additional context.
FRS 102: Lease Accounting in the UK and Ireland
FRS 102 is a financial reporting standard used by qualifying organizations in the United Kingdom and Republic of Ireland.
It applies to entities using that reporting framework rather than IFRS, FRS 101, or FRS 105.
The Financial Reporting Council's Periodic Review 2024 introduced significant changes to lessee accounting, with the principal effective date of January 1, 2026.
Under the revised requirements, lessees generally recognize right-of-use assets and lease liabilities for most leases, with specified exemptions.
This represents an important change from the previous model, under which operating leases were generally accounted for differently from finance leases.
Businesses preparing financial statements under FRS 102 should therefore ensure their lease records, accounting policies, and reporting processes reflect the requirements applicable to their reporting periods.
Occupier's FRS 102 guide provides a more detailed overview of the standard and its implications.
How Lease Accounting Affects Financial Statements
Lease accounting affects the balance sheet, income statement, and cash flow statement, although the treatment varies by reporting framework.
Balance Sheet
For most recognized leases, companies report both a lease liability and a right-of-use asset.
This makes leasing commitments more visible to investors, lenders, auditors, and other financial statement users.
For example, a retailer managing dozens of leased locations may have significant future rental commitments even though it owns relatively little real estate.
Recognizing qualifying leases provides a clearer picture of those obligations.
Income Statement
Lease-related expenses depend on the relevant standard and accounting classification.
Under ASC 842, operating leases generally produce a single lease cost, while finance leases involve separate interest and amortization components.
IFRS 16 generally recognizes depreciation of the right-of-use asset and interest on the lease liability for recognized leases.
These differences matter when comparing profitability measures and financial results across reporting frameworks.
Cash Flow Statement
Lease payments also affect cash flow reporting.
The classification of principal payments, interest, and other lease-related amounts depends on the applicable accounting standard and the nature of the lease.
As a result, businesses reporting under multiple standards may need different presentations even when the underlying contractual cash payments are similar.
A Simple Lease Accounting Example
Consider a company signing a three-year equipment lease with fixed monthly payments of $4,000.
Over the full term, the company is contractually scheduled to pay $144,000.
However, the initial lease liability is not necessarily $144,000.
Instead, the finance team generally discounts the relevant future lease payments to their present value using an appropriate discount rate under the applicable standard.
Assuming all payments qualify for inclusion, the initial liability would be lower than the undiscounted total when a positive discount rate applies.
The company would also recognize a corresponding right-of-use asset, adjusted for applicable prepayments, incentives, and other qualifying amounts.
Over the lease term, the liability decreases as payments are made, while the organization recognizes the appropriate lease expenses.
This illustrates the basic relationship between contractual payments and financial reporting. Actual calculations require the applicable accounting policies, payment timing, and lease-specific assumptions.
Common Lease Accounting Challenges
Even after adopting the relevant standards, maintaining accurate lease accounting can be difficult.
One challenge is keeping lease information complete.
A business may have executed agreements stored in one system while amendments, rent changes, and termination notices are maintained elsewhere.
If finance does not receive those updates, accounting schedules may no longer reflect the current contractual terms.
Another challenge is maintaining consistent judgments about renewal options, discount rates, and other assumptions. These decisions can affect recognized assets, liabilities, and expenses.
Lease modifications also require attention.
For example, a retailer may renegotiate its rent or extend a store lease. Depending on the changes and applicable accounting standard, finance may need to reassess or remeasure the existing balances.
Businesses with international operations face the additional challenge of maintaining records that support different reporting frameworks.
Clear processes and consistent information become increasingly important as the portfolio grows.
Best Practices for Accurate Lease Accounting
Successful lease accounting depends on more than understanding the standards. Businesses also need reliable processes for collecting information, reviewing changes, and preparing financial reports.
Start by maintaining a complete inventory of lease agreements, including relevant amendments and supporting documents.
Finance teams should establish consistent accounting policies and document significant judgments, including lease terms, discount rates, and applicable exemptions.
Regular reconciliations help confirm that accounting schedules agree with the general ledger and the underlying lease records.
Organizations should also define how information moves between real estate and finance departments.
For example, when a real estate manager negotiates an extension or termination, finance needs enough information to evaluate the accounting impact.
Finally, maintain an audit trail of calculations, changes, approvals, and supporting documentation.
These practices help businesses respond to reporting requirements and reduce the risk of discovering incomplete information during an audit.
How Lease Accounting Software Supports Compliance
Managing lease accounting through spreadsheets may be practical for some smaller portfolios, but complexity increases when organizations have multiple locations, frequent amendments, or more than one reporting standard.
Lease accounting software can help centralize relevant lease data and support the calculations required for financial reporting.
Common capabilities include present-value calculations, amortization schedules, journal entries, lease modifications, disclosure reporting, and audit histories.
However, software does not replace professional accounting judgment.
Teams must still verify contract information, select appropriate assumptions, and review financial results.
Occupier's lease accounting software connects lease information with accounting workflows and supports ASC 842, IFRS 16, GASB 87, and FRS 102.
For commercial tenants, connecting real estate updates with finance records can help reduce repetitive data entry and make changes easier to review throughout the lease lifecycle.
Frequently Asked Questions About Lease Accounting
What Is Lease Accounting in Simple Terms?
Lease accounting is the process of recording how renting property or equipment affects a company's financial statements. It includes recognizing applicable lease assets, liabilities, payments, and expenses.
What Are the Main Lease Accounting Standards?
The main standards discussed for lessees include ASC 842 for US GAAP, IFRS 16 for international reporting, GASB 87 for US state and local governments, and FRS 102 for qualifying organizations in the UK and Ireland.
What Is the Difference Between Lease Accounting and Lease Management?
Lease accounting focuses on financial recognition, measurement, and reporting. Lease management covers broader responsibilities such as organizing agreements, tracking deadlines, monitoring obligations, and managing the lease portfolio.
Do All Leases Have to Be Recorded on the Balance Sheet?
No. Modern accounting standards generally require recognition of most qualifying leases, but exemptions, exclusions, and recognition requirements vary. Short-term leases may qualify for simplified treatment, depending on the standard.
Can a Company Use More Than One Lease Accounting Standard?
Yes. Multinational organizations or groups with different reporting requirements may need information prepared under more than one accounting framework. The relevant standards depend on each entity's reporting obligations.
Why Is Lease Accounting Important for Commercial Tenants?
It helps businesses maintain accurate financial statements, understand lease obligations, comply with applicable reporting standards, and provide reliable information to lenders, auditors, and other stakeholders.
Lease management that works for real estate and finance
15,000 sq ft
90 days notice
March 2026
Action required