Lease Amortization Schedule: Free Excel Template & Examples
What is a lease amortization schedule?
A lease amortization schedule tracks the lease liability and ROU asset over the lease term. It generally shows beginning balances, payments, interest or accretion, liability reduction, ROU asset activity, and ending balances.
Creating an accurate lease amortization schedule is an important part of lease accounting under ASC 842. Finance teams use these schedules to track lease liabilities, right-of-use assets, payments, interest, and recurring journal entries throughout the lease term. This guide explains how to build a lease amortization schedule in Excel, which inputs and formulas are required, and how the calculations differ between operating and finance leases. You can also use Occupier’s free Excel template if you prefer a ready-to-use schedule.
What is a lease amortization schedule?
A lease amortization schedule is a period-by-period record of how a lease liability and right-of-use (ROU) asset change from commencement through the end of the lease.
Each row usually represents one accounting period and shows amounts such as the beginning lease liability, lease payment, interest or liability accretion, reduction of the liability, ending balance, and related ROU asset activity.
Under ASC 842, the schedule supports the calculations used for monthly or annual journal entries and helps finance teams reconcile lease balances reported on the balance sheet.
The schedule begins with the initial lease liability, which is generally based on the present value of qualifying future lease payments. From there, the liability is rolled forward each period until the lease term ends.
What information do you need to create a lease amortization schedule?
Before creating the schedule, gather the key lease assumptions from the agreement.
These typically include:
- Measurement date: Usually the lease commencement date or applicable transition or remeasurement date.
- Lease commencement date: The date the underlying asset becomes available for use.
- Lease expiration date: The final date included in the lease term.
- Lease term: The number of months or other periods included in the accounting lease term.
- Lease payments: Fixed and other qualifying payments included in the lease liability.
- Discount rate: The rate used to calculate the present value of lease payments.
- Payment timing: Whether payments occur at the beginning or end of each period.
- Initial direct costs: Qualifying incremental costs that would not have been incurred without executing the lease.
- Lease incentives: Amounts or concessions provided by the landlord.
- Prepaid lease payments: Payments made before or at commencement.
- Lease classification: Whether the lease is classified as operating or finance under ASC 842.
These inputs determine the initial lease liability, ROU asset, and subsequent accounting.
How do you calculate the initial lease liability?
The initial lease liability is generally the present value of the lease payments that have not yet been paid as of the measurement date.
In simplified form:
Lease Liability = Present Value of Remaining Lease Payments
The present value calculation depends on:
- Payment amount
- Number of payment periods
- Payment timing
- Discount rate
For example, assume a company signs a five-year lease requiring annual payments of $50,000 at the end of each year and uses a 5% discount rate.
The present value can be calculated in Excel using:
=PV(5%,5,-50000,0,0)
The initial lease liability is approximately:
$216,474
That amount becomes the opening liability in the lease amortization schedule.
For a deeper explanation of the present value calculation, see Occupier's guide to calculating the present value of lease payments.
How do you calculate the initial ROU asset?
The initial ROU asset generally begins with the lease liability and is adjusted for certain amounts associated with the lease.
A simplified formula is:
Initial ROU Asset = Lease Liability + Prepaid Lease Payments + Initial Direct Costs - Lease Incentives
Assume the example above also includes:
- Initial lease liability: $216,474
- Initial direct costs: $5,000
- Prepaid rent: $10,000
- Lease incentive received: $15,000
The initial ROU asset would be:
$216,474 + $5,000 + $10,000 - $15,000 = $216,474
The exact calculation depends on the lease terms and timing of each adjustment.
You can learn more about the asset side of the calculation in Occupier's guide to ROU assets.
How do you build a lease amortization schedule in Excel?
Once you have the opening lease liability and ROU asset, build the schedule period by period.
Step 1: Create your columns
A basic lease liability schedule should include:
- Period
- Payment date
- Beginning lease liability
- Interest or liability accretion
- Lease payment
- Liability reduction
- Ending lease liability
You will also need columns for the ROU asset calculations.
Step 2: Enter the opening lease liability
The beginning balance for the first period is the present value of the remaining lease payments.
Using our earlier example:
Beginning Lease Liability = $216,474
Step 3: Calculate periodic interest
For annual payments using a 5% annual discount rate:
Interest = Beginning Lease Liability × 5%
For the first year:
$216,474 × 5% = $10,824
For monthly schedules, convert the annual rate into the appropriate periodic rate.
Step 4: Calculate the liability reduction
The payment first covers the interest or accretion recognized for the period. The remaining amount reduces the lease liability.
Liability Reduction = Lease Payment - Interest
Using the example:
$50,000 - $10,824 = $39,176
Step 5: Calculate the ending liability
Ending Lease Liability = Beginning Liability - Liability Reduction
Therefore:
$216,474 - $39,176 = $177,298
The ending liability becomes the next period's beginning balance.
Continue the process through the final period until the lease liability reaches zero, subject to rounding.
Download the free Lease Amortization Schedule Excel Template
You do not need to build every formula manually.
Occupier's Lease Amortization Schedule Excel Template provides a structured spreadsheet for calculating lease liabilities, interest, payments, and ROU asset balances.
Use the template when you want the working Excel model.
Use this article when you need to understand how the calculations work and why each input matters.
Download the free Excel template
Screenshot update
Replace the existing screenshot here with a current image of the downloadable Excel template showing the lease inputs, beginning balances, and first several periods of the amortization schedule.
How does an operating lease amortization schedule work?
Under ASC 842, operating leases are recognized on the balance sheet with both an ROU asset and lease liability.
For an operating lease, the income statement generally shows a single lease expense recognized on a straight-line basis over the lease term.
The lease liability still follows the effective interest method:
Beginning Liability + Accretion - Payment = Ending Liability
The ROU asset reduction is then calculated so that the combined lease expense remains straight-line.
A simplified relationship is:
ROU Asset Reduction = Straight-Line Lease Expense - Liability Accretion
Operating lease example
Assume:
- Five-year lease
- Annual payments: $50,000
- Payments made at year-end
- Discount rate: 5%
- Initial lease liability: $216,474
- No incentives, prepaid rent, or initial direct costs
- Total undiscounted payments: $250,000
The straight-line annual lease expense is:
$250,000 ÷ 5 = $50,000
For Year 1:
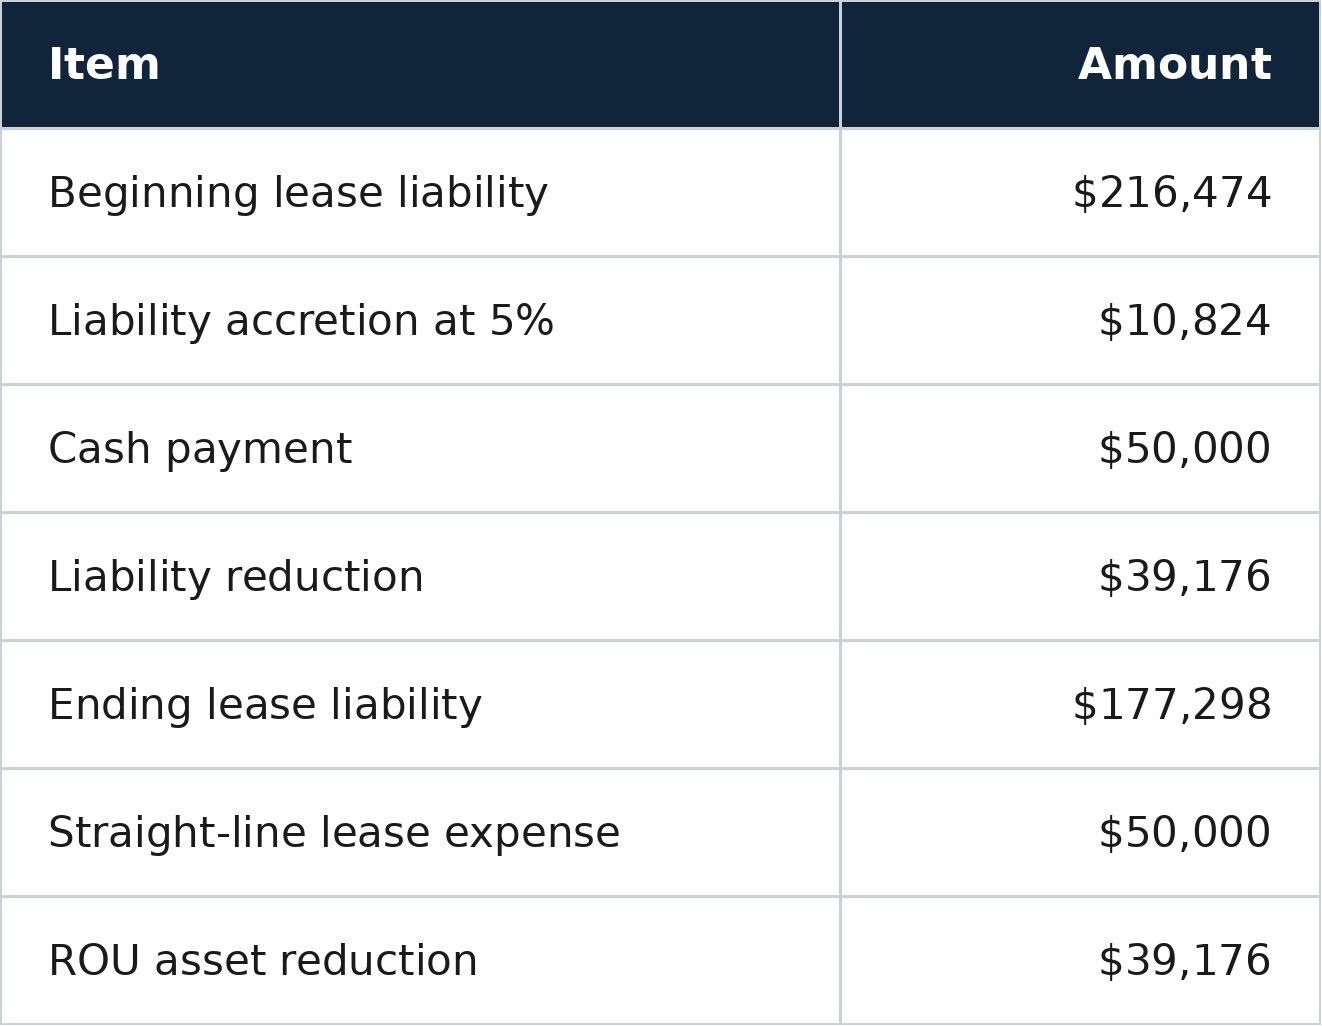
The liability accretion changes each period as the liability declines. The ROU asset reduction changes correspondingly so the total operating lease expense remains straight-line.
Screenshot update
Add a current operating lease screenshot showing beginning liability, accretion, payment, ending liability, ROU asset activity, and straight-line lease expense.
How does a finance lease amortization schedule work?
A finance lease uses the same basic present value approach to establish the initial lease liability, but the subsequent expense pattern differs.
For a finance lease:
- Interest expense is recognized separately using the effective interest method.
- The ROU asset is generally amortized separately, usually on a straight-line basis over the applicable amortization period.
- Interest expense is higher earlier in the lease and declines as the liability decreases.
Finance lease example
Using the same simplified assumptions:
- Initial lease liability: $216,474
- Initial ROU asset: $216,474
- Five-year lease
- Annual payment: $50,000
- Discount rate: 5%
Assume the ROU asset is amortized straight-line over five years.
Annual ROU asset amortization:
$216,474 ÷ 5 = $43,295
For Year 1:
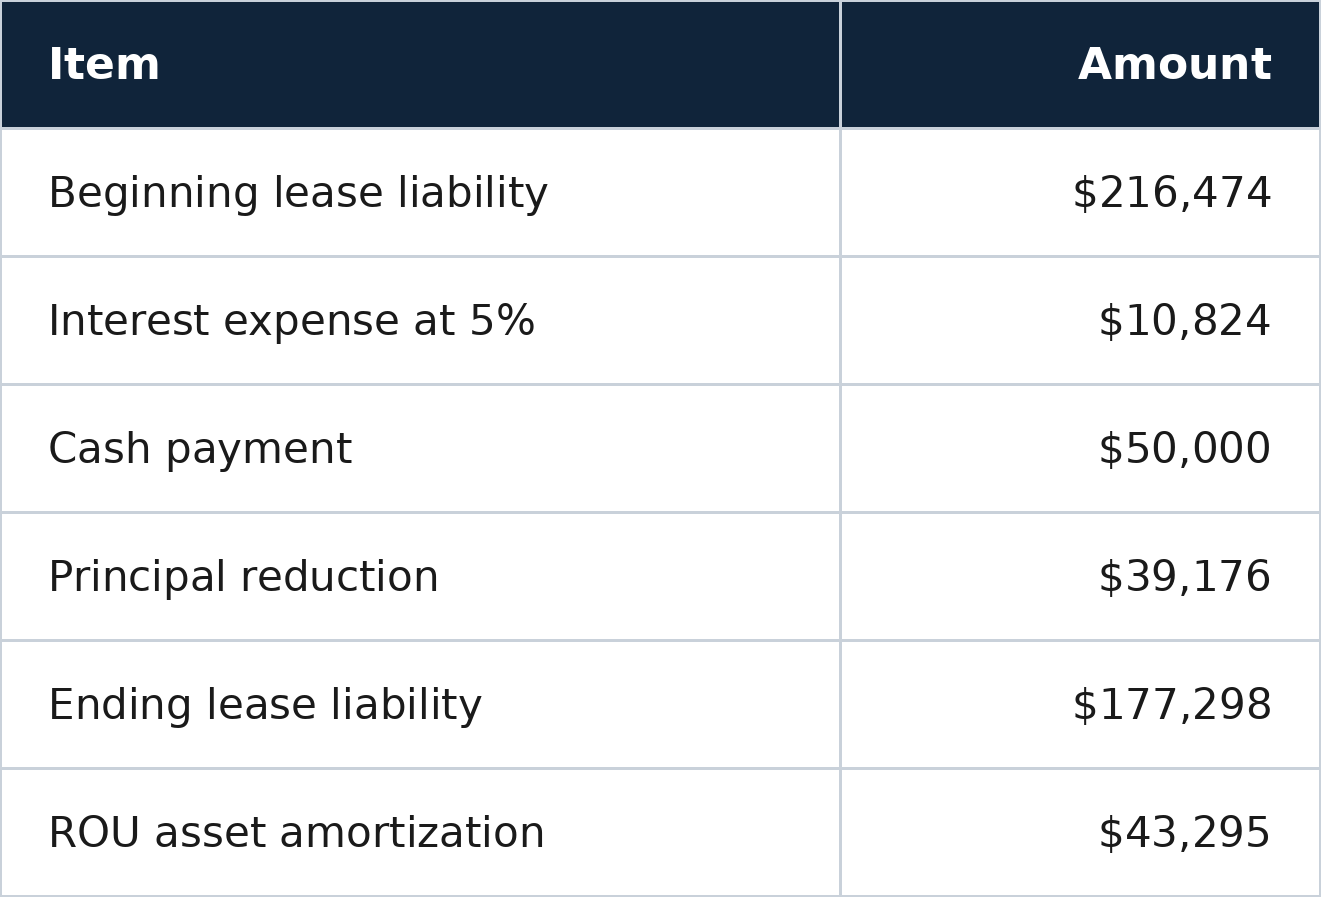
The finance lease therefore produces separate interest expense and ROU asset amortization expense, unlike the single lease expense recognized for an operating lease.
Operating lease vs. finance lease amortization schedule
The initial lease liability calculation can be similar for operating and finance leases, but expense recognition differs.
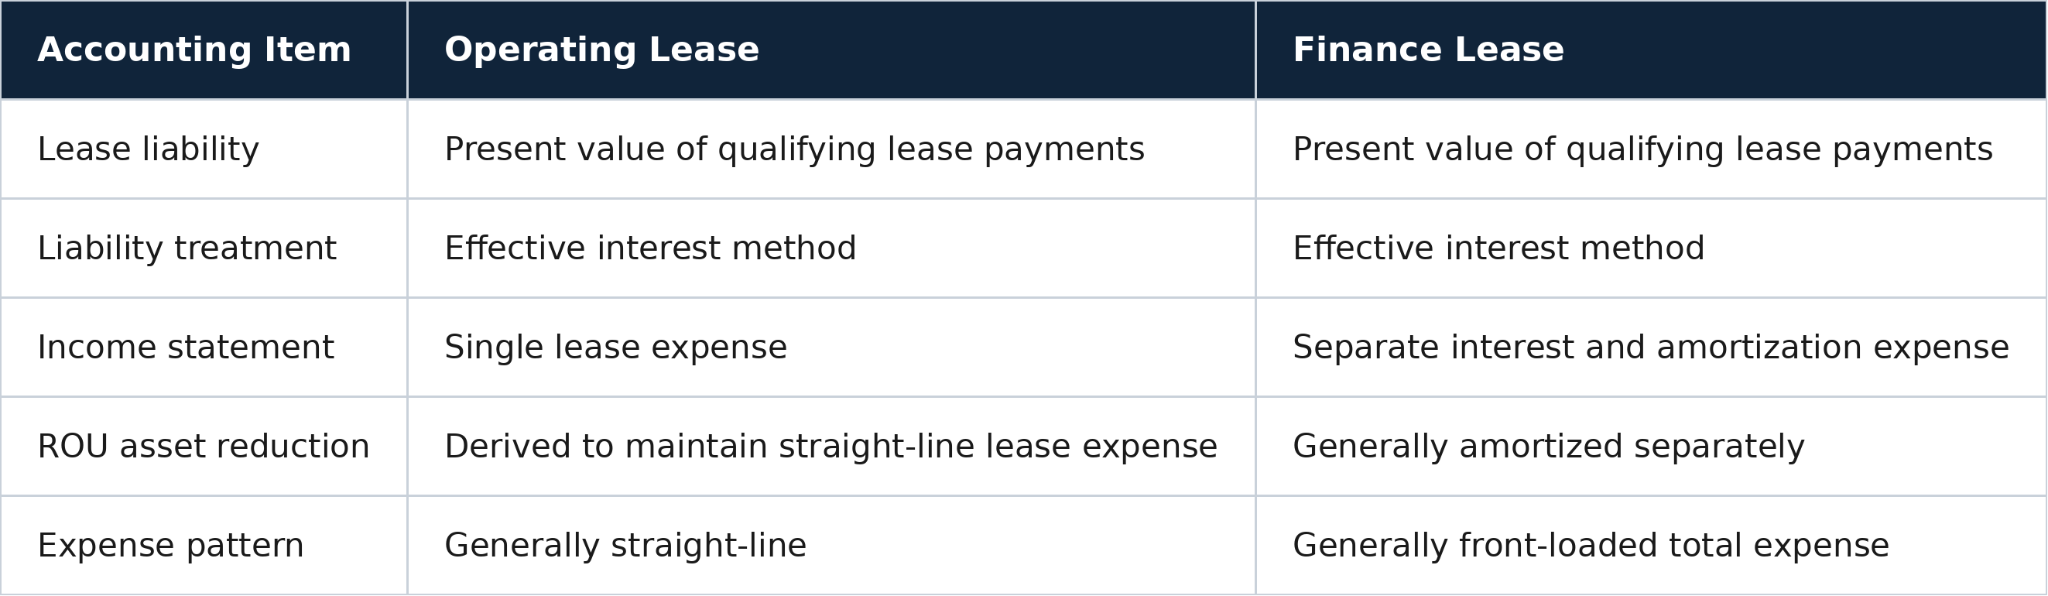
This classification difference is one of the main reasons finance teams need the correct lease type before completing the schedule.
What does Occupier's Excel template include?
The downloadable Excel template provides the fields and schedules needed to model a lease under ASC 842.
Lease inputs
These include:
- Measurement date
- Commencement date
- Expiration date
- Lease term
- Annual discount rate
- Periodic discount rate
- Initial direct costs
- Lease incentives
- Prepaid rent
- Payment timing
- Lease classification
Beginning balances
The template helps establish:
- Initial lease liability
- Initial ROU asset
- Remaining lease costs
Lease liability schedule
The schedule tracks:
- Beginning liability
- Liability accretion or interest
- Lease payments
- Liability reduction
- Ending liability
ROU asset activity
The template also tracks how the ROU asset changes through the lease term according to the applicable lease classification.
Journal entry support
The completed schedule provides the amounts finance teams need to prepare recurring lease accounting journal entries.
Why is a lease amortization schedule important?
A lease amortization schedule supports several parts of the accounting process.
Accurate journal entries
Each accounting period relies on the schedule to determine the appropriate lease liability, ROU asset, lease expense, amortization, and interest amounts.
Balance sheet reconciliation
Ending lease liability and ROU asset balances can be reconciled against the general ledger.
Audit support
Auditors may request lease schedules to verify calculations, discount rates, payment assumptions, and financial statement balances.
Forecasting
The schedule shows future payments and liability balances, helping finance teams understand upcoming lease obligations.
Lease modifications
If a lease is extended, shortened, terminated, or otherwise modified, the schedule may need to be remeasured using updated assumptions.
What happens when spreadsheets become difficult to manage?
Excel can work well for a small number of straightforward leases.
As the portfolio grows, finance teams must manage:
- Multiple payment structures
- Rent escalations
- Lease modifications
- Terminations
- Remeasurements
- Discount rates
- Multiple entities
- Audit trails
- Journal entries
A manual formula or version-control error can affect multiple reporting periods.
Occupier's lease accounting software calculates ROU assets, lease liabilities, amortization schedules, and journal entries from the underlying lease data, helping finance teams reduce spreadsheet maintenance as portfolios become more complex.
What should finance teams remember about lease amortization schedules?
A reliable lease amortization schedule begins with accurate lease data.
Finance teams need to identify the correct lease term, payment schedule, discount rate, payment timing, adjustments to the ROU asset, and lease classification before calculating the schedule.
From there, the lease liability is rolled forward each period based on interest or accretion and payments.
The biggest difference between operating and finance leases is not the initial liability calculation but how the ROU asset and lease expense are recognized after commencement.
For teams building schedules manually, download Occupier's free Lease Amortization Schedule Excel Template.
For larger portfolios, Occupier can automate the schedules and the accounting entries they support.
Frequently Asked Questions
What is a lease amortization schedule?
A lease amortization schedule tracks the lease liability and ROU asset over the lease term. It generally shows beginning balances, payments, interest or accretion, liability reduction, ROU asset activity, and ending balances.
How do you create a lease amortization schedule in Excel?
Start by calculating the present value of the future lease payments to determine the opening liability. Then create a row for each accounting period showing the beginning liability, periodic interest or accretion, payment, liability reduction, and ending balance.
Where can I download a lease amortization schedule Excel template?
Occupier provides a free Lease Amortization Schedule Excel Template in its Resources library.
Are operating and finance lease amortization schedules different?
Yes. Both generally use the effective interest method for the lease liability, but operating leases typically recognize one straight-line lease expense. Finance leases recognize interest expense and ROU asset amortization separately.
What is the initial balance in a lease amortization schedule?
The initial lease liability is generally the present value of qualifying remaining lease payments as of the measurement date. The initial ROU asset begins with that liability and is adjusted for items such as prepaid payments, initial direct costs, and lease incentives.
Does a lease amortization schedule need to reach zero?
The lease liability should generally reduce to zero by the end of the lease term after all scheduled payments have been recorded, subject to rounding and any subsequent modifications or remeasurements.
Lease management that works for real estate and finance
15,000 sq ft
90 days notice
March 2026
Action required